Global AI Competition & Innovation Lab
Global AI Competition & Innovation Lab
Global AI Competition & Innovation Lab
The economics of Artificial Intelligence.
The economics of Artificial Intelligence.
Competition, competitiveness, and creative destruction.
Our scholars are based at
' style='clip-rule:nonzero' transform='translate(-14.97 -16.86)scale(.35278)'%3E%3Cpath d='M50.65 48.98H68.3l.81-.01h1.8q1.28 0 4.27-.13l.74-.03a39 39 0 0 0-.13 2.98l-.01 2.37v14.82c0 7.91-1.8 10.6-10.34 14.82-.38.18-4.73 2.36-5.18 2.6l-.43.23-.43.23-.44-.23-.43-.23c-1.8-.94-3.62-1.77-5.03-2.46-7.82-3.84-10.33-6.56-10.33-14.96V56.41l-.02-2.25V51.8c-.02-1.43-.03-1.9-.14-2.98l.74.03c1.97.08 3.43.13 4.28.13h2.61' style='fill:%23211e1e;fill-opacity:1;fill-rule:nonzero;stroke:none'/%3E%3C/g%3E%3Cg clip-path='url(%23b)' style='clip-rule:nonzero' transform='translate(-14.97 -16.86)scale(.35278)'%3E%3Cpath d='m59.4 86.09 3.37-1.65.09-.03-.03-.08V68.86l-.03-.09.1.02h12.17l.11.03-.03-.13v-6.56l.03-.1-.1.02H62.9l-.1.02.02-.1v-12.3l.03-.11-.1.03H56.1l-.1-.03.02.1v12.3l.03.11-.1-.02H43.87l-.1-.03.03.1v6.63l-.03.07.1-.03h12.08l.1-.02-.03.12V84.3l-.03.13.08.02z' style='fill:%23fff;fill-opacity:1;fill-rule:nonzero;stroke:none'/%3E%3C/g%3E%3Cg clip-path='url(%23c)' style='clip-rule:nonzero' transform='translate(-14.97 -16.86)scale(.35278)'%3E%3Cpath d='m43.93 49.59-.16-.03.03.12v12.31l-.03.1.15-.04h12.02l.1.04-.02-.11V49.64l.02-.08-.1.03z' style='fill:%23ee2e4f;fill-opacity:1;fill-rule:nonzero;stroke:none'/%3E%3C/g%3E%3Cpath d='M-64.45 111.82h-.05v4.41h4.36l-.01-.03v-4.39l-.03.01z' style='fill:%23ee2e4f;fill-opacity:1;fill-rule:nonzero;stroke:none;stroke-width:.35277778' transform='translate(71.69 -111.2)'/%3E%3Cg clip-path='url(%23d)' style='clip-rule:nonzero' transform='translate(-14.97 -16.86)scale(.35278)'%3E%3Cpath d='M56 68.8H43.83l-.07-.04.03.08v.74c0 6.76 2.26 10.05 9.2 13.4l2.2 1.07.77.36.06.07V68.86l.02-.1z' style='fill:%23ee2e4f;fill-opacity:1;fill-rule:nonzero;stroke:none'/%3E%3C/g%3E%3Cpath d='m-64.48 118.6-.02-.01v5.53l.02-.03.25-.11c3.33-1.57 4.08-2.5 4.08-5.08v-.31h-4.33' style='fill:%23ee2e4f;fill-opacity:1;fill-rule:nonzero;stroke:none;stroke-width:.35277778' transform='translate(71.69 -111.2)'/%3E%3Cpath d='m-70.51 116.44.02.03.03.03.04.03.02.03-.01.02-.04.03-.03.03-.01.02v.03q0 .44.24.64l.03.03-.03.01h-.1l-.06-.02h-.04l-.04.26h-.05l-.04-.26h-.03l-.06.01-.08.01h-.06q0-.02.02-.03l.05-.04q.06-.04.13-.2.04-.06.04-.11 0-.13.03-.14v-.21l-.04-.03-.03-.03-.02-.02.03-.03c.05-.05.06-.05.09-.1m1.41.01.08.1.03.02-.02.02-.04.03-.03.03-.01.02v.05l.01.14c.01.2.12.42.23.48l.04.02-.02.02h-.12l-.06-.02h-.04l-.04.26h-.04l-.04-.26h-.04l-.06.01-.07.01h-.07q0-.02.02-.03l.05-.04c.05-.04.07-.06.14-.2l.04-.11q0-.13.02-.14v-.21l-.04-.03-.03-.03-.02-.02.03-.03.04-.03.03-.03.02-.03m-.7.82.03.03.02.03.04.04.03.03-.02.01-.03.03-.04.03v.05q0 .45.24.64l.03.03-.03.02h-.04l-.07-.01-.06-.02h-.04l-.03.27h-.05l-.04-.27h-.04l-.06.02h-.14l.02-.03.06-.04c.12-.1.2-.34.2-.6v-.04l-.01-.02-.04-.03-.03-.03-.02-.01zm1.41 0q.04.06.12.13l-.02.01-.03.03-.04.03v.05c0 .2.05.45.12.53l.07.08.04.03.04.03-.03.02h-.04l-.07-.01-.06-.02h-.04l-.04.27h-.05l-.03-.27h-.04l-.06.02h-.14q0-.02.02-.03l.05-.04c.12-.1.2-.34.2-.6v-.06l-.04-.02-.03-.04-.02-.01.03-.03.04-.04.02-.03zm.7-.82.09.1.03.02-.02.02-.03.03-.03.03-.02.02v.05l.01.14c.01.19.13.42.24.48l.03.02q0 .02-.02.02h-.12l-.06-.02h-.03l-.04.26h-.05l-.04-.26h-.04l-.06.01-.07.01h-.06l.01-.03.06-.04c.05-.04.06-.06.13-.2l.04-.11q0-.13.02-.14v-.14l.01-.05-.01-.02-.03-.03-.04-.03-.02-.02.03-.03.04-.03.03-.03zm4-.01.03.03.03.03.03.04.03.03-.02.01-.03.04-.03.03-.01.01v.03c0 .3.1.56.24.64l.03.03v.01h-.06l-.17-.02-.04.26h-.05l-.04-.26-.17.03h-.03l-.03-.01q0-.03.03-.04c.14-.07.24-.34.24-.64v-.03l-.01-.01-.03-.03-.04-.04-.02-.01.04-.03.03-.04.03-.03zm1.42 0 .02.03.03.03.04.04.02.03-.01.01-.04.04-.03.03-.01.01v.03c0 .3.1.56.24.64l.03.03v.01h-.06l-.17-.02-.04.26h-.05l-.04-.26-.18.03q-.05 0-.05-.02l.03-.03.12-.11q.09-.15.09-.23 0-.13.03-.14v-.2l-.1-.08.04-.03.03-.04.03-.03zm-.71.82.03.03.03.04.03.03.03.03-.02.01-.03.04-.04.03v.2c.02.2.12.42.24.49q.03 0 .03.03l-.03.01h-.03l-.18-.03-.03.27h-.05l-.04-.27-.19.03q-.05 0-.04-.02l.03-.02.11-.12q.1-.16.1-.22 0-.14.02-.15v-.14l.01-.05-.01-.01-.03-.03-.04-.04-.01-.01.03-.03zm1.42 0 .03.03.03.04.03.03.03.03-.01.01-.04.04-.03.03-.01.01v.19c.02.2.13.42.24.49q.03 0 .03.03l-.03.01h-.03l-.17-.03-.04.27h-.05l-.04-.27-.18.03q-.05 0-.05-.02l.03-.02.12-.12.1-.22q0-.13.02-.15v-.2l-.04-.03-.04-.04-.01-.01.03-.03zm.71-.82.03.03.03.03.03.04.03.03-.02.01-.03.04-.04.03v.04c0 .3.1.56.24.64l.03.03v.01h-.07l-.17-.02-.03.26h-.06l-.03-.26-.19.03q-.05 0-.05-.02l.04-.03.11-.11q.1-.15.1-.23 0-.13.02-.14v-.14l.01-.05-.01-.01-.03-.03-.04-.04-.02-.01.03-.03.04-.04.03-.03zm-5.49 3.83.09.1.03.03-.02.01-.03.03-.03.04-.02.01v.05l.01.14c0 .12.06.27.12.36q.07.1.12.12l.03.03q.01.02-.05.02l-.18-.03-.04.26h-.05l-.04-.26-.17.03h-.03q-.04 0-.03-.02l.03-.03.11-.12q.1-.16.1-.22 0-.13.02-.14v-.14l.01-.05-.01-.01-.03-.04-.04-.03-.02-.01.03-.03.04-.04.03-.03zm1.33 0 .11.13-.01.01-.04.03-.03.04-.01.01v.19c.01.12.06.27.12.36q.07.1.12.12l.03.03q.01.02-.05.02l-.18-.03-.04.26h-.05l-.04-.26-.17.03h-.03q-.03 0-.03-.02l.03-.03.11-.12q.1-.16.1-.22 0-.13.02-.14l.01-.14v-.06l-.07-.07-.02-.01.03-.03.03-.04.03-.03zm-.68 1.2.02.04.03.02.04.04.03.03-.02.01-.04.04-.02.03-.02.01v.05l.01.14c.01.2.13.43.24.48l.03.03v.01l-.03.01h-.03l-.08-.01-.06-.01h-.04l-.04.26h-.04l-.04-.27h-.04l-.06.02h-.07l-.04.01q-.03 0-.03-.02l.03-.03.12-.11q.1-.17.1-.23 0-.13.02-.14v-.14l.01-.05-.01-.01-.04-.03-.03-.04-.02-.01.03-.03.04-.04.03-.03zm-.66 1.22.03.04.03.03.03.03.03.04h-.01l-.04.04-.03.03-.01.02v.18c.02.2.13.42.24.49l.03.03-.03.01h-.03l-.17-.02-.04.26h-.05l-.04-.26-.18.02q-.05 0-.05-.02l.03-.02.12-.12q.1-.16.1-.22 0-.14.02-.15v-.2l-.04-.03-.03-.03-.02-.02.03-.03.03-.03.03-.03zm1.34 0 .02.04.03.03.03.04.03.02-.01.02-.04.03-.03.03-.01.02v.18a1 1 0 0 0 .12.37q.07.09.12.12.03 0 .03.03l-.05.01-.18-.02-.04.26h-.05l-.04-.26-.17.02h-.03l-.03-.01.03-.03.11-.12q.1-.16.1-.22 0-.14.02-.15l.01-.14v-.06l-.04-.03-.03-.03-.02-.02.03-.03.03-.03.03-.03zm-.68-3.63.02.03.03.03.04.04.03.03-.02.01-.04.04-.02.03-.02.01v.05l.01.14c.01.2.13.44.24.48l.03.03q0 .02-.05.02l-.19-.03-.04.27h-.04l-.04-.27-.17.03h-.04l-.03-.01q0-.02.03-.04l.12-.11q.1-.16.1-.23 0-.13.02-.14v-.14l.01-.05-.01-.01-.04-.03-.03-.04h-.02l.03-.04.04-.04.03-.03zm-.67-6.76.03.02.03.04.03.03.03.03-.01.02-.04.03-.03.03-.01.01v.19c.02.13.07.3.13.37l.07.08.04.04.03.02-.03.02h-.1l-.07-.02h-.03l-.04.25-.05.01-.04-.27-.03.01-.06.01h-.08l-.03.01h-.03q0-.02.02-.03l.05-.05c.05-.03.06-.05.13-.18l.04-.13q0-.13.03-.14v-.19l-.04-.04-.04-.03-.01-.02.03-.03zm1.35 0 .08.1.03.02-.01.02-.04.03-.03.03-.01.01v.19c.02.2.13.43.24.49l.03.02-.01.02h-.12l-.07-.02h-.03l-.04.26h-.05l-.04-.27h-.04l-.06.02-.07.01h-.06q0-.02.02-.03l.05-.04c.05-.04.07-.07.13-.2l.04-.12q0-.13.02-.14l.01-.13v-.06l-.04-.04-.03-.03-.02-.02.03-.03.03-.03.03-.04zm-.68 1.16.02.02.03.04.03.03.03.03-.02.02-.03.03-.03.03-.01.02v.17c.02.2.12.43.24.5l.03.03-.03.01h-.03l-.17-.03-.04.27h-.05l-.04-.27-.18.03-.05-.01.03-.03.12-.12q.08-.16.09-.22 0-.13.02-.15l.01-.13v-.07l-.04-.03-.04-.03-.01-.02.03-.03.03-.03.03-.04zm-.67 1.15.03.03.02.03.04.04.03.03-.02.01-.03.04-.05.04v.04c0 .2.06.44.13.5l.08.1.04.04.03.02-.03.02h-.04l-.07-.01-.06-.01-.04-.01-.03.27h-.06l-.03-.27h-.04l-.06.02h-.07l-.04.01-.03-.01.02-.03.06-.04c.12-.1.2-.33.2-.6v-.04l-.01-.01-.04-.03-.03-.04-.02-.01.07-.06.02-.04zm1.34 0 .03.03.02.03.04.04.03.03-.02.01-.08.08v.05l.01.14q.02.3.24.49l.03.02-.03.02h-.04l-.07-.01-.06-.01-.04-.01-.03.27h-.06l-.04-.28-.1.03h-.07l-.03.01-.02-.01.01-.03.06-.04c.04-.04.06-.05.13-.19l.04-.12q0-.13.02-.14v-.14l.01-.05-.01-.01-.03-.03-.04-.04-.02-.01.03-.03zm-2.77-.6v.06l.04.12c.04.21.08.27.19.27q.08 0 .12-.09l.02-.07q0-.03.04-.03.06 0 .06.14l.02.18.02.16-.02.12.02.23q0 .14-.05.22l.02.14v.12l-.03.13.01.05.01.04-.01.02-.07-.03-.09-.04-.08-.07c-.07.06-.1.07-.28.12l-.09.04-.04.03q-.06 0-.05-.16 0-.12.02-.2l-.13-.04h-.07q-.02 0-.02-.03l.02-.08.04-.09.09-.1.1-.06.13-.03q.12-.03.12-.11t-.11-.12l-.16-.05-.15-.07q-.1-.07-.12-.06-.05 0-.05.06 0 .11.1.12l.04-.01.04-.01q.02 0 .02.03v.07q-.02.08-.12.23l-.04.04a.5.5 0 0 1-.2.3l-.04.02-.03.06-.07.08-.1.09-.07.07-.03.06-.03.02q-.06 0-.09-.1-.01-.06-.05-.05l-.06.01h-.19l-.24.06q-.02 0-.03-.03v-.03c0-.06.04-.2.1-.3l.1-.11q-.01-.1-.1-.13l-.06-.01-.01-.02q0-.03.08-.08l.2-.06q.1 0 .2.08c.1.08.12.1.17.1.08 0 .15-.08.15-.15q.01-.08-.1-.2c-.1-.13-.13-.2-.13-.3q0-.1.04-.18l.04-.05.01-.04q0-.04-.06-.04l-.26.1q-.08.04-.08.08l.02.03.04.02v.05l-.08.1-.16.15-.04.04-.03.06-.16.16-.05.04-.03.06-.14.19-.1.1q-.04.05-.1.23-.05.12-.07.13l-.03-.02q-.1-.12-.17-.13l-.04.02-.1.03-.14.03q-.13.02-.2.11l-.03.03q-.02 0-.02-.05v-.03l.02-.1q.03-.16.07-.24l.07-.12.02-.06c0-.08-.1-.16-.2-.17q-.04 0-.04-.03t.07-.08q.13-.1.24-.1.06 0 .16.05l.08.03.09.02q.12 0 .27-.26a.4.4 0 0 0 .07-.19q0-.15-.12-.15a.2.2 0 0 0-.16.07q-.06.06-.06.12v.04q0 .06-.03.06c-.03 0-.08-.05-.23-.23-.1-.13-.13-.18-.14-.32-.12-.16-.15-.22-.15-.34v-.07q-.12-.14-.11-.26 0-.05.03-.1l-.08-.14-.01-.08-.06-.14-.04-.07q-.02-.05.16-.1v-.17l.03-.13.02-.12-.03-.12-.04-.08-.02-.05q0-.02.03-.02.06 0 .23.14c.22.17.26.24.29.46v.07q.16.12.16.26 0 .13-.07.24l-.07.12-.04.12q0 .1.07.22.08.14.17.14c.1 0 .18-.17.18-.36v-.22l.02-.1v-.15q0-.03-.03-.07l-.08-.1q-.19-.19-.19-.33.01-.18.2-.2l.07.02v-.03q0-.26.08-.28h.02l.06.06.09.05.02.03c0-.05 0-.05.05-.1q0-.02.05-.08l.04-.05.01-.04q.02-.03.03-.02.01-.01.04.05-.01.02.07.09l.05.05.03.07v.03l.08-.07.06-.03.04-.02.02.02.03.06q.06.1.05.13v.08q.17.05.17.24 0 .15-.15.31c-.06.08-.07.1-.07.15q.02.42.53.43h.25c.16.01.25.03.4.07.18.06.23.08.28.08l.05-.02.02-.03c0-.05-.1-.1-.4-.18q-.88-.23-.86-.83c0-.3.26-.55.6-.55.1 0 .27.03.37.06l.15.06.08.01q.08 0 .08-.13-.01-.06.04-.06.06.01.17.14.1.14.1.24 0 .12-.13.2-.12.18-.32.18-.15 0-.51-.2-.13-.07-.18-.07-.1 0-.11.1 0 .08.15.12c.16.06.2.08.26.15a1 1 0 0 1 .4.15c.32.1.52.33.52.58s-.17.43-.4.43l-.18-.02m6.92-.01.02.06.02.12c.05.21.1.27.2.27q.08 0 .12-.09l.02-.07q0-.03.03-.03.07 0 .07.14l.02.18.02.17q0 .05-.03.1l.01.05.02.14c0 .16-.01.2-.05.27l.02.13-.01.13-.02.11v.07l.02.04-.01.02-.08-.03-.08-.04-.08-.07a.3.3 0 0 1-.17.1l-.24.09q-.05-.01-.05-.14 0-.17.02-.23l-.13-.03h-.07q-.02 0-.02-.03l.06-.17q.08-.13.18-.16l.14-.03q.11-.02.12-.11t-.11-.12l-.16-.05-.23-.12-.04-.01q-.05 0-.05.06 0 .1.1.12l.04-.01.04-.01q.02 0 .02.04c0 .06-.04.18-.08.23l-.04.06-.04.04a.5.5 0 0 1-.2.3l-.04.02-.03.06-.07.08-.1.09-.07.07-.04.06q0 .02-.03.02-.05 0-.08-.1-.01-.06-.05-.05l-.07.01h-.18l-.24.06q-.03 0-.03-.06c0-.12.09-.3.2-.41q-.02-.1-.1-.13l-.06-.01-.01-.02q0-.04.08-.08.13-.07.2-.06.08 0 .2.08c.1.08.12.1.17.1.08 0 .15-.08.15-.15q0-.08-.1-.2c-.1-.13-.13-.2-.13-.32 0-.07.02-.1.08-.21l.01-.04q0-.03-.07-.04l-.15.04q-.17.09-.18.13 0 .02.02.03l.04.03v.02l-.01.03-.08.1-.15.15-.04.04-.03.06-.16.16-.05.04-.03.06-.14.19-.1.1-.1.23q-.06.14-.07.13l-.03-.02q-.12-.12-.17-.13l-.04.02-.1.03-.13.03c-.12.02-.16.04-.21.11l-.03.03q-.03 0-.02-.05v-.03l.02-.1q.03-.16.07-.24l.07-.12.02-.06q-.01-.13-.2-.17-.04 0-.04-.03t.07-.08q.13-.1.23-.1l.17.04.08.04.08.02q.13 0 .28-.26a.4.4 0 0 0 .06-.19q0-.15-.11-.15a.2.2 0 0 0-.16.07q-.06.06-.06.12v.06q0 .04-.03.04-.04 0-.12-.1l-.1-.13c-.12-.13-.14-.18-.15-.32q-.18-.22-.16-.34v-.07c-.08-.11-.1-.16-.1-.26q0-.06.02-.1l-.07-.15-.02-.07-.05-.14-.04-.07q0-.05.13-.09h.03l-.01-.09.01-.08.03-.14.01-.12-.02-.12-.04-.08-.02-.05q0-.02.03-.03l.04.02q.2.11.36.28c.08.1.1.17.13.38q.16.12.15.28 0 .1-.07.22l-.08.12-.03.12q0 .1.07.22.08.15.17.14c.1 0 .18-.17.18-.35v-.14l.01-.09v-.1l.01-.1v-.04c0-.04 0-.05-.11-.17q-.2-.2-.19-.36t.2-.18l.07.01v-.12l.02-.1q.02-.1.06-.08h.01l.07.06.08.05.03.03q-.01-.06.04-.1l.06-.08.03-.05.02-.04.04-.03.02.06q0 .02.04.05l.05.04q.05.05.08.15l.07-.07.06-.03.04-.02.02.02.03.06c.04.08.05.09.05.14v.07q.17.05.16.23 0 .14-.14.32c-.06.08-.07.1-.07.16q.02.4.53.42h.24c.16.01.26.03.4.07.18.06.24.08.29.08q.06-.01.07-.05c0-.06-.1-.1-.4-.18q-.88-.24-.86-.82c0-.32.26-.56.6-.56.1 0 .27.03.36.06l.16.06.07.01q.08.01.08-.13 0-.06.05-.06.07.01.17.14t.1.25-.13.19q-.13.18-.33.18-.16 0-.5-.2-.14-.07-.18-.07-.11 0-.12.1-.01.07.16.12c.17.07.2.09.26.15.19.03.27.06.39.15q.52.18.52.59c0 .24-.16.42-.4.42zm-6.85 7q.06.12.05.18v.15q.02.24.16.24.06 0 .09-.03l.04-.04h.01q.04 0 .04.04v.06l.01.18.01.14c0 .08 0 .11-.03.18l.04.23q0 .11-.04.18v.27l-.01.17v.01q0 .04-.03.04l-.04-.03q-.03-.04-.05-.04c-.03 0-.04.01-.08.12l-.09.14-.06.1-.02.09-.03.01q-.1 0-.2-.37-.03-.1-.09-.1l-.06.04-.03.05-.01.01q-.06 0-.1-.12l-.04-.17c0-.11.08-.2.34-.35q.16-.08.16-.29 0-.16-.14-.25-.11-.09-.16-.08t-.06.05.06.07q.09.03.09.07l-.07.13a.3.3 0 0 1-.12.13q0 .13-.18.24l-.07.13-.08.1-.05.12q-.01.07-.04.07-.05-.01-.15-.13a.2.2 0 0 1-.05-.13q-.03.04-.12.05l-.1.02-.09.04q-.02 0-.02-.03v-.09c0-.1.04-.24.1-.32a.4.4 0 0 0-.17-.1l-.03-.01q0-.03.03-.07l.07-.08a.4.4 0 0 1 .22-.08q.06 0 .2.06l.1.02q.06 0 .06-.08a1 1 0 0 0-.1-.34l-.08-.24c0-.13.06-.27.13-.3l-.08-.03-.11.04q-.09.05-.09.08l.03.03q.04.02.04.06-.01.15-.19.29a.3.3 0 0 1-.2.26.4.4 0 0 1-.08.17c-.1.14-.12.18-.13.26q-.01.06-.04.06l-.08-.07-.06-.07-.04-.12-.05.01h-.09a.4.4 0 0 0-.22.05h-.03q-.03 0-.04-.1a.6.6 0 0 1 .12-.37l-.07-.06-.03-.03-.04-.02-.02-.03q0-.04.12-.11a.3.3 0 0 1 .18-.07q.07 0 .17.08.07.07.11.07t.05-.03l.02-.06c0-.07-.08-.19-.18-.25a.4.4 0 0 0-.22-.07q-.16 0-.23.13l-.04.09q0 .03-.03.03c-.03 0-.04-.01-.12-.11l-.1-.11-.06-.1-.02-.04-.04-.04q-.11-.08-.16-.3v-.05a.6.6 0 0 1-.15-.37v-.05c-.05-.05-.05-.07-.1-.2l-.08-.2-.01-.03q0-.03.08-.04l.08-.01h.07v-.1l.01-.17.01-.08v-.06l-.02-.09.02-.01.05.01.16.1c.13.1.23.25.23.35v.03l-.01.05.02.06.04.06q.06.08.06.14c0 .04 0 .05-.06.14a.3.3 0 0 0-.07.17q0 .1.08.23.07.12.14.12.12 0 .13-.27 0-.16.03-.28v-.06l-.03-.07-.11-.13c-.1-.12-.14-.18-.14-.27q.01-.17.16-.18h.05v-.02l.02-.1q.03-.13.07-.14l.03.02.07.02.07.04q.02-.09.06-.13.08-.1.12-.11.02 0 .06.04l.07.08q.02 0 .04.07l.02.03.04-.03.06-.03.07-.03.04-.02q.01-.02.05.14l.02.17q.18.02.18.2t-.19.38q-.04.05-.04.1c0 .32.11.42.52.47.26.02.33.04.63.13q.24.07.31.07.1 0 .11-.07c0-.07-.05-.1-.34-.16-.69-.14-.96-.38-.96-.83 0-.32.24-.56.57-.56a1 1 0 0 1 .47.16c.18.1.22.12.26.12q.07 0 .07-.11 0-.08.05-.08t.12.08c.06.07.08.11.08.21q0 .2-.2.26l-.04.04q-.1.11-.27.11a1 1 0 0 1-.32-.1l-.18-.13q-.12-.08-.19-.08-.12 0-.12.12 0 .13.13.16l.17.06.15.06h.09q.16 0 .31.07l.07.03.1.03c.2.06.37.3.37.52q-.02.42-.44.43zm6.45-.05q.12.13.23.14l.1-.02h.05q.03 0 .03.02l-.02.07-.02.07-.02.07-.04.07-.05.05-.01.01v.05q0 .14-.1.2l-.03.01v.03l-.04.13-.07.1-.1.16q-.01.05-.05.05-.05-.01-.08-.1l-.01.02-.05.03-.07.05-.06.04-.04.04-.02.01q-.03 0-.06-.09l-.03-.12-.02-.12q0-.07.03-.13-.1 0-.14.02l-.03.01q-.02 0-.02-.02t.02-.06l.05-.12a.3.3 0 0 1 .25-.19l.1.02.05.01q.07 0 .08-.07 0-.03-.03-.05l-.14-.04q-.07-.02-.16-.12-.07-.09-.09-.08t-.02.03v.07q0 .14-.1.34l-.1.19-.07.22q0 .13.07.15l.05.02.02.01.02.02-.02.04-.07.08c-.07.09-.1.12-.18.14q-.06.15-.25.21l-.02.03c-.04.08-.14.15-.2.15h-.01q-.02.11-.13.19l-.09.06-.02.03q-.02.06-.05.06-.06 0-.1-.11l-.03.02-.07.05-.13.04q-.15.04-.19.09l-.03.05-.02.01q-.03 0-.05-.06l-.03-.2c0-.14.05-.22.18-.36v-.03q.02-.32.38-.34h.18a.3.3 0 0 0 .2-.08q.13-.1.12-.2l-.04-.15-.03-.17c0-.16.12-.35.27-.45q.07-.05.07-.09l-.01-.01-.05.03-.09.05-.06.03-.07.03q-.03 0-.03.03l.01.04v.07l-.06.08q-.07.12-.15.15-.05.18-.2.2-.07.2-.25.2l-.11.17-.05.06-.04.06q-.04 0-.09-.06l-.03-.04-.03-.06-.04-.03h-.02l-.08.01a.3.3 0 0 0-.15.09l-.05.06-.02.01q-.05 0-.05-.19 0-.15.05-.23l.1-.14.03-.06-.02-.05q-.02-.03-.06-.04l-.08-.01-.01-.01v-.03l.1-.08q.14-.08.21-.08.1 0 .2.06l.1.07.06.02q.07 0 .12-.1l.05-.17q-.02-.23-.24-.24a.3.3 0 0 0-.2.08l-.03.04-.03.06q0 .03-.03.03t-.1-.12a1 1 0 0 1-.08-.32l.01-.1a.4.4 0 0 1-.04-.36.3.3 0 0 1-.04-.17v-.04l.01-.06.01-.04c-.04-.05-.04-.08-.08-.24l-.06-.18q.01-.04.11-.04h.05l-.01-.07q0-.07.03-.15l.02-.09q0-.07-.02-.11l-.03-.08v-.03l.01-.01c.07 0 .21.07.32.18s.15.18.15.34l-.01.08q.15.12.15.24 0 .08-.08.15c-.1.1-.12.15-.12.28q0 .3.16.3.16-.01.19-.26v-.14l.03-.13v-.1q0-.06-.12-.22-.14-.16-.14-.28.01-.19.18-.2l.08.02c0-.07 0-.08.04-.17l.07-.12.02.01.05.04.04.03.03.04a.4.4 0 0 1 .12-.2l.08-.06.02.02.05.06.06.07q.03.02.05.11l.03-.02.06-.03.05-.03.02-.01.02.02.02.09.05.1q.02.02.02.09v.02h.02q.12.02.14.19c0 .13-.1.3-.24.39l-.02.1c0 .3.08.36.53.42a3 3 0 0 1 .6.16q.14.05.22.05t.08-.04c0-.05-.07-.1-.3-.19l-.32-.12q-.49-.19-.48-.63c0-.34.25-.6.6-.6q.18 0 .43.1c.24.08.25.08.28.08q.06 0 .07-.1 0-.07.05-.07.08 0 .14.11.04.1.04.2 0 .19-.18.22a.4.4 0 0 1-.3.15c-.14 0-.22-.03-.47-.18q-.12-.08-.2-.07-.13 0-.15.13 0 .09.18.14c.07.02.08.02.12.06h.06q.2 0 .4.17c.23.07.43.31.43.52 0 .23-.2.43-.42.43z' style='fill:%23211e1e;fill-opacity:1;fill-rule:nonzero;stroke:none;stroke-width:.35277778' transform='translate(71.69 -111.2)'/%3E%3Cpath d='m-67.44 115.63-.01-.1v-.08l.01-.05q0-.08-.02-.1l-.05-.07-.03-.07-.01-.03q0-.03.02-.03l.05.03h.04q.03 0 .03-.1 0-.09-.02-.12l-.06-.06-.04-.04-.02-.04q0-.02.03-.02l.08.02h.02q.02 0 .02-.03v-.02l-.01-.07-.03-.09q0-.03-.02-.03h-.01l-.1.02h-.01c-.12 0-.25-.1-.3-.23l-.07-.24q-.02-.1-.17-.22-.05-.04-.08-.04l-.06-.01q-.02 0-.02-.02t.04-.02h.13l.2.06.24.05q.3-.01.3-.26a.5.5 0 0 0-.15-.33q-.08-.08-.12-.08-.02 0-.02.02v.04q0 .04-.02.04t-.07-.07q-.11-.23-.3-.24l-.03.02.02.06.03.06.01.04h-.01q-.03 0-.07-.03l-.05-.06-.05-.07a.3.3 0 0 0-.15-.13l-.1-.05-.04-.02q-.02 0-.02.03l.02.04.03.07-.01.02q-.06-.01-.15-.14a.4.4 0 0 1-.06-.2q.02-.26.27-.28.13 0 .28.1l.17.1q.1.06.2.06l.12-.01.04-.02.02-.02-.01-.02h-.02l-.09-.02-.1-.04q-.15-.06-.18-.1l-.12-.06q-.05-.01-.05-.04l.01-.01.04.01q.08.05.14.05l.16.06.25.05q.1 0 .12-.12 0-.08-.07-.16 0-.02-.02-.02t-.02.03v.07q0 .08-.07.09l-.06-.02-.24-.07c-.2-.07-.3-.09-.4-.09-.28 0-.5.2-.5.46 0 .3.2.49.72.66.5.17.57.22.57.35q-.01.12-.16.14l-.09-.01-.25-.06q-.22-.05-.46-.05c-.36 0-.57.06-.74.23q-.05.06-.1.05h-.09q-.07 0-.1.06l-.07.1-.04.03q-.05 0-.1-.12l-.07-.11-.07-.07q-.02 0-.02-.03l.01-.03.05-.1q0-.06.03-.05.03-.01.04.1 0 .05.03.11l.04.09q0 .02.03.02c.04 0 .09-.1.1-.19q.01-.11.04-.1h.01l.03.07.05.06.05.02q.04 0 .05-.09v-.12l.01-.04.03.02.04.03q.03.04.07.04t.05-.03-.03-.09l-.03-.05q-.04-.07-.08-.07h-.04l-.04.02h-.04q0-.06.06-.16a1 1 0 0 0 .06-.3q.02-.29.06-.31.03 0 .03.06v.08l.01.07q.05 0 .1-.13l.02-.07v-.02l-.08-.14-.07-.02-.03-.02v-.13l-.02-.04-.02-.04a.4.4 0 0 0-.14.11q-.05.05-.07.05l-.01-.01v-.07l.01-.02a.3.3 0 0 0-.13-.2l-.02.02-.03.04-.04.05-.05.12v.02l-.01.04h-.01l-.03-.04-.04-.05-.06-.04-.03-.02-.02.03-.02.06v.13q0 .05-.03.05l-.05-.02-.05-.02q-.1 0-.1.1 0 .12.07.2l.04.06.04.03.01-.08-.01-.07v-.02q0-.04.02-.04t.05.08l.03.14.03.17q0 .07.04.15l.06.13.05.07q0 .02-.02.02l-.03-.01-.04-.01h-.03c-.06 0-.07.04-.07.29 0 .15.03.36.07.45l.07.2q.03.04.02.1c0 .26-.36.69-.75.88-.15.08-.2.15-.2.3v.05l.12-.05q.13-.02.15-.1l.01-.04q-.01-.02.1-.07l.06-.05.05-.05v.03l-.03.1v.03q0 .12.12.18l.05-.15.06-.1a.3.3 0 0 0 .04-.16l-.01-.12v-.03q0-.03.02-.03l.03.01.01.07q0 .03.04.03.05 0 .13-.13l.03-.1v-.05l-.02-.06q0-.05.03-.05h.02l.02.1q.01.03.05.04.04 0 .1-.09l.02-.15q0-.11.04-.1h.02l.01.05.03.03q.04 0 .09-.09v-.03q0-.03-.03-.05c-.03-.04-.04-.04-.04-.09q0-.06.04-.13l.05-.09q.07-.12.08-.11.03 0 .03.03v.03l-.02.04q0 .03.03.03l.06-.02.1-.04.13-.05h.14l.08.01q.06 0 .07-.06l-.06-.11-.02-.03v-.02l.02-.01q.05.01.14.14c.32.5.43.63.65.7.21.06.27.1.27.24q0 .1-.11.26c-.17.23-.2.32-.2.47v.03l.04-.02.06-.03.09-.02q.05-.01.05-.07v-.01l-.01-.08v-.02l.03-.07.02-.01q.02 0 .03.02l.06.13q.02.06.13.1m-2.99-2.68q-.04 0-.04.08l-.01.07v.09q0 .08.03.09.04-.01.08-.1l.01-.09-.01-.08q-.03-.06-.06-.06' style='fill:%23fddc02;fill-opacity:1;fill-rule:nonzero;stroke:none;stroke-width:.35277778' transform='translate(71.69 -111.2)'/%3E%3Cpath d='M-70.77 112.36v.04l-.05.24-.01.06.03.09.03.04.05.02v.05l.02.08.01.11v.05q-.03 0-.07-.1-.05-.13-.12-.12-.05 0-.11.03l.02.03.03.06.06.1.06.12.05.05.06.03.03.04q0 .03-.03.03h-.05l-.03-.01q-.02 0-.02.04 0 .15.22.32.03.01.03.04l-.03.02-.05-.01-.02-.01q-.03 0-.03.04l.06.16q.05.09.13.12l.17.07.01.03q0 .02-.02.02h-.03l-.03.01h-.05l-.04.01.05.12q.07.1.1.1l.02-.01.04-.09.1-.07.1-.04.07-.01q.03 0 .03-.04l-.01-.08-.01-.08-.01-.07v-.08q0-.03-.03-.03l-.03.03q-.08.13-.16.12c-.2 0-.35-.35-.35-.81l.01-.15.01-.2q0-.3-.12-.42l-.06-.05zm.47 2.71-.1-.02-.07-.03-.14-.04q-.08 0-.16.06l.04.03.07.05.07.06.06.02q.1.01.24-.13m1.43.68.07-.1q.15-.13.15-.2v-.09q0-.07.03-.06l.03.01.02.04q0 .02.03.02l.05-.04.04-.05.02-.08v-.04l-.03-.06-.01-.06q0-.03.03-.03h.03l.02.04.03.02q.03 0 .04-.03l.03-.06.01-.04-.03-.03-.05-.02q-.1-.06-.11-.24v-.04l.03-.06.01-.06-.03-.12-.05-.08q-.02-.08-.05-.07h-.02l-.03.02-.04.02-.05.06-.05.03c-.03.01-.06.08-.06.13 0 .1.01.13.14.34q.08.13.08.22 0 .23-.41.32l-.17.04q-.19.05-.23.27c.05-.03.07-.04.16-.04h.06c.06 0 .06 0 .1-.04a.3.3 0 0 1 .12-.1l.06-.03.04-.03h.02l.02.01q0 .03-.04.07a.2.2 0 0 0-.05.14q-.01.05.04.1' style='fill:%23fddc02;fill-opacity:1;fill-rule:nonzero;stroke:none;stroke-width:.35277778' transform='translate(71.69 -111.2)'/%3E%3Cpath d='m-69.33 115.17.11.1c.04.05.04.06.08.06l.05-.01.03-.01q.09-.01.09-.04l-.02-.03-.05-.03-.04-.04a.2.2 0 0 0-.12-.04q-.05-.01-.13.04m1.2.2h.1q.15-.02.17-.14 0-.04-.07-.04-.14 0-.2.18m7.61.26-.01-.07v-.05l.01-.14q0-.04-.03-.08l-.04-.06q-.04-.06-.04-.1 0-.03.02-.03h.02l.03.03h.04q.03 0 .03-.1 0-.14-.07-.18l-.06-.04-.01-.03q0-.03.03-.03h.04l.04.02h.02l.02-.03v-.02l-.02-.07q0-.12-.05-.12l-.1.02h-.02a.3.3 0 0 1-.28-.23l-.07-.24a.5.5 0 0 0-.18-.22l-.08-.04-.07-.01-.02-.02q0-.03.04-.02.14 0 .33.06.18.06.25.05.3-.01.3-.25l-.07-.25-.18-.16-.03-.01-.02.02v.04q0 .04-.02.04t-.06-.07q-.11-.23-.3-.23-.03 0-.03.02t.02.05l.04.1h-.02l-.06-.03-.05-.06-.05-.07a.4.4 0 0 0-.15-.13l-.1-.05-.04-.02-.02.02.02.05.03.07q0 .02-.02.02t-.13-.14a.4.4 0 0 1-.07-.2q.02-.26.27-.28.13 0 .28.1l.18.1q.1.06.2.06l.1-.01.05-.02.01-.02q0-.03-.03-.03a1 1 0 0 1-.36-.14l-.13-.07q-.05-.02-.05-.04l.02-.01h.02l.16.06.16.06c.07.03.2.05.25.05q.1 0 .11-.12l-.02-.1-.06-.08q-.03 0-.03.04v.02l.01.04q0 .08-.07.09l-.06-.02-.24-.07a1 1 0 0 0-.4-.09c-.29 0-.5.2-.5.46 0 .3.2.48.72.66.5.18.57.22.57.35q-.01.13-.16.14l-.09-.01-.25-.06a2 2 0 0 0-.46-.05c-.37 0-.55.05-.74.23q-.05.05-.11.05h-.08q-.07 0-.1.06l-.07.1q0 .03-.04.03-.05 0-.1-.12l-.07-.11-.08-.07-.02-.03.02-.03.04-.05.01-.05v-.03l.03-.02q.04-.01.03.1l.03.11.04.09.04.02c.04 0 .08-.1.1-.19q0-.11.03-.1.02-.02.06.07 0 .03.04.06l.05.02q.04 0 .05-.09v-.08l-.01-.04q0-.04.02-.04l.03.02.04.03q.04.04.07.04.05 0 .05-.04l-.04-.08-.02-.05q-.04-.08-.08-.07h-.04l-.04.02h-.03l-.02-.01q0-.05.07-.15a1 1 0 0 0 .06-.3l.02-.17q.01-.15.04-.14h.02l.01.06v.05l.01.1q.03 0 .06-.05l.04-.08.02-.1q0-.11-.15-.15l-.03-.01v-.14l-.02-.04-.02-.04-.03.02-.12.09q-.04.06-.06.05l-.02-.01.02-.07q0-.14-.13-.23l-.02.03-.03.04-.04.05-.04.11v.03q0 .04-.02.04h-.01l-.03-.04-.04-.05-.06-.04-.04-.02c-.03.07-.03.08-.03.18v.03q0 .06-.03.06l-.05-.02-.05-.02q-.1.01-.1.11t.06.19.09.09v-.18q0-.03.02-.03t.05.08l.02.14.03.17.05.15.06.13.05.07q0 .02-.02.02l-.03-.01-.05-.02h-.02c-.06 0-.08.05-.08.3 0 .15.03.35.07.45l.08.2.02.1c0 .26-.37.7-.75.88-.15.07-.2.15-.21.35l.13-.05q.13-.03.15-.1l.01-.04q0-.02.1-.07l.06-.05.04-.05q.02 0 .02.02l-.04.11v.03q0 .12.12.18v-.04l.04-.11.07-.1c.03-.04.04-.07.04-.17l-.01-.11v-.03q0-.03.02-.03l.03.01v.07q.02.03.05.03.05 0 .13-.13l.02-.1v-.1l-.01-.03q0-.03.03-.03h.02l.02.1q.02.03.05.04c.06 0 .12-.11.12-.24q0-.11.04-.1h.02l.01.05q0 .03.03.03l.05-.04.03-.05.01-.04q0-.02-.03-.05l-.04-.07q0-.08.09-.23l.08-.12q.03 0 .03.04v.03l-.02.04q0 .03.02.03t.07-.02l.1-.04.2-.06h.07l.08.02q.06 0 .06-.06l-.02-.06-.03-.05-.03-.04v-.01l.03-.02q.06 0 .14.15c.29.47.43.62.64.69.23.07.28.11.28.25q0 .1-.12.26-.21.28-.2.46v.03l.04-.02.06-.02.1-.02q.04-.01.05-.08l-.01-.09q0-.1.05-.1l.03.03.06.13q.02.06.13.1m-3.04-2.53v.09q0 .09.02.09.06-.01.08-.1l.02-.1-.02-.07q-.02-.06-.05-.06-.05 0-.05.15' style='fill:%23fddc02;fill-opacity:1;fill-rule:nonzero;stroke:none;stroke-width:.35277778' transform='translate(71.69 -111.2)'/%3E%3Cpath d='M-63.85 112.36v.04l-.03.15-.02.09v.06q0 .09.06.13l.04.02v.05l.01.08.02.11v.05q-.04 0-.07-.1-.05-.13-.12-.12-.05 0-.11.03c.03.05.06.09.1.2.06.12.08.15.18.2q.03 0 .03.03t-.03.03h-.05l-.03-.01q-.03 0-.02.04 0 .16.22.32l.03.03-.01.02-.02.01-.04-.02h-.03q-.03 0-.03.04 0 .06.07.16.06.09.12.12l.17.07.01.03-.02.02h-.11q-.04 0-.04.02l.06.12q.06.1.09.1l.02-.01.04-.09.1-.07.1-.04q.12-.01.1-.05l-.01-.08-.01-.08-.01-.07-.01-.08q0-.03-.02-.03l-.03.03q-.07.11-.16.12c-.2 0-.35-.33-.35-.82v-.14l.02-.18v-.06q0-.24-.13-.38l-.05-.05zm.48 2.71-.18-.05-.14-.04q-.08 0-.16.06l.03.03.08.05.07.06.06.02q.1.01.24-.13m1.42.68a.2.2 0 0 1 .08-.1q.15-.13.15-.2v-.09q0-.07.03-.06l.03.01.01.04.04.02q.02.01.09-.1.03-.03.02-.07v-.04l-.03-.06-.02-.06q0-.03.04-.03h.02l.03.04.02.02q.03 0 .05-.03l.03-.06.01-.04-.03-.03-.05-.02q-.1-.06-.11-.23v-.05l.03-.06.01-.07-.03-.1-.05-.09q-.03-.07-.05-.07t-.05.02l-.04.02-.05.06-.05.03q-.05.03-.06.13c0 .08.02.13.14.34q.07.14.07.22-.01.23-.4.32c-.3.06-.37.11-.4.3.05-.02.07-.03.16-.03h.06q.06.01.1-.04l.11-.1.06-.03.05-.03h.02l.02.01q0 .03-.04.07l-.05.12q0 .06.03.12' style='fill:%23fddc02;fill-opacity:1;fill-rule:nonzero;stroke:none;stroke-width:.35277778' transform='translate(71.69 -111.2)'/%3E%3Cpath d='m-62.41 115.17.1.1q.05.07.08.06l.06-.01.03-.01q.08-.01.08-.04l-.01-.03-.05-.03-.04-.04-.11-.04zm1.2.2h.11q.04 0 .07-.02l.07-.08.02-.04q0-.04-.07-.04-.14 0-.2.18m-6.59 7.83.02-.04.05-.05a.3.3 0 0 0 .07-.2l-.02-.11-.01-.07q0-.04.03-.05l.03.02.06.07q.03.04.08.05v-.05l.01-.06a.4.4 0 0 0-.08-.25l-.04-.08q0-.02.02-.02h.01l.07.04q.02 0 .03-.1a.4.4 0 0 0-.07-.2l-.05-.05v-.03q0-.02.03-.02l.04.02h.03q.04.01.04-.14v-.12q-.01-.1-.05-.09h-.03c-.18 0-.27-.11-.31-.42q-.07-.34-.22-.42-.08-.02-.08-.05l.03-.02.07.02q.23.1.38.1c.18 0 .32-.14.32-.3a.5.5 0 0 0-.17-.37l-.1-.05h-.02l.01.06.02.04v.01l-.02.01h-.02l-.07-.11a.4.4 0 0 0-.26-.15q-.05 0-.05.04l.03.04.03.06v.02l-.02.01c-.02 0-.03 0-.1-.1-.07-.07-.21-.15-.28-.15l-.03.02q0 .03.02.05l.04.06-.02.01q-.03 0-.16-.1-.2-.14-.2-.33c0-.14.1-.26.24-.26q.12 0 .24.1l.19.13q.12.1.29.1l.06-.02q.03 0 .03-.02l-.04-.02-.15-.06-.19-.14-.14-.1-.12-.08.02-.01h.03l.1.05.16.09c.2.13.3.18.41.18q.18-.01.2-.19l-.02-.06-.02-.04-.02-.02-.01.02-.01.07-.01.03-.03.04q-.03.02-.07.02c-.06 0-.12-.03-.3-.14a1 1 0 0 0-.45-.17.5.5 0 0 0-.49.48c0 .37.23.54.94.7q.4.08.4.25-.02.17-.24.18h-.1l-.38-.1a2 2 0 0 0-.5-.08q-.4 0-.59.26-.02.04-.04.04l-.03-.02-.05-.04-.13-.05-.08.03-.04.03q-.04-.01-.09-.1l-.06-.26q0-.06.03-.06l.02.03.03.1q.03.1.08.11.02 0 .05-.04l.03-.05q.03-.1.05-.08.03-.01.05.08l.02.06.04.07.04.02q.06-.02.07-.12v-.08l.01-.04.03.02.06.06.05.01.04-.01.01-.04-.05-.06-.07-.15q-.02-.05-.04-.05l-.02.01-.05.02-.03.01h-.02q-.02 0-.03-.02l.08-.09a.1.1 0 0 0 .05-.1q0-.1.02-.11l.01-.13.08-.28.01.06v.06q0 .07.02.07t.05-.07l.04-.08.01-.07q0-.11-.1-.12h-.05q-.03 0-.04-.04v-.13l-.02-.07v-.04l-.03.02-.04.03-.06.05-.05.04-.03.01q-.04.02-.03-.07v-.01q.01-.05-.1-.17l-.01-.02-.02.02-.04.07-.04.1v.07l-.03.03-.03-.02a.3.3 0 0 0-.16-.11v.03l-.03.07v.13q0 .03-.02.03l-.03-.02-.04-.01q-.11 0-.12.1c0 .04.02.07.09.18q.05.07.08.08l.01-.05v-.05l-.01-.06.01-.03q.06.02.09.23l.01.14q0 .07.04.15.06.1.1.13.06.04.06.07l-.02.02-.08-.03h-.03q-.1-.01-.1.17c0 .15.1.38.22.47l.17.14c.1.06.16.18.16.26q0 .17-.33.3l-.12.04c-.1.03-.13.1-.17.27l.1-.02h.08q.07 0 .08-.07v-.03l.03-.04.06-.02.04-.03.02-.01.02.02v.03l-.03.13c0 .1.02.14.06.2l.01-.04.06-.1q.1-.13.1-.23v-.01l-.01-.09.02-.04h.02q.03 0 .04.03l.03.03q.03 0 .05-.07l.02-.08v-.05l-.02-.04.01-.03h.05l.03.03h.03q.02 0 .05-.03l.05-.1q0-.03-.02-.04-.12-.09-.13-.2l.01-.05.04-.1.03-.08h.01q.02 0 .02.02v.05l-.02.07q0 .03.04.04l.06-.02q.17-.06.25-.07.07 0 .14.05l.03.01.02-.01.01-.02-.02-.05-.03-.05.02-.02q.1.02.24.48c.07.23.09.25.3.37q.28.14.26.38 0 .25-.14.66l-.04.2.03.18.03.08z' style='fill:%23fddc02;fill-opacity:1;fill-rule:nonzero;stroke:none;stroke-width:.35277778' transform='translate(71.69 -111.2)'/%3E%3Cpath d='m-68.66 122.69.07-.13q.09-.13.08-.18v-.06q0-.08.03-.08l.02.01.02.03.03.02.04-.04q.04-.07.04-.13v-.08q0-.03.03-.03l.03.03q0 .03.03.03l.03-.02.03-.05.02-.03v-.02l-.02-.03q-.1-.07-.1-.27l-.03-.2-.06-.16-.05-.13q0-.06-.04-.05-.16.02-.18.2 0 .1.08.3c.07.18.09.25.09.31 0 .14-.05.2-.24.26q-.31.1-.35.39l.04-.02.05-.02.06-.01q.08-.02.1-.07l.01-.05q0-.03.03-.03l.03-.01.03-.02v.06l-.01.09q0 .11.06.19m-1.99-3.43v.14l-.02.07q0 .1.04.2l.02.08v.02l-.01.02-.04-.02a.2.2 0 0 0-.14-.06l-.06.01.02.04.05.14.08.12.08.05.02.03.01.02-.01.01h-.07q-.02 0-.02.02t.03.11l.03.11.07.06.06.05.03.04v.02h-.05l-.01.03q0 .05.07.15.08.11.16.1h.06q.04 0 .04.04l-.03.03q-.07.01-.07.04t.02.04l.03.04q.03.06.07.06l.05-.03.12-.08q.18-.05.16-.08l-.02-.04a.3.3 0 0 1-.05-.18q0-.08-.03-.08l-.03.03a.2.2 0 0 1-.13.08c-.13 0-.28-.2-.36-.47l-.03-.2.03-.23.04-.18v-.05q0-.16-.21-.3' style='fill:%23fddc02;fill-opacity:1;fill-rule:nonzero;stroke:none;stroke-width:.35277778' transform='translate(71.69 -111.2)'/%3E%3Cpath d='m-70.38 119.77-.06.24q0 .08.04.08l.02-.02.04-.07.02-.05.03-.05q0-.07-.1-.13m.41 1.67.02.02.03.03c.07.08.08.09.12.09l.14-.04.02-.03-.03-.04-.04-.04-.1-.05q-.06 0-.16.07m.86.67.08.03.06.04h.1l.08-.03.07-.02.04-.03-.04-.02-.06-.02c-.1-.04-.1-.04-.14-.04a.3.3 0 0 0-.19.09m.94.74c.03-.06.04-.07.13-.07.1 0 .18-.18.18-.3v-.01h-.03l-.06.04-.1.05a.3.3 0 0 0-.14.2zm6.76-.88.01-.04.02-.06.04-.06a.3.3 0 0 0 .06-.18l-.02-.08-.01-.03v-.02h.02v-.01l.04.03.04.03q.02 0 .04-.07v-.04l-.03-.1v-.04l.01-.03q.03 0 .05.04l.03.01q.03 0 .06-.08l.01-.06v-.02h-.07a.3.3 0 0 1-.2-.1l-.1-.12-.1-.12-.08-.05-.03-.04.04-.02.19.07c.1.04.27.08.37.08.18 0 .33-.14.33-.32q0-.13-.15-.3l-.07-.05-.02.02.01.05.01.03q0 .03-.02.03t-.07-.1q-.02-.12-.18-.2l-.12-.04-.01.02.02.04.02.07q0 .03-.02.03c-.02 0-.03 0-.08-.1a.4.4 0 0 0-.17-.12l-.06-.01-.03.01.02.04v.02l-.01.02c-.02 0-.1-.06-.15-.12a.4.4 0 0 1-.1-.22c0-.14.14-.27.3-.27l.09.02.13.06.15.1q.15.1.28.1l.12-.02q.05 0 .06-.04h-.02l-.08-.01-.23-.1-.17-.12-.15-.06-.02-.02.02-.01h.04l.14.04.17.08a1 1 0 0 0 .33.12q.14-.01.15-.14l-.02-.1-.02-.05-.02-.02-.01.03v.05q0 .1-.1.1a1 1 0 0 1-.34-.1q-.24-.11-.4-.1c-.27 0-.52.22-.52.48q0 .34.46.52l.31.14q.38.14.36.28-.01.13-.2.14l-.24-.06c-.3-.09-.49-.13-.66-.13q-.4 0-.63.24-.03.03-.05.03l-.05-.02-.08-.03q-.05.01-.09.05l-.04.05-.03.02q-.05 0-.1-.1l-.04-.1v-.24l.02-.06.01-.02q.03 0 .03.06v.04c0 .1.04.2.09.2q.06 0 .1-.19l.02-.04q.03 0 .04.07t.05.12l.04.03q.05 0 .07-.15 0-.07.03-.07l.02.01.02.04.04.04.05.01.03-.01.03-.03-.02-.03-.07-.13-.03-.08-.02-.03h-.04l-.07.02h-.03l-.02-.01.03-.04q.15-.12.18-.38 0-.15.07-.22l.02-.02q.03 0 .03.03t-.02.05v.08l.04-.01.05-.05q.04-.06.05-.16 0-.05-.03-.08-.04-.04-.06-.04h-.05q-.03 0-.04-.02l.01-.03v-.04l-.02-.09-.02-.05v-.03l-.03.02-.06.03-.04.04q-.07.08-.08.07-.02 0-.02-.02v-.01l.01-.08a.4.4 0 0 0-.1-.22q-.12.12-.12.24v.04q0 .03-.02.03t-.03-.02l-.04-.06-.06-.05-.03-.02-.02.03-.05.17-.01.07h-.03q-.06-.05-.08-.04-.11 0-.12.12l.05.12q.07.1.1.11t.02-.02v-.07l-.02-.05q0-.03.02-.02.04 0 .09.29.03.26.14.36l.03.04-.01.01-.05-.02h-.04q-.07 0-.09.08l-.03.21-.03.3q0 .08.03.22l.02.18q-.02.35-.36.46l-.24.07q-.22.06-.24.32.04-.04.1-.04l.07-.01.07-.02.04-.04.06-.07.06-.04.02.02-.03.06-.03.1q0 .05.06.14l.02-.04q0-.03.05-.08.1-.11.1-.17l.01-.07q.02 0 .02.03l.01.02.03.02.03-.02.06-.05.03-.07.02-.07v-.04l.01-.03.04.04.03.02.03-.01q.08-.08.08-.14v-.07l-.02-.06.01-.02q.03 0 .07.08 0 .03.03.03t.07-.06l.03-.05.01-.03-.01-.04-.03-.05v-.03q0-.07.05-.18l.05-.1.02-.01.01.02v.1q0 .02.03.02l.04-.01.09-.04.08-.04c.15-.08.2-.1.27-.1q.06 0 .17.06l.04.01q.02 0 .03-.02l.01-.03-.01-.04-.02-.06.01-.01q.02 0 .03.02l.09.14q.12.2.23.23l.17.04q.07 0 .06.1 0 .16-.15.27l-.13.08q-.09.06-.1.2l.04.18.02-.03.06-.03.06-.06.03-.08.03-.07q.02-.06.04-.06t.02.05v.03c0 .05 0 .07.05.15' style='fill:%23fddc02;fill-opacity:1;fill-rule:nonzero;stroke:none;stroke-width:.35277778' transform='translate(71.69 -111.2)'/%3E%3Cpath d='M-63.61 123.1c.04-.04.05-.05.18-.07q.15-.02.17-.17 0-.09.09-.12l.05-.04.02-.02v.02l-.01.06-.02.07q0 .08.04.15.03-.06.1-.1.1-.07.11-.25 0-.09.03-.08h.02l.03.06.02.02.05-.03.05-.05q.04-.03.04-.16 0-.05.03-.05l.02.02.02.08.03.02.03-.01.05-.06.02-.07v-.07l.02-.04.02-.01.02.02.01.04q0 .02.04.03.02 0 .06-.06l.03-.03.02-.05-.01-.03a.4.4 0 0 1-.08-.25c0-.12.04-.23.19-.42q.13-.17.13-.3 0-.03-.03-.03l-.05.02h-.05l-.02-.04-.02-.03-.03-.01h-.06q-.06 0-.06.06v.04q0 .05-.06.12l-.07.06q-.15.14-.16.28l.03.16.05.2q0 .28-.78.67c-.25.13-.32.2-.32.38zm-.25-3.89v.15l-.02.09c0 .07.01.1.05.18q.04.06.04.12l-.01.02h-.02l-.03-.05q-.04-.04-.1-.04h-.07l.04.13c.03.13.04.13.1.2q.09.06.07.08 0 .03-.02.03h-.04q-.04 0-.04.08l.05.13.04.04.01.04q0 .03-.02.03l-.03-.01h-.03q-.02 0-.02.02v.06l.02.1q.01.03.05.06.02.04.05.05l.09.06q0 .03-.03.03h-.04l-.03-.01q-.05 0-.04.03v.06l.02.05q.01.1.06.1l.02-.01.23-.08.22.03v-.05l.02-.06.01-.12.01-.08v-.05l-.03.02q-.08.09-.17.08-.26-.01-.26-.52a4 4 0 0 1 .07-.66q0-.19-.22-.33' style='fill:%23fddc02;fill-opacity:1;fill-rule:nonzero;stroke:none;stroke-width:.35277778' transform='translate(71.69 -111.2)'/%3E%3Cpath d='m-63.6 120.04.03-.03.03-.03a.2.2 0 0 0 .05-.12l-.01-.05q-.02-.05-.05-.05-.02 0-.03.08v.05l-.02.06zm-.33 1.52q.04 0 .09.06.06.09.14.08l.06-.01.04-.01.04-.02q.03 0 .03-.02l-.07-.06-.1-.05-.08-.02q-.07 0-.15.05m.5 1.08.17-.08.1-.06q.1-.05.1-.08t-.1-.04c-.15 0-.27.1-.27.22zm1.51-.94.1-.02h.06l.05-.03.05-.04q.1-.06.08-.07 0-.03-.1-.03-.16 0-.24.2' style='fill:%23fddc02;fill-opacity:1;fill-rule:nonzero;stroke:none;stroke-width:.35277778' transform='translate(71.69 -111.2)'/%3E%3Cpath d='m-69.52 112.77-.02-.05v-.04q0-.04.05-.06.1-.03.13-.06l.04-.04q.02 0 .02.03-.01.07-.1.22l-.07.1q-.03 0-.04-.06zm-.22-.15.06.03q.03.01.03.04v.1q-.03.09-.08.07l-.04-.04-.08-.1-.05-.16v-.01q0-.03.02-.03l.04.02zm.22.38.06-.03h.04q.06 0 .05.06c0 .07-.04.1-.12.28q-.03.12-.09.13-.08 0-.13-.15l-.05-.12-.05-.16q0-.05.06-.05l.05.02.04.02zm6.93-.22-.03-.06v-.04q-.01-.04.05-.06l.13-.06.04-.04q.02 0 .02.02 0 .08-.1.22l-.07.12q-.03 0-.05-.07zm-.23-.16.06.03q.03.02.03.05v.01l-.02.07-.01.07-.02.02-.08-.05-.06-.1-.05-.1-.01-.06v-.01q0-.03.02-.03l.04.02zm.22.38.06-.03h.02q.08 0 .09.08l-.07.1-.04.17q-.05.12-.12.12-.08 0-.14-.15l-.04-.12-.05-.15q0-.06.05-.06l.06.02.04.02zm-7.23 6.55-.02-.06v-.01l.01-.02.05.03.05.02q.14.02.12.09v.06l-.02.06q0 .03-.02.03l-.08-.06-.04-.05zm.45.09-.05.09-.02.02q-.03-.01-.04-.1l-.01-.07q0-.04.07-.05l.07-.02.06-.04.02.01-.02.07zm-.1.26.06-.04h.03q.05 0 .05.06-.01.06-.08.18-.08.13-.12.14-.1 0-.2-.22l-.03-.1q0-.08.06-.08l.04.01.03.03q.04.03.1.03zm6.44-.45.05.04.08.04q.07.03.07.05v.04l-.01.06q-.02.07-.06.06-.03 0-.1-.11l-.05-.15v-.01zm.5.13-.08.09q-.05.06-.04.08l-.03.01q-.04 0-.04-.04v-.06l-.01-.06q0-.04.03-.05l.08-.02.08-.04.04-.01.01.02v.02zm-.37.26.05.04h.05l.09-.02.05-.02h.03q.04 0 .05.07 0 .06-.1.19l-.04.08q-.04.07-.08.07-.04.02-.13-.16l-.07-.2q0-.06.05-.06z' style='fill:%23211e1e;fill-opacity:1;fill-rule:nonzero;stroke:none;stroke-width:.35277778' transform='translate(71.69 -111.2)'/%3E%3Cpath d='M-69.6 113.11h-.05l-.02.01v.02l.02.09.01.08q0 .06.06.06t.06-.07v-.08l.01-.09v-.02l-.03-.01zm6.92 0h-.05l-.01.01-.01.02.01.09.02.08q0 .06.05.06t.07-.07v-.19l-.02-.01zm-6.88 6.87h-.05q-.03 0-.04.03 0 .07.07.16l.03.02q.03 0 .05-.12l.01-.06q0-.04-.02-.04h-.01zm6.69.05v.07q.02.05.06.06.06 0 .07-.13l.01-.05q.01-.04-.04-.03h-.06q-.04 0-.04.06z' style='fill:%23fddc02;fill-opacity:1;fill-rule:nonzero;stroke:none;stroke-width:.35277778' transform='translate(71.69 -111.2)'/%3E%3Cpath d='M-67.04 116.44h.4q.05-.14.2-.14.11 0 .2.14h.32a.2.2 0 0 1 .2-.14q.16.01.21.14h.3q.06-.14.2-.14.12 0 .2.11v.03h.42v1.92h-.36v.74h-.43v-.74h-1.07v.74h-.43v-.75h-.36z' style='fill:%23211e1e;fill-opacity:1;fill-rule:nonzero;stroke:none;stroke-width:.35277778' transform='translate(71.69 -111.2)'/%3E%3Cpath d='M-66.89 118.21h2.36v-1.62h-2.36zm0 0' style='fill:%23ee2e4f;fill-opacity:1;fill-rule:nonzero;stroke:none;stroke-width:.35277778' transform='translate(71.69 -111.2)'/%3E%3Cpath d='M-66.64 116.96a.11.11 0 0 0 0 .23q.1-.01.11-.11a.1.1 0 0 0-.11-.12' style='fill:%23fddc02;fill-opacity:1;fill-rule:nonzero;stroke:none;stroke-width:.35277778' transform='translate(71.69 -111.2)'/%3E%3Cpath d='M-66.64 116.96a.11.11 0 0 0 0 .23q.1-.01.11-.11a.1.1 0 0 0-.11-.12zm0 0' style='fill:none;stroke:%23211e1e;stroke-width:.03033889;stroke-linecap:butt;stroke-linejoin:miter;stroke-miterlimit:4;stroke-opacity:1' transform='translate(71.69 -111.2)'/%3E%3Cpath d='M-64.79 116.96a.11.11 0 0 0 0 .23q.1-.01.11-.11a.1.1 0 0 0-.11-.12' style='fill:%23fddc02;fill-opacity:1;fill-rule:nonzero;stroke:none;stroke-width:.35277778' transform='translate(71.69 -111.2)'/%3E%3Cpath d='M-64.79 116.96a.11.11 0 0 0 0 .23q.1-.01.11-.11a.1.1 0 0 0-.11-.12zm0 0' style='fill:none;stroke:%23211e1e;stroke-width:.03033889;stroke-linecap:butt;stroke-linejoin:miter;stroke-miterlimit:4;stroke-opacity:1' transform='translate(71.69 -111.2)'/%3E%3Cpath d='M-66.64 117.84a.1.1 0 0 0-.11.11q.01.11.11.12t.11-.12a.1.1 0 0 0-.11-.1' style='fill:%23fddc02;fill-opacity:1;fill-rule:nonzero;stroke:none;stroke-width:.35277778' transform='translate(71.69 -111.2)'/%3E%3Cpath d='M-66.64 117.84a.1.1 0 0 0-.11.11q.01.11.11.12t.11-.12a.1.1 0 0 0-.11-.1zm0 0' style='fill:none;stroke:%23211e1e;stroke-width:.03033889;stroke-linecap:butt;stroke-linejoin:miter;stroke-miterlimit:4;stroke-opacity:1' transform='translate(71.69 -111.2)'/%3E%3Cpath d='M-64.79 117.84a.11.11 0 0 0 0 .23.11.11 0 0 0 0-.23' style='fill:%23fddc02;fill-opacity:1;fill-rule:nonzero;stroke:none;stroke-width:.35277778' transform='translate(71.69 -111.2)'/%3E%3Cpath d='M-64.79 117.84a.11.11 0 0 0 0 .23.11.11 0 0 0 0-.23zm0 0' style='fill:none;stroke:%23211e1e;stroke-width:.03033889;stroke-linecap:butt;stroke-linejoin:miter;stroke-miterlimit:4;stroke-opacity:1' transform='translate(71.69 -111.2)'/%3E%3Cpath d='M-66.29 117.5a.7.7 0 0 0 .58.29c.22 0 .37-.08.55-.29a.7.7 0 0 0-.56-.26q-.35.01-.57.26' style='fill:%23fddc02;fill-opacity:1;fill-rule:nonzero;stroke:none;stroke-width:.35277778' transform='translate(71.69 -111.2)'/%3E%3Cpath d='M-66.18 117.5a.7.7 0 0 1 .46-.17q.22 0 .44.18a.6.6 0 0 1-.45.19.6.6 0 0 1-.45-.2' style='fill:%23211e1e;fill-opacity:1;fill-rule:nonzero;stroke:none;stroke-width:.35277778' transform='translate(71.69 -111.2)'/%3E%3Cpath d='M-65.99 117.47q.14.08.26.08.15 0 .27-.08l-.27-.07q-.14 0-.26.07' style='fill:%23fddc02;fill-opacity:1;fill-rule:nonzero;stroke:none;stroke-width:.35277778' transform='translate(71.69 -111.2)'/%3E%3Cpath d='M-66.92 116.76h2.43v-.08h-2.43zm0 0' style='fill:%23211e1e;fill-opacity:1;fill-rule:nonzero;stroke:%23211e1e;stroke-width:.01023056;stroke-linecap:butt;stroke-linejoin:miter;stroke-miterlimit:4;stroke-opacity:1' transform='translate(71.69 -111.2)'/%3E%3Cpath d='M-66.55 116.57v.23q.01.1.1.1t.1-.1v-.23q0-.13-.09-.14l-.04.01-.03.02-.02.03-.02.04zm.73.19v.04q.01.1.1.1t.1-.1v-.23q0-.13-.09-.14-.1.01-.1.14zm.71-.19v.23q0 .1.1.1t.1-.1v-.23q0-.13-.1-.14l-.04.01-.02.02-.03.03-.01.04zm-1.49 2.24h.22v-.28h-.22zm0 .15h.22v-.09h-.22zm1.5-.15h.22v-.28h-.22zm0 .15h.22v-.09h-.22zm0 0' style='fill:%23fddc02;fill-opacity:1;fill-rule:nonzero;stroke:none;stroke-width:.35277778' transform='translate(71.69 -111.2)'/%3E%3Cpath d='M-52.98 111.63v.17h-.12c-.16 0-.44 0-.44.52v2.12q.01 1.94-1.72 1.92c-1.31 0-1.92-.52-1.92-1.64v-2.4c0-.52-.28-.52-.53-.52h-.05v-.17h1.96v.17h-.05c-.25 0-.55 0-.55.52v2.3q0 1.46 1.26 1.46 1.25-.01 1.26-1.5v-2.26c0-.52-.28-.52-.49-.52h-.1v-.17zm2.11 4.47v.16h-1.65v-.17h.07c.54 0 .6-.4.6-.88v-2.78c0-.44-.25-.63-.61-.63h-.06v-.17h1.3l2.81 3.45v-2.62c0-.6-.41-.66-.59-.66h-.12v-.17h1.67v.17h-.07c-.3 0-.6.07-.6.88v3.6h-.25l-3.19-3.85v2.78c0 .47.07.88.63.88zm8.87-.82 1.02-2.84c.18-.49.06-.64-.36-.64h-.08v-.17h1.31v.17h-.03c-.14 0-.3.05-.43.36l-1.54 4.12h-.3l-1.67-4.08c-.14-.34-.3-.4-.57-.4h-.04v-.17h1.91v.17h-.12c-.33 0-.4.2-.3.46zm7.72-3.43v2.05h.4c.72 0 1.04-.32 1.04-1.07 0-.61-.4-1-.99-1-.14 0-.33 0-.45.02m.72-.22q1.53 0 1.53 1.16c0 .66-.51.99-.92 1.15l-.03.02 1.14 1.72c.18.28.32.4.64.41v.17h-1.19l-1.37-2.17h-.52v1.44c0 .52.24.56.56.56h.1v.17h-2.02v-.17h.1c.22 0 .48-.1.48-.38v-3.37c0-.54-.32-.54-.49-.54h-.09v-.17z' style='fill:%23211e1e;fill-opacity:1;fill-rule:nonzero;stroke:none;stroke-width:.35277778' transform='translate(71.69 -111.2)'/%3E%3Cg clip-path='url(%23e)' style='clip-rule:nonzero' transform='translate(-14.97 -16.86)scale(.35278)'%3E%3Cpath d='M164.15 59.68c0-1.6-1.37-2.23-2.65-2.9-1.5-.77-3.22-1.58-3.22-4 0-2.35 1.78-3.86 4.33-3.86 1.05 0 2.23.2 2.75.31l.18 2.56-.5.07c-.22-1.35-.92-2.38-2.43-2.38-1.42 0-2.47.87-2.47 2.44 0 1.48 1.36 2.09 2.64 2.73 1.56.78 3.34 1.6 3.34 4.04 0 2.7-2.4 3.92-4.64 3.92-.89 0-2.12-.18-3.1-.74l-.32-2.84.48-.08c.36 1.88 1.56 2.97 3.14 2.97 1.5 0 2.47-.92 2.47-2.24' style='fill:%23211e1e;fill-opacity:1;fill-rule:nonzero;stroke:none'/%3E%3C/g%3E%3Cpath d='M-25.45 111.63v.17h-.07c-.26 0-.5.05-.5.41v3.47c0 .36.24.41.5.41h.07v.17h-1.94v-.17h.07c.26 0 .5-.05.5-.4v-3.48c0-.36-.24-.4-.5-.4h-.07v-.18zm-19.51 0v.17h-.07c-.26 0-.5.05-.5.41v3.47c0 .36.24.41.5.41h.07v.17h-1.93v-.17h.06c.26 0 .5-.05.5-.4v-3.48c0-.36-.24-.4-.5-.4h-.06v-.18z' style='fill:%23211e1e;fill-opacity:1;fill-rule:nonzero;stroke:none;stroke-width:.35277778' transform='translate(71.69 -111.2)'/%3E%3Cg clip-path='url(%23f)' style='clip-rule:nonzero' transform='translate(-14.97 -16.86)scale(.35278)'%3E%3Cpath d='m227.43 68 .05 3.48-.56.14c-.13-1.52-.47-2.76-2.9-2.76h-3.28v6.44h2.81c1.38 0 1.75-.77 1.91-2.1h.56v5.38h-.56c-.08-1.28-.39-2.28-1.9-2.28h-2.82v5.65c0 1.65 1.42 1.65 2.92 1.65 2.68 0 3.93-.17 4.68-2.9l.55.13-.75 3.63h-12.21v-.6h.23c.93 0 1.8-.18 1.8-1.46V70.05c0-1.27-.87-1.45-1.8-1.45h-.23V68z' style='fill:%23211e1e;fill-opacity:1;fill-rule:nonzero;stroke:none'/%3E%3C/g%3E%3Cpath d='M-30.81 118.6v2.56h.5c.9 0 1.3-.4 1.3-1.34 0-.77-.5-1.26-1.24-1.26-.17 0-.4 0-.56.03m.9-.28q1.91-.01 1.91 1.45c0 .82-.64 1.24-1.15 1.45l-.04.01 1.43 2.17c.23.35.41.49.8.5v.23h-1.48l-1.73-2.73h-.64v1.8c0 .66.29.71.7.71h.12v.22h-2.53v-.22h.12c.28 0 .6-.13.6-.48v-4.23c0-.67-.39-.67-.6-.67h-.12v-.21zm5.73.01v.21h-.08c-.33 0-.64.06-.64.51v4.36c0 .45.31.51.64.51h.08v.21h-2.42v-.2h.08c.33 0 .64-.07.64-.52v-4.36c0-.45-.3-.51-.64-.51h-.08v-.21z' style='fill:%23211e1e;fill-opacity:1;fill-rule:nonzero;stroke:none;stroke-width:.35277778' transform='translate(71.69 -111.2)'/%3E%3Cg clip-path='url(%23g)' style='clip-rule:nonzero' transform='translate(-14.97 -16.86)scale(.35278)'%3E%3Cpath d='M176.36 49.05h8.68c.44 0 1-.11 1.09-.68h.42l-.34 3.42h-.46c-.03-.79-.15-1.94-1.41-1.94h-2.65v10.13c0 1.58.76 1.71 1.6 1.71h.28v.48h-5.98v-.48h.28c1 0 1.6-.08 1.6-1.67V49.85h-2.68c-1.36 0-1.5.6-1.75 1.92h-.48l.3-3.38h.39c.18.55.65.66 1.1.66' style='fill:%23211e1e;fill-opacity:1;fill-rule:nonzero;stroke:none'/%3E%3C/g%3E%3Cpath d='M-16.12 111.63v.18c-.26.01-.43.2-.55.36l-1.17 1.81v1.48c0 .6.21.63.57.63h.1v.17h-2.12v-.17h.1c.37 0 .57-.09.57-.57v-1.43l-1.28-1.82c-.2-.28-.34-.47-.65-.47h-.04v-.17h1.91v.17h-.06c-.36 0-.39.2-.23.42l.99 1.53.87-1.38c.2-.3.26-.57-.24-.57h-.07v-.17z' style='fill:%23211e1e;fill-opacity:1;fill-rule:nonzero;stroke:none;stroke-width:.35277778' transform='translate(71.69 -111.2)'/%3E%3Cg clip-path='url(%23h)' style='clip-rule:nonzero' transform='translate(-14.97 -16.86)scale(.35278)'%3E%3Cpath d='M206.39 55.04c0 3.24 1.43 6.73 4.57 6.73 2.88 0 4.28-2 4.28-6.1 0-3.02-1.61-6.22-4.6-6.22-3.95 0-4.25 4.28-4.25 5.59m-2.44.66a6.76 6.76 0 0 1 6.73-6.93c4.12 0 7 2.66 7 6.48 0 4.17-2.9 7.2-6.9 7.2a6.57 6.57 0 0 1-6.83-6.75' style='fill:%23211e1e;fill-opacity:1;fill-rule:nonzero;stroke:none'/%3E%3C/g%3E%3Cg clip-path='url(%23i)' style='clip-rule:nonzero' transform='translate(-14.97 -16.86)scale(.35278)'%3E%3Cpath d='M219.17 62.17v-.48h.19c.75 0 1.43-.14 1.43-1.16V50.7c0-1.02-.68-1.16-1.43-1.16h-.2v-.48h9.18l.03 2.77c-.07.03-.33.09-.44.12-.1-1.13-.36-2.2-1.93-2.2h-3v5.13h2.64c1.08 0 1.24-.86 1.25-1.54h.43v4.2h-.43c-.01-.82-.2-1.86-1.55-1.86h-2.33v4.86c0 1.16.98 1.16 1.85 1.16h.16v.48z' style='fill:%23211e1e;fill-opacity:1;fill-rule:nonzero;stroke:none'/%3E%3C/g%3E%3Cpath d='M-57.4 121.22c0-.87.36-1.71.96-2.25.56-.5 1.3-.79 2.12-.79.74 0 1.36.14 1.97.42l.06 1.34-.2.03c-.21-.78-.57-1.5-1.8-1.5-1.27 0-2.05 1-2.05 2.62 0 1.43.63 2.79 2.17 2.79a2.3 2.3 0 0 0 1.95-.92l.15.28a2.8 2.8 0 0 1-2.26 1.04c-1.87 0-3.06-1.1-3.06-3.06m12.52-1.78-.2 3.59c-.03.8.22.86.75.88h.05v.21h-1.96v-.2h.08c.65-.03.7-.4.73-.94l.22-3.67c.03-.5-.24-.78-.7-.78h-.07v-.21h1.64l1.98 4.4 1.86-4.4h1.61v.2h-.03c-.65 0-.77.21-.72 1.03l.23 3.85c.03.45.27.5.71.51v.21h-2.4v-.21c.4-.02.68-.04.68-.43v-.42l-.18-3.71-2 4.82h-.18zm23.31-.84v4.55c0 .62.26.72.89.72 1.46 0 2.13-1.26 2.13-2.5 0-1.93-.8-2.8-2.43-2.8zm-1.7 5.52v-.2h.08c.33 0 .64-.07.64-.52v-4.36c0-.45-.3-.51-.64-.51h-.08v-.21h2.6c.96 0 1.77.24 2.33.76q.84.8.85 2.13c0 .81-.32 1.6-.89 2.16a3 3 0 0 1-2.17.75zm10.72-.3v-1.42q0-.46-.65-.47h-.07v-.21h2.23v.2h-.06q-.48 0-.48.48v1.6c-.54.17-1.25.3-2.04.3-1.92 0-3.16-1.24-3.16-3.16 0-2.05 1.63-2.98 3.17-2.98.69 0 1.4.14 1.85.29l.09 1.39h-.2c-.24-1-.68-1.38-1.68-1.38-1.35 0-2.17 1-2.17 2.6 0 1.46.7 2.92 2.23 2.92.36 0 .73-.05.94-.15m-22.43-2.87c.73.06 1.12.22 1.45.55q.38.4.39.97c0 .91-.84 1.64-1.93 1.64h-2.84v-.2h.11c.29 0 .62-.14.62-.5v-4.22c0-.67-.4-.67-.62-.67h-.11v-.21h2.58c1.2 0 1.87.44 1.87 1.27 0 .92-.8 1.26-1.52 1.37m-1.19-2.43v2.33h.44q1.22 0 1.24-1.13 0-1.21-1.15-1.2zm0 2.59v2.04c0 .57.18.73.77.73.7 0 1.24-.58 1.24-1.37 0-.9-.54-1.4-1.45-1.4zm-13.44-1.62.81 2.26h-1.62zm.1-1.18-1.84 5q-.2.57-.74.58h-.02v.22h1.77v-.22h-.08c-.42 0-.71-.13-.53-.68l.43-1.17h1.82l.46 1.28q.19.59-.48.58h-.05v.22h2.25v-.22h-.02q-.44.02-.64-.56l-1.9-5.03zm12.94-6.69.01.98-.15.04c-.04-.43-.13-.77-.82-.77h-.92v1.8h.8c.38 0 .48-.21.53-.58h.15v1.5l-.15.01c-.03-.36-.11-.64-.54-.64h-.79v1.59c0 .46.4.46.82.46.76 0 1.1-.05 1.32-.81l.15.03-.2 1.02h-3.44v-.17h.06c.26 0 .5-.05.5-.4v-3.48c0-.36-.24-.4-.5-.4h-.06v-.18z' style='fill:%23211e1e;fill-opacity:1;fill-rule:nonzero;stroke:none;stroke-width:.35277778' transform='translate(71.69 -111.2)'/%3E%3C/svg%3E "University of Cambridge")


' transform='matrix(1.6734 0 0 -1.6734 -355.35 840.72)'%3E%3Cpath d='M0 0c-.18-.87-.69-2.33-1.02-3.07-.67-1.35-2.5-3.06-4.45-3.06-2.38 0-3.3 1.17-3.3 2.4 0 .9.49 1.58 1.38 1.58.95 0 1.1-.79 1.1-1.07 0-.3-.1-.74-.23-.87q-.15-.14-.15-.43c0-.52.59-.8 1.13-.8 1.32 0 2.04 1.08 2.5 2.84.3 1.2.77 3.22 1.71 6.75l-.15.05c-.36-.49-1.82-2.56-5.27-2.56-3.52 0-5.93 2.48-5.93 6.9 0 3.3 1.51 6.09 3.4 8a9.7 9.7 0 0 0 7.21 3c2.66 0 4.01-.88 4.52-1.28.34-.26.56-.31.7-.31.3 0 .45.25.6.82q.04.17.24.12l.38-.1c.1-.02.18-.07.15-.2l-1.45-5.14c-.05-.15-.1-.18-.28-.15l-.41.05q-.2.03-.18.25c.43 2.2-.82 4.89-4.14 4.89-1.64 0-3.48-.57-5.27-2.92-1.48-1.86-2.32-4.62-2.32-7.72 0-4.19 2.58-4.85 3.7-4.85a4.7 4.7 0 0 1 4.66 4.14c.07.97-.21 1.17-.9 1.17h-.9c-.2 0-.22.08-.17.26l.1.56c.02.16.08.2.28.2.38 0 1.28-.07 3.53-.07 1.74 0 2.35.08 2.7.08q.28-.01.24-.2l-.08-.62q-.02-.22-.23-.2h-.54c-.48 0-.84-.21-1.17-1.57z' style='fill:%230e2b58;fill-opacity:1;fill-rule:nonzero;stroke:none' transform='translate(225.66 482.4)'/%3E%3Cpath d='M0 0c.05-.05.1-.1.05-.28l-1.33-3.73c-.1-.41-.25-.46-.56-.46l-2.7.05c-1.47.02-3.3.02-5.07.02h-3.32l-2.12-.02-1.13-.05q-.2-.01-.15.2l.1.67q.04.15.18.15h.82c1.02 0 1.53.51 1.79 1.36l3.9 12.13c.44 1.38-.48 1.74-1.25 1.74h-.81q-.2.01-.16.26l.16.56c.05.15.1.2.3.2l1.49-.02a59 59 0 0 1 2.2-.05h1.83q2.75 0 4.27.02l1.92.05c.4 0 .46-.1.56-.5l.77-3.43c.05-.18.05-.18-.1-.28l-.31-.16c-.1-.05-.16 0-.3.16l-2.61 3.01q-.24.22-.47.2h-3.98l-2.15-6.6h2.2c1.1 0 2.1.13 3.01 2.12.06.1.1.15.21.15l.46-.15c.1 0 .15-.1.1-.15-.4-.98-1.22-4.15-1.33-5.12-.05-.15-.1-.15-.2-.15h-.46c-.15.05-.15.1-.15.26 0 1.84-.98 2.12-2.82 2.12h-1.27l-2.5-7.75h5.72c.87 0 1.58.39 2.25.98.56.46 1.94 2.2 2.35 2.65.05.1.15.16.3.06z' style='fill:%230e2b58;fill-opacity:1;fill-rule:nonzero;stroke:none' transform='translate(245.64 488.95)'/%3E%3Cpath d='M0 0c-2.1-2.35-3.63-6.13-3.63-8.94 0-3.17 1.69-4.66 3.78-4.66 3.74 0 7.06 5.73 7.1 11.25 0 2.55-1.27 4.24-3.57 4.24A4.9 4.9 0 0 1 0 0m10.02-4.34c0-5.12-3.63-10.43-9.4-10.43a6.5 6.5 0 0 0-4.6 1.69c-1.6 1.53-2.26 3.57-2.26 5.87 0 5.32 3.89 10.33 9.3 10.33 4.1 0 6.96-2.76 6.96-7.46' style='fill:%230e2b58;fill-opacity:1;fill-rule:nonzero;stroke:none' transform='translate(255.12 498.94)'/%3E%3Cpath d='M0 0c1.02 0 2.35-.1 4.09.61 1.33.57 2.5 2 2.5 3.84 0 1.07-.76 2.73-3.27 2.73-.46 0-.76 0-1.07-.05zm-2-6.36c-.43-1.38-.15-1.84.57-1.84h1.07c.15 0 .2-.1.15-.2l-.05-.62q-.08-.21-.3-.2c-.3 0-1.43.07-3.63.07-1.79 0-2.76-.08-3.07-.08q-.23.01-.15.26l.1.56c0 .15.05.2.26.2h.66c.61 0 1.07.57 1.28 1.2l4.09 12.76c.25.82.1 1.28-.77 1.28h-.87q-.29-.01-.2.2l.1.54c.05.15.1.2.36.2 2.66 0 5.31.08 6.03.08 2.2 0 6.03-.18 6.03-3.7 0-2.51-2.7-4.55-6.03-4.91v-.1c.82-.2 1.23-.98 1.48-1.49.15-.25 1.9-3.88 2.33-4.57.69-1.07 1.3-1.48 2.22-1.48h.67q.22-.01.15-.26l-.05-.51c-.05-.15-.1-.26-.26-.26-.25 0-.66.08-2.04.08-1.49 0-1.95-.08-2.35-.08-.26 0-.36.26-.72.85-.36.61-2.6 5.62-2.91 6.23C1.53-.74.4-.89-.28-.89z' style='fill:%230e2b58;fill-opacity:1;fill-rule:nonzero;stroke:none' transform='translate(272.27 493.7)'/%3E%3Cpath d='M0 0c.2 1.02-.2 1.23-.92 1.23h-.84c-.2 0-.26.13-.23.28l.1.53q.03.22.25.2c.41 0 1.28-.07 3.38-.07 2.04 0 2.66.08 3.01.08q.24 0 .2-.3l-.04-.52q-.03-.21-.26-.2h-.4c-.62 0-1.08-.2-1.23-.87l-.87-3.91c-.08-.3-.2-.41-.51-.56A14 14 0 0 0-3.47-5.3c-4.76 0-7.62 3.22-7.62 6.95 0 6.19 5 10.94 10.73 10.94 2.2 0 3.63-.87 4.14-1.28.3-.25.51-.3.62-.3.3 0 .46.25.71.81q.01.17.26.1l.36-.1q.15.01.15-.2L4.4 6.52c-.06-.16-.1-.2-.26-.16h-.51q-.23 0-.16.31c.31 2.2-.76 4.88-4.03 4.88-3.94 0-7.31-4.73-7.31-10.17 0-3.94 2.35-5.54 4.3-5.54a4.7 4.7 0 0 1 2.5.58c.25.16.4.51.5.92z' style='fill:%230e2b58;fill-opacity:1;fill-rule:nonzero;stroke:none' transform='translate(295.11 489.46)'/%3E%3Cpath d='M0 0c.05-.05.1-.1.05-.28l-1.33-3.73c-.1-.41-.25-.46-.56-.46l-2.7.05c-1.47.02-3.3.02-5.07.02h-3.32l-2.12-.02-1.13-.05q-.2-.01-.15.2l.1.67q.04.15.18.15h.82c1.02 0 1.53.51 1.79 1.36l3.9 12.13c.44 1.38-.48 1.74-1.25 1.74h-.81q-.2.01-.16.26l.16.56c.05.15.1.2.3.2l1.49-.02a59 59 0 0 1 2.2-.05h1.83q2.75 0 4.27.02l1.92.05c.4 0 .46-.1.56-.5l.77-3.43c.05-.18.05-.18-.1-.28l-.31-.16c-.1-.05-.16 0-.3.16l-2.61 3.01q-.24.22-.47.2h-3.98l-2.15-6.6h2.2c1.1 0 2.1.13 3.02 2.12q.06.15.2.15l.46-.15c.1 0 .15-.1.1-.15-.4-.98-1.22-4.15-1.33-5.12-.05-.15-.1-.15-.2-.15h-.46c-.15.05-.15.1-.15.26 0 1.84-.98 2.12-2.82 2.12h-1.27l-2.5-7.75h5.72c.87 0 1.58.39 2.25.98.56.46 1.94 2.2 2.35 2.65.05.1.15.16.3.06z' style='fill:%230e2b58;fill-opacity:1;fill-rule:nonzero;stroke:none' transform='translate(316.2 488.95)'/%3E%3Cpath d='M0 0c2.3 0 3.22.2 3.68.46.1.05.15.1.26.1.1 0 .2-.05.2-.2-.05-.41-.3-4.14-.25-5.16 0-.16-.06-.2-.2-.23l-.42-.08c-.15 0-.25.1-.36.4-.2.82-.66 2.41-1.02 3.08-.56.43-2.4.66-3.58.66h-.5l-4.05-13.04c-.5-1.6-.25-2.17 1.08-2.17h1.02q.2-.01.15-.25l-.1-.51q-.04-.27-.3-.26c-.36 0-1.39.08-3.79.08-2.5 0-3.86-.08-4.11-.08q-.27.01-.23.26l.05.56q.02.21.3.2h.67c1.43 0 1.92.67 2.5 2.58L-5.06-.97h-.66c-2.36 0-3.48-.13-4.07-.56-.9-.67-2.22-2.15-2.83-2.87-.1-.1-.21-.1-.31-.1l-.4.26q-.15.09-.06.25c.3.57 1.89 4.14 1.94 4.3.05.15.1.25.26.25.1 0 .2-.05.4-.2C-10.27.2-9.05 0-6.39 0z' style='fill:%230e2b58;fill-opacity:1;fill-rule:nonzero;stroke:none' transform='translate(332.42 501.68)'/%3E%3Cpath d='M0 0c-2.1-2.35-3.63-6.13-3.63-8.94 0-3.17 1.69-4.66 3.78-4.66 3.74 0 7.06 5.73 7.11 11.25 0 2.55-1.28 4.24-3.58 4.24A4.9 4.9 0 0 1 0 0m10.02-4.34c0-5.12-3.63-10.43-9.4-10.43a6.5 6.5 0 0 0-4.6 1.69c-1.6 1.53-2.25 3.57-2.25 5.87 0 5.32 3.88 10.33 9.3 10.33 4.09 0 6.95-2.76 6.95-7.46' style='fill:%230e2b58;fill-opacity:1;fill-rule:nonzero;stroke:none' transform='translate(342.84 498.94)'/%3E%3Cpath d='M0 0c-.05-.3.15-.4.4-.1.16.15 5.84 8.33 5.94 8.48.61.92.92 1.94.92 2.48 0 .51-.2.87-.67.87h-.36q-.21 0-.2.18l.1.69c.05.1.1.15.31.15.25 0 .92-.07 2.5-.07 1.49 0 2.15.07 2.46.07q.28.01.23-.2l-.08-.62c-.05-.15-.1-.2-.3-.2h-.41c-.46 0-.72-.3-.82-1.2L8.74-.1c-.05-.46.1-.51.36-.2.51.55 3.02 4.7 3.52 5.56a37 37 0 0 1 2.59 5.14c.23.67.17 1.33-.6 1.33h-.4c-.15 0-.26.05-.2.23l.1.54c0 .2.1.25.25.25.36 0 .97-.07 2.3-.07 1.54 0 2.2.07 2.56.07q.3 0 .26-.18l-.1-.63q-.07-.23-.21-.21h-.46c-.46 0-.92-.15-1.33-.69-.26-.36-4.1-6.7-4.7-7.72-.72-1.17-4.07-6.1-5.17-7.46-.33-.4-.63-.82-1.04-.82s-.51.36-.46.92L6.75 6.7c.05.3-.16.3-.36.05C6.13 6.39-.77-3.2-1.71-4.3c-.3-.36-.57-.67-.97-.67q-.51 0-.36 1.07l1.81 14.3c.1.86 0 1.32-.56 1.32h-.61c-.2 0-.26.05-.23.23l.07.59c.06.15.1.2.31.2.26 0 1.28-.07 2.97-.07 1.58 0 2.55.07 2.86.07.25 0 .3-.05.25-.23l-.1-.58c0-.1-.05-.21-.25-.21h-.41c-.82 0-1.18-.3-1.36-1.35z' style='fill:%230e2b58;fill-opacity:1;fill-rule:nonzero;stroke:none' transform='translate(358.25 489)'/%3E%3Cpath d='M0 0c0 1.38.9 2.1 1.59 2.1.66 0 1.25-.36 1.25-1.23 0-.74-.72-1.1-.85-1.66-.1-.49.28-1.05 1.72-1.05 2.45 0 4.52 1.94 5.64 3.48 1.82 2.53 3.84 8.1 3.84 10.63 0 .59-.3.76-.87.76-1.56 0-3.02.03-4.47-.43-1.05-.3-2.05-1-2.05-1.61 0-.3.18-.87.72-1.02.79-.13 1.15-.59 1.15-1.15 0-.57-.49-1.1-1.28-1.1-.9 0-1.66.97-1.66 2.2 0 1.3.56 2.68 1.76 3.55 1.84 1.3 4.4 1.1 9 1.1.48 0 .64-.18.74-.59.87-3.91 3.24-10.45 4.62-12.68.18-.3.31-.07.41.41 1.13 5.06 2.76 10 5.6 12.17a5.6 5.6 0 0 0 3.58 1.28c1.53 0 2.25-.9 2.25-1.74a1.3 1.3 0 0 0-1.26-1.28c-.53 0-.92.4-1.12.72-.13.3-.56.58-.92.58-.49 0-1-.1-1.82-.69-1.76-1.27-3.75-3.98-5.39-11.32-.4-1.86.03-2.4.28-2.83 1.3-2.23 5.04-6.96 9.49-6.96 1.3 0 2.22.57 2.42 1.4.26 1.13.6 1.64 1.1 1.64.56 0 .74-.48.74-.86 0-.34-.3-1.1-.76-1.59-.44-.49-1.8-1.92-4.73-1.92-5.19 0-8.54 4.12-10.05 6.11-2.88 3.81-5.2 9.46-6.46 14.52-.05.23-.2.25-.28-.15-.59-3.25-1.69-6.57-3-8.8C9.62-.36 7.32-3.22 3.59-3.22 1.76-3.22 0-2.09 0 0' style='fill:%230e2b58;fill-opacity:1;fill-rule:nonzero;stroke:none' transform='translate(372.49 487.11)'/%3E%3Cpath d='M0 0c-1.4-4.52-3.42-7.54-8.13-7.54-3.32 0-5.77 1.53-5.77 4.68 0 1.07.35 2.66.5 3.22l2.2 7.08c.36 1.17 0 1.58-.71 1.58h-.92c-.1 0-.2.05-.15.2l.1.62c.05.15.1.2.36.2.3 0 1.17-.07 3.52-.07 2.05 0 2.92.07 3.17.07.2 0 .26-.1.26-.3l-.1-.51c-.03-.1-.1-.2-.26-.2h-.71c-.52 0-1.16-.11-1.54-1.36l-2.1-6.85c-.15-.56-.76-2.46-.76-3.55 0-3.12 2.7-3.43 3.47-3.43 1.18 0 2.51.4 3.33 1.13C-3.07-4.01-2.2-2.63-1.38.15L.46 6.7c.49 1.7.2 2.32-.61 2.32h-.82c-.2 0-.26.1-.23.2l.08.57c.05.15.1.25.35.25.31 0 1.28-.07 2.92-.07 1.48 0 2.04.07 2.3.07s.3-.1.25-.3l-.1-.51c0-.1-.05-.2-.25-.2h-.41C3.12 9.02 2.6 8.27 2.2 7z' style='fill:%230e2b58;fill-opacity:1;fill-rule:nonzero;stroke:none' transform='translate(246.03 468.48)'/%3E%3Cpath d='M0 0c-.15.26-.36.26-.4-.05L-2.97-8.6c-.87-2.91-.77-4.11.3-4.11h.97q.28-.01.26-.26l-.1-.53c-.05-.18-.05-.23-.31-.23-.25 0-1.33.07-3.07.07-1.78 0-2.6-.07-2.91-.07q-.22 0-.18.28l.08.53c.05.1.1.2.25.2h.56c1.18 0 1.8.88 2.56 3.15L-1.43.31c.49 1.5-.05 2.22-1.13 2.22h-.97q-.29 0-.2.3l.1.47c.05.15.1.25.3.25.31 0 1.34-.07 4.35-.07.46 0 .62-.31.77-.67l5.67-11.8c.2-.31.31-.26.51.35l2.71 8.28c.67 2.07.46 2.89-.4 2.89H9.5c-.26 0-.31.05-.26.26l.05.56c.05.1.1.2.26.2.3 0 1.12-.07 2.91-.07 1.33 0 1.84.07 2.2.07.26 0 .3-.15.26-.36l-.1-.46q0-.21-.21-.2h-.67c-.61 0-1.12-.61-1.63-2.07l-4.7-13.44c-.16-.41-.36-.62-.52-.67-.25 0-.5.16-.66.51z' style='fill:%230e2b58;fill-opacity:1;fill-rule:nonzero;stroke:none' transform='translate(255.02 474.97)'/%3E%3Cpath d='M0 0c.36 1.28-.05 1.69-.71 1.69H-1.9c-.2 0-.26.05-.26.2l.16.67q0 .15.3.15c.31 0 1.69-.08 3.73-.08 2.2 0 3.28.08 3.63.08q.39 0 .31-.3l-.15-.52c0-.1-.05-.2-.26-.2H4.9c-1.08 0-1.66-.26-2.05-1.71L-.3-11.81c-.33-1.22.05-1.74 1.13-1.74h.92q.23-.01.15-.25l-.05-.51c-.05-.2-.05-.26-.3-.26-.31 0-1.49.08-4.1.08-2.14 0-3.47-.08-3.78-.08q-.21.01-.2.26l.15.56q-.01.21.2.2h.98c1.48 0 1.63.52 1.99 1.82z' style='fill:%230e2b58;fill-opacity:1;fill-rule:nonzero;stroke:none' transform='translate(272.98 475.82)'/%3E%3Cpath d='M0 0c.92 1.23 1.02 2.12.3 2.12h-.5c-.26 0-.31.1-.29.26l.13.56c0 .15.05.2.3.2.37 0 1.23-.07 2.62-.07 1.48 0 2.14.07 2.45.07.25 0 .3-.1.28-.23l-.08-.53c-.05-.16-.1-.26-.25-.26H4.4C3.53 2.12 2.22.84 1.23-.4L-9.7-14.1c-.15-.2-.46-.46-.81-.46-.41 0-.46.36-.36.97L-8.84.74c.1.77-.16 1.38-.97 1.38h-.82c-.2 0-.3.05-.26.23l.16.54c.05.2.05.25.25.25.36 0 1.43-.07 3.63-.07 1.84 0 2.91.07 3.22.07.26 0 .3-.05.26-.23l-.08-.58c-.03-.16-.08-.2-.28-.2h-.72c-.81 0-1.27-.31-1.4-1.06L-7.62-9.15c-.1-.66.2-.71.57-.25z' style='fill:%230e2b58;fill-opacity:1;fill-rule:nonzero;stroke:none' transform='translate(290.26 475.38)'/%3E%3Cpath d='M0 0c.05-.05.1-.1.05-.28l-1.33-3.73c-.1-.41-.25-.46-.56-.46l-2.7.05c-1.47.02-3.3.02-5.07.02h-3.32l-2.12-.02-1.13-.05q-.19-.01-.15.2l.1.67q.04.15.18.15h.82c1.02 0 1.53.51 1.79 1.35l3.9 12.14c.44 1.38-.48 1.74-1.24 1.74h-.82q-.2.01-.16.26l.16.56c.05.15.1.2.3.2l1.49-.02a59 59 0 0 1 2.2-.05h1.83q2.75 0 4.27.02l1.92.05c.4 0 .46-.1.56-.5l.77-3.43c.05-.18.05-.18-.1-.28l-.31-.16c-.1-.05-.16 0-.3.16l-2.61 3.01q-.24.22-.47.2h-3.98l-2.15-6.6h2.2c1.1 0 2.1.12 3.01 2.12.06.1.1.15.21.15l.46-.15c.1 0 .15-.1.1-.15-.4-.98-1.22-4.15-1.33-5.12-.05-.15-.1-.15-.2-.15h-.46c-.15.05-.15.1-.15.26 0 1.84-.98 2.12-2.82 2.12h-1.27l-2.5-7.75h5.72c.86 0 1.58.39 2.24.98C-2.4-2.04-1.02-.3-.6.15c.05.1.15.16.3.05z' style='fill:%230e2b58;fill-opacity:1;fill-rule:nonzero;stroke:none' transform='translate(307.61 465.72)'/%3E%3Cpath d='M0 0c1.02 0 2.35-.1 4.09.61 1.33.57 2.5 2 2.5 3.84 0 1.07-.76 2.73-3.27 2.73-.46 0-.76 0-1.07-.05zm-2-6.36c-.43-1.38-.15-1.84.57-1.84h1.07c.15 0 .2-.1.15-.2l-.05-.62q-.08-.21-.3-.2c-.3 0-1.43.07-3.63.07-1.79 0-2.76-.08-3.07-.08q-.23.01-.15.26l.1.56c0 .15.05.2.26.2h.66c.61 0 1.07.57 1.28 1.2l4.09 12.76c.25.82.1 1.28-.77 1.28h-.87q-.29-.01-.2.2l.1.54c.05.15.1.2.36.2 2.66 0 5.31.08 6.03.08 2.2 0 6.03-.18 6.03-3.7 0-2.5-2.7-4.55-6.03-4.91v-.1c.82-.2 1.23-.98 1.48-1.49.15-.25 1.9-3.88 2.33-4.57.69-1.07 1.3-1.48 2.22-1.48h.67q.22-.01.15-.26l-.05-.51c-.05-.15-.1-.26-.26-.26-.25 0-.66.08-2.04.08-1.49 0-1.94-.08-2.35-.08-.26 0-.36.26-.72.85-.36.61-2.6 5.62-2.91 6.23C1.53-.74.4-.89-.28-.89z' style='fill:%230e2b58;fill-opacity:1;fill-rule:nonzero;stroke:none' transform='translate(315.55 470.47)'/%3E%3Cpath d='M0 0q-.06-.15-.2-.15h-.46c-.21 0-.26.1-.26.25.15 1.02-.15 4.1-2.76 4.1-1.48 0-2.3-1.39-2.3-2.49 0-1.79 1.12-2.6 2.3-3.78s2.86-2.6 2.86-5.44c0-3.27-2.35-5.01-5-5.01-1.64 0-2.82.97-3.63 1.89-.26.25-.52.2-.67.05-.15-.2-.4-.61-.61-.97-.06-.1-.1-.15-.26-.1l-.3.15c-.16.05-.16.05-.1.25l1.88 5.58c.05.1.1.1.26.1l.4-.1c.11-.05.16-.1.16-.26-.72-3.68 1.28-5.42 2.86-5.42a2.7 2.7 0 0 1 2.76 2.69c0 1.63-1.27 2.6-2.4 3.83-1.58 1.74-2.91 3.07-2.91 5.7 0 1.84 1.43 4.5 4.75 4.5 1.38 0 2.6-.87 3.02-1.18q.14-.09.35-.1c.16 0 .31.36.41.87 0 .1.05.1.26.1l.3-.05q.22 0 .21-.15z' style='fill:%230e2b58;fill-opacity:1;fill-rule:nonzero;stroke:none' transform='translate(338.63 473.47)'/%3E%3Cpath d='M0 0c.36 1.28-.05 1.69-.72 1.69h-1.17c-.2 0-.26.05-.26.2l.16.67q0 .15.3.15c.3 0 1.69-.08 3.73-.08 2.2 0 3.28.08 3.63.08q.39 0 .3-.3l-.14-.52c0-.1-.05-.2-.26-.2H4.9c-1.07 0-1.66-.26-2.04-1.71L-.3-11.81c-.33-1.22.05-1.74 1.13-1.74h.92q.23-.01.15-.25l-.05-.51c-.05-.2-.05-.26-.3-.26-.31 0-1.49.08-4.1.08-2.14 0-3.47-.08-3.78-.08q-.21.01-.2.26l.15.56q-.01.21.2.2h.98c1.48 0 1.63.52 1.99 1.82z' style='fill:%230e2b58;fill-opacity:1;fill-rule:nonzero;stroke:none' transform='translate(344.86 475.82)'/%3E%3Cpath d='M0 0c2.3 0 3.22.2 3.68.46.1.05.15.1.25.1s.21-.05.21-.2c-.05-.41-.3-4.14-.26-5.16 0-.16-.05-.2-.2-.23l-.4-.08c-.16 0-.26.1-.37.4A18 18 0 0 1 1.9-1.63c-.56.44-2.4.67-3.58.67h-.5L-6.23-14c-.5-1.6-.25-2.17 1.08-2.17h1.02q.2-.01.15-.25l-.1-.51q-.04-.27-.3-.26c-.36 0-1.39.08-3.79.08-2.5 0-3.86-.08-4.11-.08q-.27.01-.23.26l.05.56q.01.21.3.2h.67c1.43 0 1.92.67 2.5 2.58L-5.06-.97h-.66c-2.36 0-3.48-.13-4.07-.56-.9-.67-2.22-2.15-2.84-2.87-.1-.1-.2-.1-.3-.1l-.41.26q-.14.09-.05.25c.3.57 1.89 4.14 1.94 4.3.05.15.1.25.26.25.1 0 .2-.05.4-.2C-10.27.2-9.05 0-6.39 0z' style='fill:%230e2b58;fill-opacity:1;fill-rule:nonzero;stroke:none' transform='translate(363.88 478.45)'/%3E%3Cpath d='M0 0c-.28-1.33.05-1.43.92-1.43h.56c.16 0 .2-.1.2-.2l-.1-.57c0-.15-.05-.25-.25-.25-.4 0-1.23.07-3.27.07-2.3 0-3.07-.07-3.38-.07-.15 0-.2.05-.2.25l.1.56c0 .1.05.2.26.2h.56c1.18 0 1.53.57 1.69 1.31l.82 3.78c.1.36.05 1.03-.06 1.33l-2.65 7.85c-.2.61-.72.97-1.59.97h-.56q-.21-.01-.2.2l.1.62c.05.15.1.2.25.2.36 0 1.02-.07 3.07-.07 2.2 0 3.06.07 3.37.07.2 0 .26-.05.26-.2L-.15 14c-.05-.16-.1-.21-.26-.21h-.66c-.82 0-.82-.61-.67-1.12L.31 5.8c.1-.4.3-.4.5-.05.37.56 4 5.93 4.25 6.7.33.97 0 1.35-.87 1.35h-.56q-.23.01-.16.26l.06.56c0 .15.05.2.3.2.36 0 1.33-.07 2.76-.07 1.59 0 2.35.07 2.71.07.2 0 .26-.1.26-.25l-.1-.51q.01-.28-.2-.26h-.47c-.87 0-1.38-.4-1.89-1.1-.4-.56-5.06-7.05-5.42-7.67a6 6 0 0 1-.87-2.2z' style='fill:%230e2b58;fill-opacity:1;fill-rule:nonzero;stroke:none' transform='translate(375.58 463.7)'/%3E%3C/g%3E%3C/svg%3E "Georgetown University")
'/%3E%3Cpath d='M126.06 1.03C57.11 1.03 1.04 57.07 1.01 125.95a124.2 124.2 0 0 0 36.56 88.4A124.2 124.2 0 0 0 125.92 251l.07.5v-.5c68.88 0 124.94-56.06 124.98-124.93a124.2 124.2 0 0 0-36.56-88.4 124 124 0 0 0-88.35-36.64M126 252h-.07a125.2 125.2 0 0 1-89.07-36.93A125.2 125.2 0 0 1 0 125.95C.03 56.5 56.55 0 126 0a125.2 125.2 0 0 1 89.13 36.96 125 125 0 0 1 36.87 89.1C251.96 195.52 195.44 252 126 252' style='fill:%23b39c1c;fill-opacity:1;fill-rule:nonzero;stroke:none' transform='scale(.59524)'/%3E%3Cpath d='M238.94 126.04c-.01 62.38-50.61 112.92-112.99 112.92-62.37-.03-112.93-50.62-112.9-113s50.6-112.92 112.98-112.9c62.38.03 112.93 50.6 112.91 112.98' style='fill:%23fff;fill-opacity:1;fill-rule:nonzero;stroke:none' transform='scale(.59524)'/%3E%3Cpath d='M126.03 13.45c-62.09 0-112.59 50.47-112.6 112.52-.02 62.06 50.46 112.58 112.53 112.6l.03.4v-.4c62.05 0 112.55-50.48 112.57-112.53S188.11 13.47 126.03 13.44m-.04 225.89h-.03c-62.48-.03-113.3-50.88-113.3-113.36C12.68 63.52 63.54 12.68 126 12.68c62.52.03 113.34 50.88 113.33 113.36s-50.87 113.29-113.34 113.29' style='fill:%23b39c1c;fill-opacity:1;fill-rule:nonzero;stroke:none' transform='scale(.59524)'/%3E%3Cpath d='M126 40.93c-46.86 0-85.02 38.1-85.08 84.96-.07 46.91 38.04 85.13 84.96 85.2h.13c46.84 0 85-38.11 85.05-84.95a84.4 84.4 0 0 0-24.83-60.2 84.5 84.5 0 0 0-60.13-25.01Zm0 170.67h-.13c-47.18-.06-85.53-38.53-85.47-85.7.07-47.12 38.47-85.47 85.6-85.47h.1a85 85 0 0 1 60.5 25.15 85 85 0 0 1 24.98 60.56c-.06 47.1-38.45 85.46-85.57 85.46' style='fill:%23baa32e;fill-opacity:1;fill-rule:nonzero;stroke:none' transform='scale(.59524)'/%3E%3Cpath d='M207.84 126.03a81.56 81.56 0 0 1-81.46 81.67 81.56 81.56 0 0 1-81.67-81.47c-.08-45.04 36.4-81.6 81.45-81.67a81.6 81.6 0 0 1 81.68 81.47' style='fill:%2366232e;fill-opacity:1;fill-rule:nonzero;stroke:none' transform='scale(.59524)'/%3E%3Cpath d='M202.05 101.15a33.9 33.9 0 0 0-42.39-21.88 33.9 33.9 0 0 0-67.8-.1A33.91 33.91 0 0 0 71 143.72a33.9 33.9 0 0 0 54.88 39.83 33.95 33.95 0 0 0 47.02 7.05 33.95 33.95 0 0 0 7.9-46.88 33.9 33.9 0 0 0 21.24-42.56' style='fill:%23fde8a8;fill-opacity:1;fill-rule:nonzero;stroke:none' transform='scale(.59524)'/%3E%3Cpath d='M127.34 50.78c.38 1.35-.07 11.88-.22 16.3.01 1.28-.06 6.86.05 8.8.1 1.96-.17 9.42-.15 11.35.43-1.72.64-2.7.47-4.54.6.5 1 1.6 1.01 2.59.41-1.73 1.32-6.22 0-10.75.75.5 1.87.7 2.1 6.76.5-1.89 1.3-8.4-1.26-9.47 0 0 2.03.56 2.67 2.49.41-2 .9-3.5 1.35-4.5-.2 2.03-.09 4.71.07 5.68.56-3.06 2-7.27 4.06-9.26a23 23 0 0 0-2.43 8.8s1.09-2.11 1.35-5.33c0 0 .32 1.8.42 2.55.49-1.6 1.85-5.56 2.95-7.14.72-1.9.64-1.53 1.08-2.5.01.97-.19 1.95-.86 3.21a82 82 0 0 0-1.47 5.8c1.15-2.57 4.15-7.83 6.22-9.12-1.18 1.72-2.72 3.17-4.28 9.25-1.99 1.87-8.18 7.5-11.8 16.29-1.3 3.45-1.76 11.82-1.68 17.94 0 0 .8-1.73 1.3-2.93-.03-2.39-.69-6.94-1.37-7.9 1.28 1.4 2.42 2.72 2.67 4.97.02-4.04-.58-9.32-1.79-10.88 1.6 2.15 2.2 3.03 2.3 4.22.2-2.02.04-2.55-.13-3.66a8.6 8.6 0 0 1 1.72 4.46c-.2-3.5-.48-6.48 1.49-9.5-.56 2.55-1.17 6-.4 7.78.38 1.17.6.96.59-.77-.03-1.71-.3-5.14 2.83-10.34-.7 2.99-1.29 3.98-1.08 8.16 1-3.07 3.83-9.53 6.05-11.07-.94 2.19-2.9 5.74-3.83 9.17.87-1.2 1.68-2.42 1.82-3.08.8-1.95 2.39-5.79 5.86-8.15a59 59 0 0 0-4.44 7.82c1.97-2.4 5.66-6.28 10.5-7.24-2.22 1.3-6.2 4.94-9.16 7.74 3.12-.94 4.92-1.71 7.47-.7-1.95.03-6.04 1.06-7.75 2.36 1.65-.25 3.73-.58 4.95.52-1.64-.12-6.2 1.05-8.48 2.57 1.94-.46 4.75-1.62 5.89-.51-1.35.07-5.5 1.25-7.56 3.02 2.22-.63 3.7-.97 5.06-1.43a42 42 0 0 0-7.18 4.66c2.3-1.07 5.18-2.46 7.42-2.12-2 .63-6.08 2.6-7.56 3.92 2.52-1.3 4.6-2.3 7.96-2.22-2.3.7-8.02 2.96-10.43 6.2 1.47-.75 3.1-1.67 5.36-1.33-1.57.75-9.83 2.9-9.58 14.6 1.02-1.57 4.18-4.96 6.03-6.11.18-2.55.66-6.22 2.22-7.5-.3 1.66-.7 4.03-.53 5.76.1.74.6.44.74-.56.13-1.33.89-6.34 3.1-9a23 23 0 0 0-1.39 7.8c.09.97.6.8 1.04-.46 0 0 .88-6.44 2.78-8.5-.34 1.82-1.05 4.89-.96 6.76.18.8.98.13 1.27-1.6a20.5 20.5 0 0 1 4.35-9.24c-.94 2.54-2.03 4.2-2.43 8.17-.14.9-.57 1.87.82-.46.64-1.96 1.68-7.48 7.38-11.31-1.61 1.6-3.27 5.2-4.93 9.7q-.98 2.92 1.32-.83c1.09-2.55 5.53-9.94 7.9-11.1 0 0-4.24 5.98-5.38 9.41-.44 1.05-.06 1.12 1.33-.91 1.4-2.11 3.6-8.05 8.67-10.35-1.47 1.51-5.14 6.26-5.86 8.59-.43 1.2.6.37.6.37.23-.3 1.1-1.28 1.91-2.42 1.17-1.67 5-6.42 8.56-7.8-1.47 1.2-4.89 4.09-7 8.31.98-.46 2.1-1 3.04-2.36.96-1.13 4.56-5.45 8.43-6.1 0 0-5.4 3.51-6.93 6.58-1.26.93-1.7 1.61.09.62.9-.7 2.43-1.53 3.24-2.6.67-.6 4.8-4.4 8.9-4.23-1.78.78-5.7 3.14-8.28 5.65.6.06.97-.23 2.07-1 1.12-.76 6.43-4.5 11.09-3.31a37 37 0 0 0-4.23 1.12c-.97.54-2.46 1.39-4.3 2.52 0 0 10.1-3.13 12.55-.53-1.21-.45-3.46-.7-6.36.38 2.62.26 11.59 1.02 14.5 5.08-1.75-.85-6.54-3.18-12.3-3.38 2.4 1.43 4.9 4.32 5.08 5.73 0 0-5-4.85-8.75-5.77 1.81.86 6.02 3.06 7.05 7.52-.99-1.33-5.31-6.2-9.95-7.18 1.57.8 6.48 4.02 7.74 8.86-1.52-2-6.53-7.37-10.36-7.84 2.43 1.67 6.4 3.63 7.52 7.8a16 16 0 0 1-2.89-3.31c-3.86-3.02-9.62-4.49-8.93-3.55 0 0 9.62 4.49 9.54 9.06-1.84-2.82-2.52-3.18-2.9-3.78-2.78-1.14-4.55-3.72-9.92-4.26 0 0 5.72 2.6 9.66 7.55 0 0-8.16-7.04-13.22-6.38 0 0 9.36 2.34 9.9 9.34-.6-1.2-5.2-8.2-11.97-7.97 4.41 1.36 6.6 2.67 8.66 6.16.01 1.1.14 3.95-.9-.9-1.11.17-1.88-1-3.46-1.96-1.59-.94-5.35-2.31-8.17-1.53 2.56.8 8.03 2.58 9.42 5.98 1.06.98 1.9 1.93 1.99 2.67-1.07-1.1-2.06-2.2-2.73-2.86-.76-.51-2.27-1.32-2.72-1.9-1.05-.52-2.04-1.17-9.07-1.9 4.04.48 8.9 1.06 11.76 8.05-1.3-1.77-7.59-8.7-15.53-5.67 4.03-.14 9.52 1.8 12.1 5.5 0 0-4.23-3.74-14.09-4.14 1.42.22 2.17.57 2.47.78 1.35.15 6.94.44 10 5.01-2.4-1.66-6.7-3.86-13.35-3.6-1.2-.06-2.15-.13-2.82.33 2.16-.03 7-.17 10.58 3.36-2.27-1.09-10.64-2.26-12.8-1.75 2.69.25 8.55 1.8 9.75 3.2-1.5-.41-3.66-.91-4.34-1.27-1.35-.27-9.8-.77-12.67 2.86-1.1 1.36-3.37 3.78-3.94 6.33 1.54-1.59 2.28-2.73 6.6-3.97 1.25-.63 5.05-1.86 4.11-4.6.74.36 2.12 2.05-.54 4.19 1.26-.26 1.7-.63 2.39-1.1.66-.44 3.69-2.36 5.86-2.55a33 33 0 0 0-4.9 3.52 2.4 2.4 0 0 0 1.73-.49c.8-.3 3.85-2.21 8.02-2.57-2.07.93-4.75 2.1-6 2.85-.45.4-.97.98.6.65 1.26-.3 4.65-3.57 9.2-3.7-2.3.99-4.89 2.24-6.2 3.74-.67.84.31.98 1.12.38a7 7 0 0 1 2.29-1.54c.73-.75 2.06-2.27 8.78-2.21-2.23.55-6.18 2.03-8.47 3.55-.58.53-1.25 1.58 1.36.58a16 16 0 0 1 11.69-2.77c-2.17.24-7 1.58-9.46 3.28-.8.6.02.57 1 .19 0 0 7.18-3.77 12.36-1.3-1.55-.06-7.75.48-10.56 2.38 1.35.14 3.65-.06 4.77-.52 1.49-.3 5.51-1.34 8.5-.18-1.86.03-7.16.55-8.49 1.39-.66.37.01.6.83.44.83-.17 5.8-1.42 11 .74-2.03-.12-7.64-.5-9.5.2-.8.54-.2 1.06 1.36.8 1.57-.24 6.77-1.52 10.78 1.12-2.78-.62-7.78-.48-9.19.13 2.69.2 5.9 0 8.24 1.9-2.32-.49-5.16-.69-6.2-.35 2.1.56 6.57.27 10.06 3.88a33 33 0 0 0-8.17-2.26c-.82 0-.14.88 1.14 1.16 1.34.17 5.24.47 8.34 3.93-2.1-1.17-5.63-2.3-7.03-2.3 2.9 1.3 5.16 2.1 5.64 3.14.89.79 2.32 1.76 2.64 2.5-1.6-1.03-4.6-3.07-5.95-3.12.75.8 4.39 3.73 5.97 10.3-1.21-1.42-4.88-7.04-5.56-8.15.63 2.08 1.18 4.3 1.48 4.69-1.14-1.41-3.46-6.37-5.05-8 .48 1.49 1.98 6.62 2.57 7.07-1.75-2.37-3.81-6-4.6-7.94-.45-.97-1.36-1.61-1.59-1.86a13.5 13.5 0 0 1 2.21 8.28 42 42 0 0 0-.85-2.83 19 19 0 0 1-1.79-3.63c-.75-1.18-2.12-2.8-2.35-3.11a5 5 0 0 0 .32 1.71c.46.6.92 1.62 1 2.38.4 1.19 1.01 2.69 1.62 3.05-1.73-1.85-2.58-2.21-5.04-7.77-.54-1.88-.62-1.35-1.07-1.47.31 1.53 1.67 7.11 3.28 9.57-1.37-1.25-3.42-4.14-4.3-8.24-.4-1.47-1.46-2.43-2.14-2.64.71 1.48 2.16 4.2 2.2 7.06.16 1.11.41 3.34.41 3.34-.84-2.22-3.13-10.4-6.2-11.78 1.81 2 2.3 4.29 2.24 10.72 0 0-1.27-10.45-6.98-12.6 1.2 1.19 3.94 4.14 3.57 9.73-.54-1.93-2.5-7.72-5.42-9.48 1.22 2 2.74 4.15 2.19 7.82-.25-1.42-1.67-7.37-5.05-8.38 1.37 1.64 2.89 3.1 2.7 6.48-.77-1.87-3.3-7.13-5.46-7.11 1.43 1.33 2.93 2.43 2.9 5.58-1.13-1.78-3.73-5.4-5.76-5.75 1.59 1.4 3.03 2.34 3.36 5.03-.76-1.1-2.66-4.36-7.46-5.42 1.35.8 3.55 2.37 3.72 4.53-1.15-1.4-5.83-5.92-10.21-3.84-1.56.85-4.07 2.6-5 5.22.07.9.01 1.5.01 1.5 1.5-.1 4.33.02 7.42 1.76 1.43.57 1.88.72 2.61.11.83-.46 4.98-2.16 8.36-1.54-2.32.4-5.51 1.2-7 2.56-.65.62.03.96 1.59.36 1.78-.84 4.58-2.61 11.6-2.4-2.45.54-8.48 1.9-9.87 3.5-.94 1.05-.14.82.6.36.9-.4 2.68-1.23 3.41-1.77-.66.9-2.21 2.13-2.73 2.66 2.52-1.09 7.2-4.2 11.7-3.02-1.86.06-6.04 1.3-9.67 3.88-.65.62-.58 1.2 1.2.21 1.86-.7 7.28-2.71 11.5-.17-2.01-.4-6.65-.8-10.5 1.59-.82.68.3.58 1.12.34 1.19-.37 8.12-1.83 12.33.35-2.09-.1-8.95-.17-10.43 1.05-.82.82-.07.97 1.04.66 1.12-.32 7.45-1.91 11.39 1.55-2.2-.8-6.54-1.86-9.57-.16-.74.51.3.5.6.42 1.42-.08 7.69-.54 12.6 3.57-2.79-1.16-6.45-2.52-10.41-1.86-.9.23-.35.88.62.94 1.72.15 9.11.48 12.29 3.65-2.02-.72-4.43-1.8-9.13-1.96-1.87-.06-1.2.53-.15.58 1.06.07 3.59.49 4.12.86-.9.16-3.13.1-3.13.1-.51.1-.29.7.62.76 1.1-.19 6.93-.19 10.71 3.11-2.25-.78-6.3-2.13-8.76-1.66 1.13.43 5.47 1.72 9.26 4.66-2.26-.96-7.36-2.82-8.19-2.67.85.66 1.07.97 2.2 1.47 1.04.3 6.52 2.3 8.37 6.09-1.44-1.27-5.21-3.89-6.49-3.95-1.26-.03.02.53.7.89s3.99 2.1 4.99 3.8a11 11 0 0 0 2.04 2.3c-1.36-.95-1.9-1.17-2.56-2.05-.76-.51-2.95-1.83-3.56-1.88 1.22 1.38 1.98 1.82 3.18 2.55.84.74 3.4 2.5 4.19 5.47a19 19 0 0 0-4.4-4.03c.17.67.25 1.03.79 1.54.75.8 2.8 3.1 3.5 5.47a8 8 0 0 0-1.6-2.06c-.67-.43-1.1-1.44-1.67-1.9.28.92 1.56 4.26-.56 7.57.23-2.1.13-4.9-.39-6.45-.13 1.1-.49 2.34-2.01 3.1a7 7 0 0 0 .47-6.27c-.17 1.09-.5 3.87-2.32 5.08.56-.94 1.96-4.54.17-8.02a7 7 0 0 1-.79 3.24c.04.61-.28 2.26-1.49 2.61.47-.93 2.28-4.88-1.19-10.05.24 1.47 1.02 6.01-1.5 8.11.53-1.62.94-7.77-.53-9.28.28 1.51 1 6.6-3.88 8.92 1.4-1.86 4.64-6.54.52-12.76 0 0-.04 5.09-1.3 6.85.02-2.25.5-7.9-2.12-10.06.33 2.4 1.01 7.66-1.47 10.79.43-2.2 1.34-8.94-1.18-12.26.2 2.07.16 6.94-.82 8.64.12-2.25.38-8.13-2.18-10.96.65 2.3 1.6 6.59-.43 9.54.13-3.01-.34-8-3.07-11.6.3 1.61 1.15 5.97-.65 9.24.01-2.64-.26-10.48-3.98-12.66 1.14 2.34 3.46 6.85 1.84 11.63-.16-2.97-2.1-9.45-4.89-12.98.93 2.5 2.43 5.77.08 10.3.3-2.51-.75-9.67-3.59-12.5.35 1.08.76 2.52.85 4.76.18.77.66 2.9 1 3.41-.79-1.1-2.66-5.68-3.65-8.76-.78-1.15-1.2-1.34-1.76-1.65-.83-.41-2.41-1.4-5.46-.96-.03 4.9.8 11.66 1.63 14.85s2.33 10.9.36 17.76c-.3 2.35-.17 4.26.47 6.95-.41 2.7-.37 3.92.28 7.17-.5 2.42-.5 4.04.22 7.5 0 0-.16 5.78 1.88 8.32 0 0-.18.3-.65.1-.45-.26-1.2-1.36-1.87-2.8-1.34.68-3.43-2.64-4.46-3.71.88 0 2.97-.23 3.85-.65.37-.16.16-.79-.04-.71-2.76.73-6.1.88-8.53.28.02 3.5-.93 6.2-1.95 7.35-.41.44-1.21.37-.91.03.47-.7 1.55-2.12 1.15-8.01.6-3.5.6-4.97 0-7.55.53-2.73.74-4.22.18-7.17.46-2.7.7-3.89.24-6.94-1.94-6.38-1-14.46-.28-17.77 0 0 1.76-7.81 1.47-12.36-.7.75-1.25 1.04-1.62 1.7.2 1.13.64 4.2-2.27 7.6.37-1.58 1.24-3.5 1.03-6.34-.12-.6-.83-.26-1.3.63-.36 1.08-.85 6.23.49 9.52-.8-.72-2.28-2.71-2.13-7.86-.18-.68-.68.12-.61 1.06-.03 1.08-.22 4.44.59 6.1.3.84.88 2.39.24 3.86-.2-1.4-1.07-3.45-1.46-4a9 9 0 0 1-1.08-4.53c-.37.67-.56 3.6.01 5.1.3.99 1.24 4.23-.02 6.27-.18-1.4-.21-3.34-.9-4.47 0 0-1.05-3.07-1-4.02-.16 1.85.43 6.7.85 9.28a12.6 12.6 0 0 1-2.1-6.07c-.02-.96-.31-2.4-.6-1.06-.07 1.4-.32 6.78 1.25 10.89-.86-1.04-2.29-2.98-2.65-8.18-.17-.73-.29-.5-.32.57-.05 1.06.17 9 1.1 11.02-1.45-3.51-2.26-5.7-2.48-9.65-.07-1.07-.51.17-.5 1.06.01 1.06-.03 5.5-.29 7-.16.78-.14 2.24.04 2.75-.58-1.16-1.34-3.74-1.34-7.66-.44.97-1.35 3.72-.3 10.2-.8-1.2-1.83-2.43-1.5-6.6-.3 2.1-.96 6.98-.65 9-.84-3.76-1.82-6.15.4-10.9 2.02-4.1 7.86-14.39 19.2-24.23 0-1.08-.03-2.63-2.99-1.97-1.67.47-5.06 2.03-6.77 3.9 0 0-1.4 4.83-2.42 7.77.3-2.64.65-5.68.35-6.84-.65 1.63-1.71 5.34-1.68 7.3 0 .96-.31 2.35-.64 2.7.04-1.46-.03-2.47-.26-2.9a17 17 0 0 1-.12-4.64c-.54 1.68-2 4.84-1.81 10.38-.64-1.13-1.8-4.12-.64-8.69-.77.9-2.81 2.63-1.87 13.48-.75-.95-2.52-3.36-2-10.16-.7 2.01-1.25 6.06-1.18 11.88-.93-2.62-1.91-4.78-.77-11.02-.72.63-1.86 2.55-1.27 9.5.13.71.41 1.72.28 3.4-.4-1.18-1.73-3.79-1.78-10.78a25.6 25.6 0 0 0-.28 14.9c-1.15-1.68-2.96-6.35-2.36-11.9-.4.11-.44.5-.48 1.34-.11 1.13-.21 9.2-5.1 12.3.27-.68 3.05-2.9 3.2-11.94-.72.93-3.64 4.09-.83 13.63 0 0-2.27-1.92-2.65-10.04-.33.57-.62.9-.64 1.96-.1 1.07.37 6.73-3.49 11.15.8-2.38 2.08-3.61 2.04-10.39 0 0-2.3 3.89-3.62 10-.41 2.43-1.37 5.37-2.1 5.98a301 301 0 0 0 1.27-9.25c-1.13 2.92-2.82 9.72-6.48 12.74 1.26-2.15 2.47-3.73 3.27-6.89.3-1.4 1.34-4.03 1.5-4.87a78 78 0 0 0-5.06 6.56c.58-2.01 3.36-7.11 6.08-10.16a37 37 0 0 0-5.7 5.4 41 41 0 0 1 7.11-7.84c-1.29.36-2.95 1.18-5.71 3.56.98-1.53 3.57-4.2 5.86-5.3 1.21-.64 1.82-1.47 2.04-1.75-1.9.53-7.13 2.9-9.5 5.1.76-1.3 4.34-5.66 10.66-6.98-2.69.32-5.21.86-9-2.43 2.2 1.14 7.81 2.22 11.42-.23 0 0-6 1.03-9.1 4 1.16-1.7 6.55-5.7 11.3-6.56-1.56.16-7.26 1.34-8.82 2.04a41 41 0 0 1 10.2-3.45c1.18-.17.67-.57 1.17-.8 0 0-7.45.05-10.29 2 1.1-1.32 5.72-3.9 11.72-3.88-1.52-.32-3.76-.5-8.5 1.02 1.88-1.21 6.56-3.57 11.93-3.19-.72-.22-1.24-.5-1.5-.55 1.28-.23 2.45-.31 3.17-.77-1.3-.42-5.62-.47-8.56.92 1.05-.98 3.9-2.48 7.96-2.88-.78-.49-1.74-1.19-1.93-2.53 0 0 3.46 3.09 7.9.77-1.45-.03-4.63.08-5.24.13 1.6-.69 3.67-1.4 6.45-1.87.97-.14 1.4-.36 1.57-.69-1.4.18-3.97.38-5.93.96 1-.85 4.05-2.4 8.2-2.28.9-.01 1.51-.27 1.72-.48 0 0 4.4-2.94 5.84-3.5 1.45-.59 3.17-1.06 4.5-.57-.62-1.82-3.17-5.87-9.66-5.59 1.8-1.88 7.27-.64 9.47 2.27 0 0-.3-2.38-.65-3.38-1.47-1.11-3.83-2.26-7.45-1.78-2.12.4-4.23 3.92-5.48 7.94 0 0 .14-3.7 1.91-7.14-1.93 1.04-5.17 3.94-5.89 11.26 0 0-2.3-4.62 1.14-9.88-1.78 1.6-3.93 2.67-5.73 11.97-.28-3.07.18-7.71 2.07-10.87-1.85 1-3.83 2.82-3.79 11.63 0 0-2.06-3.63-.43-9.48-.94 1.58-1.77 1.9-2.17 5.05-.2 1.64-1.42 5.16-2.14 6.82.19-2.47.64-6.44.64-7.41-.1-1.48.56-2.7.63-3.07-1.32 1.52-5.15 5.52-3.92 13.73 0 0-2.2-3.48-.95-9.4-1 2.47-2.72 8.18-2.72 8.18.25-2.77.56-7.92 1.79-10.17-1.4 1.57-3.36 5.12-4 12.5-.55-1.92-1.1-4.38.75-10.22-1.38 2.04-3.45 4.45-3.98 14.23-1.02-3.2-1.74-5.96.8-12.33-1.26 1.37-2.12 3.7-2.75 6-.35 2.4-.95 7.65-2.1 10.73 0 0-.38-6.12.8-12.79-1.37 3.9-2.68 6.1-3.47 13.65-.72-2.55-1.5-5.9 1.45-12.74-1.53 2.5-2.74 6.36-3.73 9.77a18 18 0 0 1-.32-3.85s-1.5 2.57-2.65 4.8l-.54-.24c.18-1.7.9-4.32 2.78-6.55-2.15 1.27-4.85 3.4-6.42 4.6l-.27-.17a29 29 0 0 1 8.15-7.52c-1.42.52-5.51 1.84-6.85 1.71 1.22-.66 7.1-3.62 7.79-4-1.39.2-3.62.43-7.36 2.17 1.21-1 4.69-3.4 9.76-4.3 0 0-5.47-.02-11.03 2.4 2.15-1.41 5.07-3.46 13.18-4.59.64-.1.98-.28.08-.26-.88.02-3.2.16-4.7.5 1.98-.72 4.09-1.77 6.47-2.06-1.28-.2-6.09-.1-10.22.38 1.53-.58 6.16-2.46 13.25-2.18.79-.13 1.8-.44.34-.39-1.46.07-4 0-5.46-.21 1.57-.31 2.45-.86 6.1-.87.62 0 .87-.3-.3-.36-1.19.01-7.5.22-10.3.06 1.45-.35 3.5-1.03 12.23-1.4a40 40 0 0 0-9.98-.9c1.64-.47 5.87-1.85 12.84-.26 2.06.27 2.98-.5.66-1.08-.9-.19-8.46-1.5-10.33-1.51 2.65-.23 8.13-.72 13.04.63.68.25 1.72.14.38-.41-1.36-.55-4.4-1.84-9.38-2.32 0 0 6.77-1.27 12.42 1.5.53.3 1.97-.07.58-.68-1.38-.63-4.57-1.75-6.15-4.48 1.29.8 5.7 3.48 10.7 3.75-1.23-.44-4.58-1.87-4.94-4.46.86 1.02 3.33 3.82 10.27 3.42.55.03 1.3-.19.06-.48-1.23-.27-2.29-.93-6.24-1.21 1.32-.4 5.89-.38 9.45.8 0 0-.69-.66-2.15-1.32 1.34-.05 2.43-.21 5.66 1.6 0 0 4.11-.58 6.77.7-.98-1.23-1.86-2.63-4.64-4.2-1.2-.24-6.03-.75-8.45 3.22.36-2.28 2-3.87 4.19-4.76-1.6.24-.02-.08-.02-.08s-5.3.6-8.97 4.7c.9-1.97 3.28-4.94 7.11-6.05-1.64.13-6.34.88-11.05 5.8.44-1.51 2.59-5.34 7.19-7.23-1.27.19-4.58 1.24-6.49 3.8-.84 1.16-2.6 3.36-5.07 3.44 1.3-.93 2.74-2.5 3.61-4 .73-1.08 2.9-3.62 4.72-4.4-1.37.42-5.36 1.24-9.64 7.69.38-2.25 1.49-5.55 6.35-8.46 0 0 .84-.57-.4-.3-.73.35-5.07 2.28-8.4 9.17 0-1.7.62-5.66 4.7-9.63-1.3.76-4.96 2.4-8.46 9 .13-1.63.7-6.27 6.62-9.83-1.33.61-5.12 1.82-10.05 9.46.8-2.36 3.44-6.88 6.7-9.68 0 0 1.03-.89-.38-.26-.86.42-5.01 2.17-9.05 10.1.23-1.91 2.16-8.77 6.25-10.98-.95.3-6.36 2.93-8.98 10.02.02-1.28 1.13-6.1 5-9.86.34-.33.3-.64-.75 0-1.02.66-5.7 3-7.93 8.98-.12-.98-.25-2.05.14-2.89.45-.82 2.12-4.24 4.99-6.57.3-.1.23-.26-.56.02 0 0-6.2 3.03-9.3 10.95-.04-1 1.57-5.73 3.45-8.25.25-.3.76-.95 1.23-1.6a7 7 0 0 1 2.14-1.63c.04-.22-.27-.68-1.44.13 0 0-4.59 2.89-6.3 8.3-.04-1.75.3-4.78 2.58-7.37-1.48 1.35-5.28 4.7-7.43 8.8.36-1.94 1.8-5.65 3.9-7.8-2.27 1.24-6.49 3.18-9.8 9.96.32-1.3 1.56-6.11 5.83-10.2-1.3.51-7.05 3.54-8.3 4.16A25 25 0 0 1 65.1 97.8a100 100 0 0 0-7.32-.25c1.08-.52 3.38-1.04 11.37-.86 0 0-1.24-1.17-7.74-1.34 1.2-.27 6.37-1.51 10.95.55.52.27 2.06.57 1.08-.28a32 32 0 0 0-8.67-2.7c2.65-.13 7.27-.35 12.88 2.54.73.36 3.23.89 1.57-.06-1.65-.96-5.87-3.38-10.78-4.34 1.94.05 7.59-.15 13.8 4.27.57.4.86.27.42-.28a23 23 0 0 0-8.01-5.54c1.23.06 5.46.56 10.12 5.2.68.6 3.88 2.54 2.7.9-1.32-1.59-3.5-4.25-7.52-7.21 1.86.8 6.34 2.51 10.26 7.59.64.77 1.58 1.31 1.53.45-.3-.82-2.31-4.97-8.29-5.56.82-.18 6.96-1.76 10.34 5.62.44 1.04 1.68 2.1 1.74.67-.28-.91-2.08-6.8-5.63-9.53 0 0 4.76 1.46 7.14 8.62.44 1.53 1.91 3.1 3.27 3.21-1.1-1.16-3.41-3.3-5-9.84.96 1.68 4.84 7.71 7.91 10.32.52.56.68.37.44-.17-.47-.99-2.1-3.36-3.65-5.06-.57-.5-2.12-1.88-2.63-2.94.95.77 1.6 1.06 2.2 1.38.6.45 3.92 3.24 6.93 8.06-.43-1.86-1.29-4.45-.15-8.12.11 2.1 1.63 8.87 4.31 10.93-.62-1.41-1.2-3.28-.77-6.91.4 2.18 1.21 6.48 3.7 8.4 0 0-1.41-2.37-.17-6.6.15 1.55.35 5.91 2.5 7.95.69.66 3.89 2.96 4.47 3.85-.82-1.67-2.26-3.93-1.21-7 0 0 1.76 6.51 5.1 9.3.07-1.6.11-7.17-1.54-7.3-.94-.33-4.12-1.07-5.52-2.55 1.01.23 4.48.48 5.02.64-1.4-1.16-3.05-1.07-4.1-1.6 0 0-2.07-.8-3.55-.89 1.17-.43 2.74-.94 6.63-.14-1.62-.76-3.35-2.3-8.97-2.6 1.02-.38 3.39-1.34 7.52.23a13 13 0 0 0-6.07-1.73 13 13 0 0 1-5.62-.97c2.46.06 8.88-.25 11.25.68-2.27-1.66-4.74-2.68-12.96-2 0 0 3.82-2.68 9.92-1.12.72.22.91-.19-.07-.55-.97-.36-6.83-2.11-12.62-.17 1.02-.87 4.14-3.08 10.2-2.04-1.87-.5-5.32-1.28-12.19-.76 2.2-.64 5.23-2.46 11.68-.92-1.36-.69-6.5-3.03-14.24-.28 0 0 5.87-4.3 10.95-2.58-1.63-.76-6.22-1.49-10.87 0 1.5-.88 3.56-2.29 8.37-2.32-1.35-.32-4.27-.88-10 1.04 1.75-1.06 3.96-2.93 7.62-2.8-1.65-.47-6.75-1.47-13.06.7.85-.78 3.88-2.8 7.24-3.04-1.45-.08-5.2-.3-10.28 1 1.02-.95 3.47-2.01 6.3-2.15 0 0-1.53-.05-3.5.08l-.64.07c-1.91.18-4.12.58-5.7 1.43.36-.32 1.75-1.2 3.97-1.85.5.08 1.16.26 1.71.41l.65-.05c.02-.2.07-.75.06-.9 3.71-.55 8.75-.13 14.54 3.35a27 27 0 0 0-7.41-7.44c1.54.6 6.34 2.41 10.28 8.44 0 0-.7-3.65-4.78-7.54 1.57.95 5.06 4 7.34 9.42a17 17 0 0 0-4.16-8.78c1.2.83 4.64 3.41 6.31 10.87-.03-1.9-1.14-6.97-2.06-8.3 1.8 2.6 3.31 4.1 3.9 9.7.1.85.64 2.19.58.47-.07-1.7-.48-7.1-1.69-9.05 1.4 1.9 3.61 5.32 3.63 11.07 0 0 .49 3.5.8.88.04-1.1.4-5.49-1.13-8.38.84 1.02 2.96 4.11 2.88 11.27 0 .61.31 1.49.54 1.86.24.5.58 1.39.64-.3.1-1.52.38-4.6-.54-6.04.64.7 2.4 2.88 1.76 8.41-.1.91-.04 2.25.4 1.46.3-.5.58-1.35.57-2.21-.2-1.76-1.07-16.84-10.39-25.61-1.04-2.5-2.39-6.07-7.13-8.46 1.47.37 5.13 1.81 7.76 5.83-.8-2.18-2.26-5.63-3.51-6.79 2.5 2.6 4.84 5.6 6.15 10.72.24 1.17.9 2.29.7.92-.2-1.63-1.3-6.3-2.06-7.9 1.35 2.63 3.03 5.23 4.4 11.92.22.85.34 1.08.44-.16-.02-1.38.35-3.84-.84-6.97.95 1.41 2.6 2.32 2.16 10.35-.06 1.06.17 2.23.41.81.25-1.43.58-3.96.43-6.73.63 1.82 1.27 4.8.74 9.18-.24 1.57.27 3.54.5 4.37 0 0 .75-5.1.03-8.62.47.99.97 1.9 1.24 3.53.1-2.16.06-27.35 2.02-32.77' style='fill:%23b39c1c;fill-opacity:1;fill-rule:nonzero;stroke:none' transform='scale(.59524)'/%3E%3Cpath d='M122.36 160.26c2.57.56 4.4.45 6.59-.4.4-.11.5.28.16.43s-1.41.66-3.75.89c.14 1.26.28 2.4.18 4.17a9 9 0 0 0 3.85-.7c.3-.22.44.3.22.45-.2.12-3.33 1.54-7.52.43.4-2.13.52-3.25.27-5.27' style='fill:%23fff;fill-opacity:1;fill-rule:nonzero;stroke:none' transform='scale(.59524)'/%3E%3Cpath d='M123.47 121.02c.74 12.53-.38 15.73-1.8 25.97-.51 4.74.15 9.7 1.65 10.3 1.72.39 1.85-.86 1.53-2.14-1.5-6.8-.08-10.85.08-21.72.2-14.79.92-36.95.9-38.7.02-1.38.15-5.3.13-6.1-.46 1.06-.75-.2-1.03-1.28.04 1.95.08 2.69.16 5.22a9 9 0 0 0-.94-2.44c.7 2.02.8 6.07.86 7.27-.08 2.39-.28 4.62-.46 4.8-.3.2-1.2-1.18-1.7-2.25a56 56 0 0 0-14.55-17.1s9.14 7.59 14.28 17.82c1.02 2.76 2.21 2.9 2.5 12.8-.25 3.46-1.16 3.33-2.75.58-5.48-7.77-28.54-21.48-54.63-15.89 18.88-2.96 39.34 1.99 52.07 13.97 1.37 2.08 3.41 3.83 3.7 8.89' style='fill:%23ebebeb;fill-opacity:1;fill-rule:nonzero;stroke:none' transform='scale(.59524)'/%3E%3Cpath d='M119.51 113.68c-4.97-2.68-26.51-.75-47.1 20.26 17.46-17.05 39.99-23.75 47.5-19.46-.16-.4-.4-.8-.4-.8' style='fill:%23ebebeb;fill-opacity:1;fill-rule:nonzero;stroke:none' transform='scale(.59524)'/%3E%3Cpath d='M121.6 123.16c-3.17-1.63-8.05 1.52-24.33 14.14 0 0-10.14 7.82-14.79 15.77 7.25-9.96 15.18-15.34 23.17-21.45 3.16-2.3 13.5-10.8 15.97-7.4zm5.34-14.92c2.48-6.03 7.68-18.8 14.56-23.46 0 0-7.82 5.4-14.59 25.65-.02-.97.03-2.2.03-2.2' style='fill:%23fffdeb;fill-opacity:1;fill-rule:nonzero;stroke:none' transform='scale(.59524)'/%3E%3Cpath d='M127.5 115.45c3.98-6.47 19.1-15.76 27.6-20.72a48.5 48.5 0 0 1 21.68-6.1c-5.92.72-12.44 1.8-19.97 5.62-8.81 5.02-27.1 16.13-29.35 23.19m.86 1.35c1.3-1.83 4.29-4.74 12.7-4.52 6.42.32 24.21 2.78 35.65 13.71-4.86-3.59-10.99-8.72-26.27-12.01-5.42-.93-18.04-3.57-22.2 4.08.1-.57.12-1.26.12-1.26m-.16 5.01c6.04-.76 20.06 8.84 27.73 15.13 3.78 3.12 11.54 8.56 17.84 19.12-7.6-10.76-13.09-14.83-19.72-19.93-2.2-1.73-20.28-15.58-25.83-13.37-.06-.32-.02-.95-.02-.95m-5.9 42.96c2.58.42 4.65.39 7.09-.4.33-.24.54.21.37.4-.7.33-1.74.63-4.13.82.08 1.68.15 2.39 0 4.5 1.54.08 2.64-.26 4.06-.67.33-.23.5.3.32.41-.25.23-3.77 1.76-7.93.56q.63-2.6.22-5.62m-.32 6.7c.46 1.71.54 3.83.02 6.31 0 0 4.02 1 8.16-.38.39-.2.14-.84-.23-.7-.58.22-1.91.61-4.2.58.1-1.98.05-2.87-.07-4.72 1.63-.13 3.4-.37 4.38-.83.34-.2.22-.74-.13-.63-1.9.66-4.19 1.14-7.93.37' style='fill:%23ebebeb;fill-opacity:1;fill-rule:nonzero;stroke:none' transform='scale(.59524)'/%3E%3Cpath d='M41.99 93.84q.16-.4-.3-.56l-1.29-.55-3.3 8.1-1.82-.74L38.6 92l-1.07-.43.69-.9-.57-2-2.71 6.65-1.62-.67 3.51-8.58q.75-.43 1.28-.18l.26.15q.12.05.23.32l.83 3.6 3.01-7.35 1.81.75-3.08 7.5 1.93.79q.79.47 1 1.53l-1.14 2.74-.82-.02q-.54 0-.74-.1-.17-.05-.11-.23zm-8.01-6.43-1.58.88.48 1.82zM27.56 85l1.87-1.06.7 1.18-2.03 1.16.7 2.42-1.16.7-.7-2.31-1.38.98-.26.4-.87-1.25 1.95-1.41-.85-1.5 1.35-.82zm6.55 2.1 1.58-3.9-1.16-.48-1.16 2.82L32 85l1.15-2.83L32 81.7l-1.09 2.67-1.46-.6 1.1-2.67-1.2-.5-1.17 2.9-1.42-.57 1.92-4.72 7.77 3.17.6-1.47 4.08 1.68-.8 1.94-2.54-1.05-5.87 14.34 2.55 1.05-.86 2.07-4.07-1.66.66-1.67-7.52-3.06 1.94-4.71 1.43.6-1.15 2.8.92.39 1.2-2.94 1.46.6-1.2 2.93 1.2.5 1.2-2.93 1.4.57-1.22 3.02 1.09.45L32.5 91h-.78l-.39-1.99-1.5 1.03-.6-1.15 1.5-1.2-.62-1.86 1.26-.47.51 1.54 1.56-1zm26.75-39.72 6.57-5.52 1.23 1.46-6.2 5.21a18 18 0 0 0 5.37 2.81q3.63.86 7.55 0h.13l.06.06q.06.09.01.1l-.16.93q-.08.59-.1 1.07l-.18.18q-1.56.25-3.1.3-1.55.05-3.27-.21a23 23 0 0 1-5.47-2.31q1.04 3.5.85 6.82a29 29 0 0 1-1.57 6.08l-.07.14q-.06.06-.22.04a7 7 0 0 0-1.73-.26h-.06l-.04-.14q.72-1.87 1.13-3.52.43-1.66.53-3.32a15 15 0 0 0-1.83-6.97l-6.5 5.46-1.24-1.46 6.67-5.6-4-4.78 1.76-1q.53-.22.72 0 .14.17-.02.62zm45.66-18.74.1.5.92-.19-.1-.5zm-1.92-1.02 4.17-.92.71 3.28-4.18.9zm-.06-1.53 3.57-.78.26 1.2-3.57.8zm-.42-1.68 3.61-.8.27 1.25-3.6.79zm-1.05-3.67 4.15-.91.32 1.42-4.15.93zm.3 3.4-.33-1.52 4.7-1.05.19.91.53-.93.53.18.52-1.46.42-1.13 1.47.47q.3.13.34.27.06.24-.5.36l-.9 2.07.33.23.9-2.02 1.47.6.16.14.1.14q.06.25-.64.4a10 10 0 0 0-.96 2.54l.58-.13-.3-.57 1.19-.74 1.46 2.59-1.3.56-.26-.44-.16-.43-.6.32.26 1.1 1.04-.47 1.58 2.37-1.3.6-.49-.7-.73-1.26.48 2.15-1.48.32-.43-1.93q-.03.55-.08 1.08-.09.53-.2 1.02l-1.48-.26q.09-.32.19-1.29l.15-1.27 1.3.21-.26-1.2-1.06.28q-.26.37-.42.45-.2.05-.34-.3l-.63-1.26 1.4-.37.28-.88-1-.44-1.13-.32zm.27 14.77h-1.98l.38-4.9 10.29-2.28-.07-.36-10.77 2.37-.37-1.67 12.61-2.78.8 3.67-10.71 2.36-.08.73L114 33.8q1.37-.31 1.53.5.06.17 0 .58l-.36 1.08-.38 1.08a3.6 3.6 0 0 1-2.62 1.87l-2.61.6q-.3.05-.42-.45l-.57-1.03-.07-.05q.04-.1.1-.1l.16-.06.14-.06 2.59-.58h.08q.9-.17 1.32-.96l.08-.3.2-.35-9.48 2.08zm-2.69-9.5.14.26q.05.2-.1.35l-.19 1.27-.1.57-.14.6-1.5-.34.63-2.92zm.7-7.7q.3.15.39.38.05.21-.5.35h-.1l-.92 1.83.34.26.35-.78.43-.83 1.31.68c.07.06.1.17.18.3q.06.28-.42.37l-.68 1.22-.51 1.17.71-.35-.1-.16-.14-.26 1.13-.85.73 1.17.66 1.17-1.22.74-.34-.73-.67.23.24 1.2 1.04-.63q.72 1.14 1.34 2.33l-1.2.85-1.04-2.03.47 2.17-1.47.31-.77-3.51-1.34.49q-.15.46-.43.53c-.1.01-.23-.08-.38-.35l-.6-1.26 1.5-.55.3-.57.22-.69q-1.08-.7-2.23-1.21l.76-1.43.55.25 1.12-2.35zM99.4 33.2v1.77q0 .84-.1 1.86a61 61 0 0 1-.25 3.66l.13.45q.14.62-.18.73-.27.05-.77-.28l-1.18-.84a62 62 0 0 0 .83-6.4l.17-2.17zm-4.5-5.77 1.05.3c.24.1.57.19.96.36q.75.28 1.47.66l-.75 1.7q-1.5-.77-3.41-1.43Zm-.36-5q1.93.87 3.3 1.58l-.89 1.53a19 19 0 0 0-3.24-1.61Zm55.64 11.08-.83 1.08 5.69 1.41-.55-1.3zm7.77-3.7-9.07-2.51-.12.42 9.07 2.5zm2.18-.74-.8 2.93-12.84-3.52.8-2.94zm3.77-3.62-.36 1.32-7.97-2.19-.25.87 7.09 1.96-.39 1.34-15.93-4.37.38-1.37 6.85 1.9.25-.87-8.07-2.22.37-1.32 8.05 2.21.34-1.2 2.03.83q.3.15.24.33-.05.2-.5.25l-.1.35zm-18.83 4.93-.68 2.45-1.82-.49 1.09-3.95 18.21 5.02-1.05 3.82-1.82-.5.65-2.36zm14.02 4.4-.3 1.06-2.29-.62 1.5 3.42-1.54.09-.6-1.32-3.73-.86-.4 1.33 6.27 1.71-.36 1.27-6.26-1.72-.27.95 8.2 2.25-.37 1.34-18.11-4.98.36-1.33 7.98 2.18.26-.96-6.08-1.65.38-1.36 6.07 1.67.28-1-4.94-.92q-.13.3-.3.25-.19-.05-.21-.75l-.02-1.34 2.98.67.96-.96-3.17-.86.32-1.23zm44.36 22.77-12.87-12.08 1.3-1.38 5.57 5.23 2.48-2.64 1.43 1.79q.25.34.1.53-.2.2-.76.07l-1.66 1.75 5.7 5.33zm-15.24.27-1.98-1.06a34 34 0 0 0 4.13-7.81l2.2.9a48 48 0 0 1-4.27 7.87zm-8.16-2.66 1.4-1.5 7.48 7.02a43 43 0 0 0 9.62-6.06l1.22 1.73q.4.61.2.8-.15.21-.78 0a54 54 0 0 1-8.56 5.13l5.25 4.91-1.43 1.5zm35.3 29.61.88 2.12 1.8-.74-.86-2.13zm-2.05-1.01 4.47-1.82 2.15 5.23-4.47 1.83zm10.41 9-1.58-3.84q-1.33.55-2.78 1.42-.95.59-2.36 1.6 2.16-.06 4.76-.32l.05 1.64q-.06.5-.3.6-.2.07-.5-.34a27 27 0 0 1-5.65.05q-.43.26-.66.96l-.04.1q.15.4 2.13.29l.06.14-.7 1.46-.09.02.04.06q-.63.02-1.3-.03-.67-.04-1.27-.14-.57-.21-.78-.77a1 1 0 0 1-.13-.55 3.4 3.4 0 0 1 .97-2.1 11 11 0 0 1-2.79-1.45l-.01-.08v-.08q.39-.8.57-1.58l.2-.01q.62.47 1.4.89t1.71.8a34 34 0 0 1 3.17-2.32q1.8-1.15 3.63-1.88l-2.64-6.43 1.45-.58 2.6 6.36 1.85-.76.42 1.41q.1.63-.18.74-.17.07-.58-.1l-.84.35.7 1.73q.23-.25.46-.64.25-.37.43-.72l1.07.74q-.27.78-.56 1.3-.29.48-.74.88l.24.61zm-10.3-2.56-2.96-4.22q-.75-.11-.84-.39-.1-.23.4-.66l1.32-.77 3.37 5.68zm-5.59-5.29 5.4 13.17 14.48-5.95L222.3 79zm-2.3.95-.78-1.88 18.38-7.55 6.9 16.83-18.3 7.52-.73-1.8.68-.27-5.4-13.15zm21.64 69.77 1.83.51q1.35.65 1.21 1.9l-.53 1.88-.07.16-.12.06-1.55.15q-.1-.05-.17-.25l.45-1.63.06-.05q.04-.16-.06-.33-.1-.16-.36-.23l-.94-.28-.36 3.35q.33.48.26.72-.04.17-.4.21l-1.77-.16.74-4.54-1.67-.48.07-.1q.02-.09-.03-.43l-.74-1.58-1.62 5.73-1.67-.49 2.22-7.86q.61-.69 1.24-.5.28.06.53.34l1.44 3.35.46.12.45-4.07 1.44.77zm-7.84-11.94-.73 2.55 1.37 1.12.15-.8q4.9.76 6.85.57-2.15-1.2-3.98-2.1-1.83-.82-3.66-1.34m-2.49 12.43 1.25.34 1.12-3.95-1.26-.36zm-2.2 1.45 2.16-7.66 4.55 1.28-2.18 7.68zm5.23-15.8q6.03 2.25 9.02 4.4 1.05-.4 2.1-1.08 1.08-.67 2.2-1.68l.14-.04 1.05 1.5-.06.17q-1.05.92-2.08 1.61-1.05.7-2.12 1.17a21 21 0 0 1 1.97 5.39l-.12.13-1.6.86-.03.01-.06-.07a13.5 13.5 0 0 0-2.02-5.28q-2.9.45-7.2-.3l.42.39-1.26 1.5a33 33 0 0 0-7.36-5.23l1.13-1.72q.26-.26.49-.2.2.06.25.6l2.25 1.3 1.55-5.52 1.78.5zm-8.8 11.33-.14-.05.73-1.8q.19-.41.42-.34.15.04.24.23.1.2.14.38l1.2.35 1.05-3.75 1.58.44-2.81 9.92-1.58-.44 1.24-4.36zm4.13 21.6-2.45 3.72 3.97 2.6 2.45-3.71zm3.03 7.33.96.61-1.11 1.68-7.96-5.2 4.64-7.09 7.96 5.21-1.1 1.67-.94-.61zm-8.72 1.34-2.41 3.68 3.97 2.61 2.4-3.68zm3.07 7.29.94.62-1.06 1.6-7.96-5.2 4.55-6.97 7.97 5.24-1.08 1.65-.95-.62zm-7.55-18.55-4.22 6.44 3.53 2.32 4.24-6.44zm.7 9.8.78.51-1.07 1.67-7.25-4.77 6.47-9.86 7.24 4.74-1.1 1.7-.8-.53zm-18.56 21.08-1.29 1.03.8 1.03 1.3-1.02zm-2.2-10.81 1.54-.8q.34-.16.42-.06l.03.18a1 1 0 0 1-.1.34l2.45 3.13 2.63-2.07 3 3.85q.5.62 1 1.36l1.6 2.2q.26.35 2.02 3.14.6 1.8.06 2.78l-1.06.8q-.3.25-.61.04l-.85-.61-.24-.12q-.16-.2.27-.52l.56-.44q.38-.45 0-1.52-1.51-2.37-1.9-2.92-.4-.57-1.02-1.38-.77-.97-1.94-2.56-1.16-1.58-1.34-1.78l-1.23.96a42 42 0 0 1 2.45 3.4q.45.63.89 1.37.41.75.97 1.86a38 38 0 0 1 2.24 5.35q-.3.13-.49.17-.2.04-.27 0l-.41.15q-.23.1-.43-.17-.15-.16-.28-.5l-.15-.41-.06-.33a49 49 0 0 0-2.9-5.78l-1.13-1.54-1.77-2.5-1.63 1.26-.94-1.2 1.63-1.27zm.67 8.87-1.29 1 .83 1.07 1.3-1.03zm-1.14 4.03-1.2.95.8 1.03 1.2-.94zm-1.52-1.95-1.2.95.83 1.04 1.21-.92zm.05-2.9-1.64 1.3.67.83 1.64-1.28zm-.82-1.05-.75-.96 1.53-.72q.24-.08.38.05l-.09.33.22.3 1.9-1.49.84 1.06-1.98 1.54.66.84 1.34-1.04 3.88 4.95-2.63 2.05.62.8 3.33-2.6 2.9 3.7q.98 1.58.18 2.45l-1.2.94q-.33.27-.58.1l-.94-.43-.15-.13q-.12-.13.22-.38l.91-.73q.43-.31.03-1.16l-1.74-2.2-2.05 1.58.9 1.17.48-.72-.45-.07.33-1.2 2.2 1.1a6 6 0 0 1-.36 1.1h-.16l.03.04-.64-.37-2.24 3.26q.07.44-.1.57-.12.1-.4-.07l-1.07-.68 1.27-1.55-1.17-1.49-1.85 1.46 3.16 4.05-1.35 1.04-4.07-5.2 3.2-2.5-.61-.8-2.6 2.03-3.89-4.97 1.2-.93-.66-.84-1.68 1.31-.83-1.04 1.68-1.33-.74-.95 1.36-.76q.27-.06.4.08.1.15-.03.4l.22.28zm-5.63 2.48 4.85 6.2 3.02 4.25q.87 1.47 1.31 2.57.44 1.12.6 2.15.05.12.03.17l-.03.12-.08-.01-.66-.11-.63-.15a.7.7 0 0 1-.39-.23l-.1-.31q-.3-1.29-1.4-3.24-.59-1.06-1.26-2.05t-1.65-2.24l-5.68-7.27 9.23-7.2.86 1.07zm-17.69 16.74-1.7-.62-1.07 1.56zm-2.42-6.41 2.04.7-.45 1.31-2.21-.75-1.37 2.12-1.27-.4 1.27-2.07-1.64-.38-.5.07.4-1.5 2.33.56.57-1.64 1.5.48zm2.87 16.68q.38-.15.24-.6l-.47-1.33-8.26 2.85-.63-1.84 8.27-2.87-.38-1.08 1.12-.09 1.12-1.73-6.77 2.33-.57-1.65 8.77-3.02q.8.31.98.85l.06.29q.05.12-.1.37l-2.15 3.02 7.5-2.58.64 1.85-7.66 2.63.67 1.97q.16.9-.49 1.75l-2.81.96-.54-.62a2 2 0 0 1-.4-.63q-.07-.16.1-.23zm-.14-10.38 3.97-1.39-.4-1.17-2.88.98-.5-1.4 2.9-.99-.42-1.18-2.74.96-.5-1.49 2.74-.95-.43-1.21-2.93 1.01-.5-1.45 4.8-1.66 2.72 7.92 1.52-.5 1.44 4.15-1.98.68-.9-2.58-14.67 5.03.9 2.6-2.12.74-1.43-4.17 1.68-.58-2.64-7.7 4.8-1.63.5 1.47-2.87.99.33.94 3-1.03.51 1.5-3 1.02.43 1.24 3-1.03.5 1.43-3.08 1.05.37 1.11 3.9-1.34-.51-.56 1.22-1.62-1.75-.43.47-1.23 1.9.36.98-1.72 1.17.64-.82 1.4 1.8.52zm-57.89 1.26q.15 2.43.1 4.12l-1.81-.08a18 18 0 0 0-.09-3.95zm-5.67-2.57q.5.53 1.06 1.27.55.67 1.07 1.36l-1.6.83-1.87-2.57zm8.4-3.26q.05.15.05.33l-.05.27q-.09.24-.45.09l-.24-.14-.25-.19a58 58 0 0 1-11.8-3.48l-.27-.13-.1-.02-.06-.1-.17-1.77q.08-.15.16-.16l1.56.72a56 56 0 0 0 5.7 1.98q2.75.81 5.3 1.17zm-13.55 9.47c.25 1.2.71 2.21 1.38 3.12q1.78 0 3.96-.9zm.64-6.31q.2.45.14.6-.07.2-.61.1-.97.53-1.89.93-.91.39-1.89.63l-.76-1.76a14 14 0 0 0 4.23-1.92zm10.42 5.48 1.09-2.64-14.11-5.81-1.13 2.79-1.75-.72 1.76-4.3 3.74 1.54-.43-2.13 1.62-.02q.5 1.52.83 2.72l-.56.04 2.65 1.08q0-.54-.1-1.1-.15-.6-.35-1.18l1.66-.07a22 22 0 0 1 .68 2.88l-.32.12 2.64 1.08-.18-.5c1-.25 2.24-.78 3.7-1.68l.86 1.43q.12.3.07.45-.1.22-.68.03a15 15 0 0 1-2.05.98l3.86 1.6-1.72 4.14zm-7.88-5.4q.37.26.29.43-.07.2-.57.25l-.62 1.46-.03.07q-.24.55.5.85l3.3 1.36q.53.27 2.06-.88l.15.06q.16.53.67 1.12l.03.2v.18q-1.97 1.4-2.98 1.1l-3.85-1.6-1.13.44 6.4 2.62q.36.39.47.72.1.4-.03.69a15 15 0 0 1-4.89 1.9q1.56 1.04 2.83 1.71 1.28.64 2.69 1.24l.01.15-.75.66q-.48.43-.6.56a24 24 0 0 1-3.48-1.82q-1.66-1.05-3.29-2.4-1.37-.07-2.97-.4-1.58-.3-3.46-.84l-.2-.12-.34-1.57-.03-.1.12-.13q1.22.53 2.58.83 1.37.29 3.13.52a14 14 0 0 1-.7-1.65q-.3-.81-.48-1.59-1.66.2-2.92.2l-.13-.03-.07-.04-.7-1.59-.02-.08.08-.08a22 22 0 0 0 6.07-.98q-.27-.36-.05-1.04l1.4-3.42zm-33.41-15.65 1.77 1.5 1.27-1.53-1.77-1.48zm11.13 3.2-3.18-2.67a21 21 0 0 0-1.8 2.54q-.59.96-1.34 2.51 1.88-1.03 4.05-2.47l.82 1.4q.17.49 0 .66-.12.18-.6-.05-1.23.83-2.44 1.49-1.18.65-2.53 1.19-.25.42-.16 1.16l.02.11q.34.26 2.02-.75l.13.1.05 1.6-.06.06.06.06-1.17.57q-.6.26-1.19.47a1.3 1.3 0 0 1-1.06-.31 2 2 0 0 1-.36-.45q-.45-1.1-.13-2.29-1.74.22-3.13 0-.03 0-.06-.06l-.02-.06a8 8 0 0 0-.22-1.68l.17-.09q.77.13 1.65.13.88.02 1.87-.07a39 39 0 0 1 1.74-3.54 24 24 0 0 1 2.33-3.36l-5.3-4.44 1-1.2 5.26 4.4 1.27-1.53 1.04 1.08q.37.49.18.73-.12.13-.57.16l-.58.7 1.45 1.2q.06-.3.11-.77c.03-.27.04-.58.02-.84l1.32.17q.1.81.08 1.4-.02.56-.25 1.14l.5.4zm-13.4-3.13 3.09-3.7 4.35 3.63-3.1 3.71zm3.1 5.64-4.6-2.35q-.69.25-.93.06-.18-.17.05-.8l.81-1.28 5.64 3.45zm-7.4-2.07 10.89 9.14 10.05-12-10.9-9.14zm-1.62 1.92-1.56-1.31 12.77-15.23L77.2 202l-12.7 15.18-1.48-1.25.47-.57-10.9-9.12zm.76-28.02q-.05.15-.17.28-.12.15-.19.19-.23.13-.4-.2l-.11-.26-.09-.3a58 58 0 0 1-7.27-9.94l-.13-.26-.05-.06v-.12l.93-1.52q.16-.05.22-.03l.82 1.52a54 54 0 0 0 3.31 5.03 43 43 0 0 0 3.54 4.15zm-5.7 2.98a48 48 0 0 1-2.44 3.33l-1.37-1.18q1.31-1.43 2.33-3.18zm-2.96-5.51q.09.74.1 1.67v1.72l-1.76-.28.06-3.2zm1.45 7.88 2.46-1.44-7.68-13.15-2.6 1.5-.95-1.62 4-2.34 2.05 3.5.94-1.97 1.3.97q-.52 1.5-1 2.67l-.45-.32 1.44 2.46q.32-.4.58-.93.25-.55.45-1.14l1.35.93a20 20 0 0 1-1.2 2.7l-.32-.09 1.45 2.46.14-.52q1.41.66 3.95.94l-.18 1.65q-.08.3-.2.4-.21.1-.57-.39l-1.18-.2a5 5 0 0 1-1.04-.28l2.1 3.62-3.88 2.24zm-4.95-10.67c-.1.3-.18.52-.28.56q-.16.1-.54-.3-1.08-.15-2.06-.41-.98-.23-1.88-.63l.46-1.88q2.04.89 4.54 1.06zm-4.36 4.61q-.75 1.65-.78 3.3 1.41 1.11 3.7 1.7zm6.31-3.02q.15.45-.02.54t-.6-.17l-1.4.81h-.06q-.51.34-.12 1l1.8 3.1q.26.51 2.17.55l.08.12a3 3 0 0 0-.14 1.3q-.04.1-.1.18l-.11.14q-2.41-.07-3.03-.94l-2.1-3.59-1.14-.34 3.48 5.97q.06.52-.08.85a1 1 0 0 1-.43.53q-3.02-.4-5.03-1.47.6 1.77 1.21 3.09.63 1.3 1.37 2.6l-.08.15q-.35 0-.98.06l-.81.07a24 24 0 0 1-1.69-3.54 31 31 0 0 1-1.14-3.9q-1.05-.93-2.12-2.11a49 49 0 0 1-2.25-2.79l-.05-.23.67-1.44.04-.09.16-.02q.66 1.13 1.57 2.21.88 1.05 2.15 2.3a18 18 0 0 1 1.02-3.28 24 24 0 0 1-2.45-1.61l-.07-.1-.02-.07.38-1.7.06-.08h.1a22 22 0 0 0 5.42 2.9q0-.46.58-.85l3.2-1.88zm-2.7-26.68q0 .6-.23.65-.25.07-.64-.45l-.76.18a20 20 0 0 0-8.42 4 21 21 0 0 0-5.19 8.57l-.11.08-.14-.01a.2.2 0 0 1-.12-.05 10 10 0 0 0-1.77-1.46l-.07-.13q-.03-.11.07-.27 1.66-3.8 4.6-7.12 1.47-1.48 3.34-2.8a17 17 0 0 1-6.04-1.35q-3.83-2.32-5.52-4.3l-.07-.34q.66-1.13.86-2.06l.14-.1.2.08a14 14 0 0 0 3.02 3.08q1.81 1.32 4.32 2.38 2.19.52 5.3.35a38 38 0 0 0 7.12-1.1zm188.14-22.58a2.84 2.84 0 0 1-5.67 0 2.83 2.83 0 0 1 5.67 0m-198.03.16a2.84 2.84 0 1 1-5.67-.01 2.84 2.84 0 0 1 5.67 0m98.93 99.09a2.84 2.84 0 1 1-5.68 0 2.84 2.84 0 0 1 5.68 0' style='fill:%23000;fill-opacity:1;fill-rule:nonzero;stroke:none' transform='scale(.59524)'/%3E%3Cpath d='M125.38 6c-.38.33-.15.53-.45.95-.32.3-.7.34-1.05.04-.34-.4-.34-1.13.23-1.81a2.2 2.2 0 0 1 2.62-.52c1.02.52 1.5 2.09.77 3.47-.66 1.05-2.1 1.92-4.1 1.4-1.88-.46-2.9-2.61-1.77-4.98a6.1 6.1 0 0 1 4.94-2.95c1.77-.1 3.34.01 5.01 1.37a4.2 4.2 0 0 1 3.92-.92c.41.1.32.5.1.53-.63.1-2.64.53-2.85 3.6-.28 3.41-1.64 5.96-3.29 6.88l-3.3-.09c1.32-.27 4.68-2.4 4.77-5.93a4.2 4.2 0 0 0-1.54-3.43 5.25 5.25 0 0 1-.5 6.66c-1.8 1.77-5 3.1-9.67.53a3.8 3.8 0 0 1-3.8.91c-.28-.09-.4-.46 0-.57.64-.24 2.69-.81 2.79-3.55.07-2.86.94-5.11 3.28-6.88l3.3.1c-.85.32-4.5 1.5-4.75 5.97-.06 2.24 1.6 3.54 3.37 3.79 4.56.58 6.15-3 4.91-5.58-.66-1.16-2.01-1.49-3.34-1.2s-2.24 1.36-2.26 2.58c.06 1.2.73 1.7 1.55 1.81 1.35.07 1.99-.52 2.12-1.48.04-.73-.52-.99-1-.7' style='fill:%23b39c1c;fill-opacity:1;fill-rule:nonzero;stroke:none' transform='scale(.59524)'/%3E%3Cpath d='M142.33 8.92c.44-.24.23-.5.58-.86q.56-.38 1.06.1c.27.4.17 1.17-.47 1.76-.61.49-1.5.87-2.68.18-.93-.64-1.22-2.26-.3-3.52.77-.99 2.34-1.65 4.24-.9 1.82.74 2.54 3 1.11 5.2a6.1 6.1 0 0 1-5.28 2.27c-1.78-.14-3.32-.44-4.8-2-1.16.8-2.55.93-3.99.4-.4-.2-.26-.54-.04-.57.65 0 2.69-.16 3.3-3.17.7-3.36 2.4-5.72 4.16-6.4 0 0 1.6.25 3.26.54-1.34.08-4.96 1.75-5.5 5.22a4.2 4.2 0 0 0 1.07 3.63 5.3 5.3 0 0 1 1.37-6.56c2-1.5 5.37-2.4 9.66.74a3.8 3.8 0 0 1 3.87-.4c.28.13.34.5-.06.56-.66.16-2.78.45-3.23 3.16-.45 2.82-1.6 4.93-4.16 6.38-.44-.06-3.25-.53-3.25-.53.88-.17 4.68-.9 5.5-5.3.34-2.21-1.13-3.7-2.85-4.17-4.47-1.18-6.5 2.16-5.6 4.89.5 1.23 1.79 1.73 3.13 1.63 1.37-.16 2.41-1.06 2.6-2.29.1-1.18-.5-1.77-1.3-1.98-1.36-.24-2.06.24-2.3 1.17-.14.72.38 1.06.9.82' style='fill:%23b39c1c;fill-opacity:1;fill-rule:nonzero;stroke:none' transform='scale(.59524)'/%3E%3Cpath d='M159.17 10.67c-.47.2-.3.48-.7.78q-.62.3-1.03-.26c-.2-.45 0-1.17.7-1.67.7-.4 1.62-.64 2.68.22.85.78.88 2.44-.2 3.54-.93.83-2.55 1.28-4.34.25-1.68-.99-2.06-3.33-.33-5.28a6 6 0 0 1 5.56-1.5c1.73.39 3.22.94 4.44 2.7a4.1 4.1 0 0 1 4 .18c.37.24.2.57-.04.55-.63-.08-2.66-.22-3.71 2.68-1.2 3.2-3.22 5.28-5.07 5.71l-3.14-1c1.34.1 5.17-1.03 6.22-4.37.24-.97.47-2.32-.54-3.75a5.26 5.26 0 0 1-2.31 6.28c-2.22 1.2-5.66 1.6-9.44-2.13a3.9 3.9 0 0 1-3.9-.2c-.25-.16-.27-.53.14-.54.7-.05 2.82-.03 3.65-2.64.88-2.72 2.33-4.65 5.06-5.73l3.14 1.02c-.89.06-4.74.22-6.2 4.42-.67 2.15.56 3.86 2.2 4.57 4.22 1.82 6.73-1.18 6.25-4-.3-1.32-1.52-2-2.87-2.08a2.8 2.8 0 0 0-2.9 1.86c-.27 1.17.24 1.84 1 2.16 1.29.45 2.06.08 2.44-.82.25-.69-.23-1.1-.76-.95' style='fill:%23b39c1c;fill-opacity:1;fill-rule:nonzero;stroke:none' transform='scale(.59524)'/%3E%3Cpath d='M174.62 18.21c.48-.14.36-.41.79-.67.41-.14.77-.03.98.4.16.46-.14 1.15-.92 1.56-.74.28-1.68.41-2.64-.57-.72-.9-.54-2.53.69-3.5 1.02-.7 2.68-.92 4.33.33 1.53 1.2 1.6 3.59-.37 5.3a6.1 6.1 0 0 1-5.72.74c-1.65-.62-3.06-1.35-4.05-3.27-1.34.5-2.7.19-3.93-.69-.34-.3-.12-.6.1-.56.62.18 2.64.57 4.05-2.13 1.6-3.04 3.88-4.84 5.76-5.03 0 0 1.45.7 2.99 1.42-1.3-.3-5.26.35-6.74 3.53-.37.9-.78 2.2.04 3.77a5.25 5.25 0 0 1 3.12-5.92c2.36-.9 5.83-.84 9.08 3.35a3.8 3.8 0 0 1 3.82.7c.24.18.2.56-.2.52-.7-.06-2.8-.34-3.97 2.14-1.2 2.6-2.9 4.3-5.76 5-.4-.2-2.98-1.4-2.98-1.4.9.06 4.74.4 6.74-3.6.95-2.04-.06-3.88-1.58-4.78-3.96-2.37-6.84.28-6.71 3.14.12 1.3 1.23 2.17 2.55 2.44a2.8 2.8 0 0 0 3.12-1.48c.42-1.11 0-1.86-.7-2.29-1.22-.59-2.03-.32-2.53.5-.34.68.07 1.13.64 1.05m15.62 6.57c-.5.04-.42.36-.88.53q-.68.12-.91-.53c-.07-.5.32-1.12 1.15-1.4a2.2 2.2 0 0 1 2.5.98c.58.97.15 2.59-1.2 3.32-1.11.55-2.82.5-4.24-.98-1.33-1.44-1.03-3.8 1.21-5.17 1.54-.85 3.61-.95 5.75.15 1.54.88 2.81 1.83 3.48 3.87 1.4-.26 2.7.24 3.8 1.3.27.35 0 .61-.21.53-.6-.26-2.5-.97-4.32 1.5-2.08 2.74-4.6 4.15-6.49 4.03 0 0-1.33-.9-2.73-1.88 1.26.52 5.24.53 7.2-2.4a4.2 4.2 0 0 0 .56-3.75 5.25 5.25 0 0 1-4.01 5.37c-2.45.52-5.88-.09-8.43-4.76a3.8 3.8 0 0 1-3.7-1.28c-.18-.22-.07-.58.3-.5.68.2 2.7.8 4.27-1.48 1.6-2.36 3.54-3.78 6.48-4.02.36.26 2.72 1.85 2.72 1.85-.88-.2-4.63-1.13-7.23 2.5-1.25 1.85-.55 3.83.82 4.98 3.53 2.95 6.78.8 7.12-2.05.09-1.33-.87-2.32-2.15-2.8-1.28-.46-2.61-.07-3.3.95-.6 1.05-.3 1.83.34 2.36 1.11.8 1.95.64 2.56-.08.45-.62.1-1.13-.46-1.14' style='fill:%23b39c1c;fill-opacity:1;fill-rule:nonzero;stroke:none' transform='scale(.59524)'/%3E%3Cpath d='M202.95 36.36c.5 0 .46-.3.94-.41q.72-.05.85.66c0 .49-.47 1.06-1.33 1.21-.79.07-1.74-.06-2.37-1.3-.43-1.04.2-2.57 1.66-3.13 1.18-.4 2.84-.12 4.04 1.55 1.13 1.59.53 3.9-1.86 4.96a6.1 6.1 0 0 1-5.68-.93c-1.4-1.08-2.55-2.16-2.96-4.27a4.2 4.2 0 0 1-3.57-1.8c-.24-.37.06-.6.26-.49.54.33 2.36 1.28 4.5-.9 2.4-2.44 5.1-3.52 6.96-3.17l2.45 2.21c-1.18-.65-5.13-1.19-7.46 1.45a4.2 4.2 0 0 0-1.05 3.62 5.3 5.3 0 0 1 4.7-4.78c2.5-.18 5.8.87 7.72 5.82a3.8 3.8 0 0 1 3.5 1.75c.14.28 0 .6-.37.45-.64-.24-2.57-1.11-4.42.92-1.89 2.12-4.01 3.3-6.94 3.15l-2.45-2.2c.84.32 4.42 1.73 7.48-1.5 1.49-1.7 1.05-3.76-.16-5.07-3.12-3.4-6.63-1.68-7.34 1.1-.24 1.3.58 2.42 1.76 3.07 1.22.6 2.6.4 3.41-.52.73-.96.54-1.77 0-2.39-1.02-.93-1.88-.88-2.58-.25-.51.56-.24 1.1.31 1.2' style='fill:%23b39c1c;fill-opacity:1;fill-rule:nonzero;stroke:none' transform='scale(.59524)'/%3E%3Cpath d='M216.2 46.88c-.5-.08-.5.23-1 .27q-.7-.07-.74-.75c.07-.5.63-1 1.5-1 .79.03 1.7.3 2.15 1.6.28 1.1-.57 2.53-2.09 2.86-1.23.23-2.83-.29-3.79-2.12-.88-1.74.05-3.92 2.57-4.63a6.1 6.1 0 0 1 5.49 1.73c1.24 1.27 2.2 2.53 2.28 4.68a4.2 4.2 0 0 1 3.28 2.3c.19.4-.15.6-.33.45-.48-.4-2.14-1.62-4.57.24-2.74 2.06-5.56 2.72-7.34 2.11l-2.11-2.54c1.06.8 4.9 1.9 7.59-.36a4.2 4.2 0 0 0 1.57-3.43 5.25 5.25 0 0 1-5.34 4.04c-2.5-.17-5.63-1.71-6.8-6.88a3.8 3.8 0 0 1-3.18-2.26c-.12-.26.06-.58.42-.37.58.34 2.38 1.5 4.49-.25 2.2-1.84 4.46-2.69 7.34-2.11l2.1 2.53c-.8-.42-4.12-2.36-7.62.4-1.72 1.45-1.6 3.55-.59 5.03 2.59 3.81 6.32 2.62 7.42-.01.43-1.27-.21-2.49-1.29-3.3-1.11-.78-2.51-.78-3.45.02-.86.83-.8 1.67-.34 2.36.86 1.06 1.72 1.16 2.5.62.6-.47.42-1.05-.13-1.23' style='fill:%23b39c1c;fill-opacity:1;fill-rule:nonzero;stroke:none' transform='scale(.59524)'/%3E%3Cpath d='M225.12 61.62c.49.13.52-.17 1.02-.16q.68.17.63.87c-.12.47-.75.87-1.61.8-.79-.15-1.65-.53-1.92-1.9-.13-1.11.9-2.41 2.44-2.56 1.25-.05 2.78.68 3.47 2.62.65 1.83-.55 3.87-3.14 4.24a6 6 0 0 1-5.21-2.44c-1.07-1.42-1.87-2.79-1.66-4.93-1.4-.3-2.39-1.29-2.96-2.71-.13-.42.23-.56.4-.4.44.47 1.9 1.88 4.56.36 3-1.7 5.87-2 7.57-1.12 0 0 .84 1.37 1.76 2.79-.96-.94-4.61-2.54-7.58-.64a4.2 4.2 0 0 0-2 3.19 5.24 5.24 0 0 1 5.8-3.3c2.48.49 5.37 2.42 5.85 7.7a3.8 3.8 0 0 1 2.87 2.66c.08.28-.15.57-.46.33-.55-.42-2.18-1.79-4.5-.35-2.41 1.54-4.76 2.07-7.54 1.13-.24-.4-1.78-2.78-1.78-2.78.74.51 3.8 2.87 7.62.59 1.89-1.22 2.05-3.3 1.25-4.9-2.07-4.12-5.91-3.42-7.35-.97-.6 1.2-.12 2.5.84 3.44 1.01.92 2.38 1.1 3.42.44.96-.72 1.02-1.56.63-2.3-.7-1.16-1.53-1.36-2.38-.94-.67.37-.56.98-.04 1.24' style='fill:%23b39c1c;fill-opacity:1;fill-rule:nonzero;stroke:none' transform='scale(.59524)'/%3E%3Cpath d='M234.89 75.5c-.46-.2-.55.08-1.04-.02q-.65-.25-.48-.95c.2-.44.88-.75 1.74-.53.74.27 1.53.8 1.57 2.2-.06 1.1-1.3 2.21-2.83 2.1-1.25-.14-2.62-1.1-3.01-3.1-.34-1.94 1.2-3.76 3.8-3.7a6 6 0 0 1 4.75 3.25c.82 1.57 1.38 3.06.84 5.14a4.1 4.1 0 0 1 2.45 3.16c.06.45-.3.5-.45.31-.35-.52-1.55-2.16-4.44-1.08-3.21 1.17-6.1.98-7.63-.13l-1.28-3.06c.77 1.1 4.12 3.27 7.37 1.89a4.3 4.3 0 0 0 2.5-2.85 5.25 5.25 0 0 1-6.3 2.33c-2.35-.9-4.88-3.28-4.5-8.57a3.8 3.8 0 0 1-2.39-3.08c-.03-.29.24-.54.52-.24.47.5 1.84 2.13 4.38 1.07 2.62-1.12 5.04-1.26 7.63.12l1.27 3.04c-.64-.66-3.25-3.47-7.41-1.85-2.06.88-2.56 2.94-2.03 4.65 1.37 4.4 5.26 4.35 7.11 2.14.78-1.06.51-2.43-.28-3.51-.84-1.09-2.18-1.48-3.3-1-1.07.54-1.27 1.38-1 2.16.5 1.27 1.3 1.61 2.2 1.33.7-.26.7-.9.24-1.22' style='fill:%23b39c1c;fill-opacity:1;fill-rule:nonzero;stroke:none' transform='scale(.59524)'/%3E%3Cpath d='M239.27 92.14c.42.29.54-.01 1 .17q.6.34.36 1c-.26.42-.98.63-1.77.3a2.2 2.2 0 0 1-1.29-2.36c.2-1.1 1.57-2.05 3.08-1.75 1.21.32 2.47 1.44 2.58 3.5.08 1.96-1.68 3.56-4.26 3.18a6.2 6.2 0 0 1-4.28-3.86c-.6-1.69-.96-3.22-.15-5.2a4.2 4.2 0 0 1-2.02-3.47c-.01-.45.36-.45.48-.27.27.58 1.27 2.34 4.27 1.66 3.34-.75 6.18-.16 7.54 1.14l.87 3.19c-.64-1.18-3.66-3.77-7.05-2.83a4.2 4.2 0 0 0-2.84 2.48 5.26 5.26 0 0 1 6.53-1.47c2.2 1.2 4.41 3.89 3.34 9.1a3.8 3.8 0 0 1 1.96 3.37c0 .28-.3.5-.54.15-.4-.55-1.54-2.35-4.2-1.62-2.75.77-5.16.6-7.54-1.13l-.88-3.18c.55.71 2.78 3.87 7.11 2.78 2.16-.59 2.93-2.56 2.62-4.3-.78-4.55-4.65-5.02-6.76-3.06-.91.95-.84 2.33-.19 3.52.7 1.18 1.96 1.74 3.15 1.4 1.12-.39 1.42-1.2 1.27-2-.34-1.3-1.07-1.77-2-1.6-.73.17-.81.79-.39 1.16' style='fill:%23b39c1c;fill-opacity:1;fill-rule:nonzero;stroke:none' transform='scale(.59524)'/%3E%3Cpath d='M244.67 108.18c-.38-.33-.56-.08-1-.31q-.53-.43-.2-1.05c.33-.4 1.08-.5 1.82-.04.64.47 1.25 1.19.92 2.53-.36 1.07-1.84 1.8-3.31 1.27-1.15-.5-2.22-1.78-2.03-3.84.2-1.94 2.17-3.26 4.67-2.5a6.1 6.1 0 0 1 3.67 4.45c.36 1.72.49 3.32-.6 5.17 1.1.87 1.59 2.2 1.49 3.7-.06.46-.45.41-.51.2-.2-.6-.93-2.52-3.99-2.28-3.4.25-6.14-.74-7.31-2.23l-.38-3.29c.46 1.28 3.07 4.28 6.56 3.84a4.2 4.2 0 0 0 3.18-2.03 5.2 5.2 0 0 1-6.67.51c-2.02-1.51-3.8-4.5-1.96-9.48a3.8 3.8 0 0 1-1.47-3.62c.06-.3.38-.47.56-.1.33.62 1.2 2.55 3.92 2.23 2.84-.35 5.18.18 7.29 2.22l.41 3.29c-.44-.8-2.2-4.25-6.63-3.82-2.22.28-3.26 2.12-3.23 3.9.1 4.6 3.88 5.63 6.23 4.02 1.06-.83 1.17-2.2.71-3.47a2.8 2.8 0 0 0-2.9-1.85c-1.18.22-1.57.96-1.55 1.79.15 1.36.8 1.92 1.75 1.89.75-.07.91-.69.56-1.1' style='fill:%23b39c1c;fill-opacity:1;fill-rule:nonzero;stroke:none' transform='scale(.59524)'/%3E%3Cpath d='M244.21 125.36c.33.4.54.17.95.44.3.34.35.7.05 1.06-.37.34-1.11.36-1.8-.2-.57-.52-1.07-1.34-.58-2.64.5-1.01 2.06-1.54 3.44-.8 1.08.63 1.97 2.06 1.52 4.07-.45 1.9-2.58 2.95-4.96 1.88a6.2 6.2 0 0 1-3.05-4.9c-.13-1.76-.04-3.36 1.28-5.06-.99-1-1.3-2.38-.99-3.87.11-.42.48-.33.54-.1.1.6.57 2.61 3.63 2.78 3.44.2 6 1.51 6.96 3.16l-.04 3.3c-.3-1.32-2.5-4.64-6-4.67-1 .04-2.34.23-3.43 1.6a5.2 5.2 0 0 1 6.68.39c1.79 1.76 3.19 4.95.72 9.65.97.9 1.32 2.34.95 3.77-.08.29-.42.4-.54.02-.24-.64-.86-2.67-3.61-2.73-2.85-.01-5.13-.83-6.94-3.14.02-.45.04-3.3.04-3.3.31.84 1.61 4.48 6.07 4.64 2.24.02 3.5-1.67 3.72-3.44.48-4.59-3.11-6.09-5.68-4.8-1.15.67-1.44 2.03-1.15 3.34.34 1.32 1.41 2.23 2.64 2.23 1.2-.08 1.69-.77 1.77-1.6.04-1.35-.54-2-1.5-2.1-.75-.02-.99.55-.69 1.02' style='fill:%23b39c1c;fill-opacity:1;fill-rule:nonzero;stroke:none' transform='scale(.59524)'/%3E%3Cpath d='M244.86 142.34c-.28-.43-.5-.23-.87-.58q-.4-.58.1-1.05c.43-.27 1.17-.17 1.77.49.48.62.85 1.48.16 2.67-.67.94-2.3 1.21-3.55.26-.97-.78-1.62-2.33-.84-4.24.75-1.82 3.01-2.5 5.19-1.05a6 6 0 0 1 2.23 5.29c-.14 1.78-.48 3.31-2.05 4.76.83 1.2.9 2.59.37 4-.17.4-.53.28-.57.04 0-.64-.14-2.67-3.13-3.32-3.36-.74-5.69-2.45-6.37-4.22l.56-3.25c.08 1.33 1.72 4.97 5.2 5.55.97.1 2.33.16 3.62-1.04a5.26 5.26 0 0 1-6.54-1.43c-1.49-2.04-2.34-5.4.84-9.65a3.8 3.8 0 0 1-.37-3.88c.14-.26.5-.33.57.06.12.68.4 2.8 3.12 3.27 2.8.47 4.92 1.64 6.34 4.2l-.56 3.26c-.18-.89-.87-4.68-5.24-5.54-2.22-.38-3.73 1.08-4.2 2.8-1.22 4.47 2.1 6.52 4.81 5.65 1.25-.5 1.76-1.78 1.67-3.13-.12-1.36-1.03-2.4-2.25-2.6-1.19-.1-1.79.48-2 1.27-.25 1.34.23 2.05 1.14 2.32.74.13 1.07-.39.85-.91' style='fill:%23b39c1c;fill-opacity:1;fill-rule:nonzero;stroke:none' transform='scale(.59524)'/%3E%3Cpath d='M239.58 158.79c.2.46.47.3.77.68.22.4.14.78-.24 1.04-.45.21-1.17.01-1.67-.7a2.2 2.2 0 0 1 .2-2.69c.77-.84 2.43-.89 3.55.2.85.91 1.28 2.55.27 4.34-.99 1.69-3.32 2.08-5.3.36a6.2 6.2 0 0 1-1.51-5.58c.39-1.7.92-3.2 2.67-4.44a4.2 4.2 0 0 1 .17-4.01c.24-.36.57-.2.56.05-.07.63-.2 2.66 2.67 3.7 3.23 1.19 5.3 3.19 5.76 5.03 0 0-.5 1.53-1 3.15.12-1.33-1.05-5.14-4.4-6.17a4.2 4.2 0 0 0-3.74.53 5.3 5.3 0 0 1 6.3 2.3c1.21 2.19 1.6 5.64-2.11 9.44a3.8 3.8 0 0 1-.15 3.89c-.18.24-.54.26-.56-.14-.04-.68-.04-2.82-2.66-3.64-2.72-.86-4.66-2.29-5.74-5.02l.99-3.16c.07.9.25 4.76 4.47 6.2 2.14.65 3.85-.58 4.53-2.22 1.82-4.26-1.2-6.73-4.02-6.25-1.3.3-1.98 1.53-2.06 2.88a2.8 2.8 0 0 0 1.88 2.9c1.17.25 1.84-.26 2.16-1 .42-1.3.05-2.07-.83-2.45-.7-.24-1.1.23-.96.78' style='fill:%23b39c1c;fill-opacity:1;fill-rule:nonzero;stroke:none' transform='scale(.59524)'/%3E%3Cpath d='M235.43 175.17c-.13-.5-.41-.36-.65-.8q-.24-.65.4-.98c.47-.13 1.16.16 1.53.97.3.72.41 1.66-.6 2.6-.88.7-2.52.52-3.46-.73-.7-1.03-.9-2.7.39-4.32 1.21-1.52 3.59-1.56 5.28.44a6.1 6.1 0 0 1 .66 5.72c-.65 1.66-1.39 3.04-3.31 4a4.2 4.2 0 0 1-.76 3.94c-.3.34-.6.1-.55-.12.18-.62.6-2.61-2.09-4.08-3.01-1.64-4.78-3.94-4.94-5.83l1.46-2.96c-.3 1.32.25 5.26 3.43 6.79.89.37 2.2.78 3.78 0a5.25 5.25 0 0 1-5.89-3.2c-.86-2.36-.75-5.84 3.48-9.02a3.9 3.9 0 0 1 .76-3.84c.2-.21.57-.16.51.24-.06.68-.38 2.77 2.1 3.99 2.56 1.24 4.26 2.97 4.92 5.8l-1.45 3c.06-.9.46-4.75-3.5-6.8-2-.98-3.88 0-4.81 1.53-2.42 3.91.19 6.83 3.04 6.76 1.34-.12 2.18-1.22 2.49-2.54.26-1.34-.33-2.6-1.44-3.13-1.11-.44-1.86-.04-2.28.66-.61 1.2-.36 2.04.46 2.53.65.36 1.1-.06 1.04-.62' style='fill:%23b39c1c;fill-opacity:1;fill-rule:nonzero;stroke:none' transform='scale(.59524)'/%3E%3Cpath d='M225.77 189.41c.06.5.36.4.54.87.1.44-.08.78-.53.94-.48.07-1.13-.33-1.4-1.16a2.2 2.2 0 0 1 .96-2.5c.97-.6 2.58-.2 3.33 1.19.57 1.1.52 2.79-.96 4.23-1.42 1.34-3.77 1.04-5.18-1.16a6.1 6.1 0 0 1 .12-5.76c.86-1.56 1.8-2.82 3.83-3.52a4.1 4.1 0 0 1 1.28-3.79c.33-.3.6-.04.52.2-.25.56-.95 2.5 1.54 4.32 2.75 2.03 4.17 4.54 4.08 6.43 0 0-.9 1.33-1.83 2.75.46-1.26.44-5.25-2.48-7.18a4.3 4.3 0 0 0-3.76-.54 5.3 5.3 0 0 1 5.4 3.98c.54 2.45-.04 5.88-4.68 8.48.3 1.3-.17 2.67-1.26 3.67-.24.2-.59.1-.5-.28.17-.68.77-2.72-1.5-4.25-2.38-1.58-3.83-3.51-4.1-6.43l1.84-2.75c-.19.87-1.1 4.62 2.54 7.2 1.88 1.23 3.87.52 4.98-.84 2.93-3.58.75-6.81-2.1-7.13-1.34-.06-2.32.92-2.79 2.18-.45 1.29-.04 2.62.98 3.29 1.06.6 1.84.3 2.36-.33.78-1.13.63-1.98-.1-2.6-.61-.4-1.13-.07-1.13.5m-8.71 14.65c0-.51-.3-.46-.41-.95q-.02-.7.67-.84c.5 0 1.07.49 1.2 1.35a2.2 2.2 0 0 1-1.32 2.35c-1.06.42-2.57-.25-3.12-1.7-.38-1.19-.08-2.85 1.6-4.05 1.62-1.09 3.89-.45 4.95 1.94.57 1.66.4 3.72-1 5.68-1.09 1.4-2.2 2.53-4.33 2.9a4.1 4.1 0 0 1-1.84 3.55c-.37.24-.6-.08-.49-.27.34-.53 1.32-2.33-.86-4.5-2.4-2.44-3.43-5.16-3.05-7l2.25-2.43c-.67 1.16-1.26 5.1 1.34 7.47.74.64 1.9 1.4 3.62 1.1a5.3 5.3 0 0 1-4.73-4.75c-.16-2.52.94-5.79 5.92-7.66a3.9 3.9 0 0 1 1.82-3.46c.26-.15.58 0 .43.38-.26.62-1.15 2.55.85 4.42 2.12 1.9 3.24 4.05 3.05 6.97l-2.23 2.45c.34-.85 1.8-4.41-1.42-7.5-1.66-1.52-3.73-1.12-5.05.07-3.43 3.08-1.76 6.6 1.01 7.36 1.3.26 2.42-.55 3.09-1.73a2.8 2.8 0 0 0-.47-3.42c-.96-.73-1.78-.55-2.4-.01-.93 1-.91 1.85-.27 2.57.54.53 1.1.26 1.2-.29' style='fill:%23b39c1c;fill-opacity:1;fill-rule:nonzero;stroke:none' transform='scale(.59524)'/%3E%3Cpath d='M203.76 214.96c-.07.5.23.5.28 1.02q-.07.67-.77.73c-.5-.07-1-.64-1.02-1.5.03-.78.31-1.7 1.62-2.14 1.1-.3 2.52.56 2.86 2.06.23 1.23-.28 2.85-2.12 3.8-1.72.9-3.9-.04-4.63-2.55a6.1 6.1 0 0 1 1.73-5.49c1.27-1.25 2.52-2.24 4.67-2.32a4.1 4.1 0 0 1 2.3-3.27c.39-.18.58.16.44.34-.4.5-1.62 2.13.26 4.56 2.07 2.75 2.73 5.55 2.11 7.34l-2.55 2.12c.82-1.07 1.92-4.9-.35-7.6-.68-.7-1.68-1.64-3.44-1.56a5.3 5.3 0 0 1 4.06 5.33c-.17 2.51-1.7 5.64-6.88 6.82a3.8 3.8 0 0 1-2.24 3.18c-.26.12-.59-.07-.4-.4.36-.6 1.5-2.4-.26-4.51-1.82-2.18-2.68-4.44-2.1-7.31l2.53-2.14c-.43.8-2.38 4.13.41 7.63 1.44 1.7 3.54 1.6 5.03.58 3.8-2.6 2.61-6.3-.03-7.41-1.26-.45-2.5.21-3.3 1.3-.8 1.11-.77 2.5.04 3.44.83.85 1.67.8 2.36.33 1.04-.86 1.14-1.72.6-2.5-.46-.6-1.04-.41-1.21.12' style='fill:%23b39c1c;fill-opacity:1;fill-rule:nonzero;stroke:none' transform='scale(.59524)'/%3E%3Cpath d='M191.43 226.56c.14-.5-.16-.54-.13-1.03.1-.42.4-.66.87-.62.48.14.89.77.8 1.64-.17.75-.58 1.63-1.93 1.88-1.13.11-2.4-.93-2.54-2.49-.04-1.23.71-2.75 2.65-3.43 1.86-.63 3.87.62 4.21 3.2a6.1 6.1 0 0 1-2.5 5.2c-1.43 1.04-2.82 1.81-4.95 1.59a4.1 4.1 0 0 1-2.77 2.9c-.42.12-.55-.22-.38-.4.46-.41 1.9-1.87.42-4.55-1.66-3.02-1.9-5.89-1.02-7.58l2.82-1.72c-.96.95-2.6 4.58-.75 7.56a4.2 4.2 0 0 0 3.16 2.07 5.3 5.3 0 0 1-3.23-5.88c.55-2.46 2.51-5.32 7.8-5.73a3.8 3.8 0 0 1 2.68-2.82c.29-.08.58.15.33.47-.43.54-1.82 2.14-.4 4.48 1.5 2.44 2 4.8 1.02 7.54-.38.26-2.82 1.75-2.82 1.75.54-.73 2.94-3.75.71-7.61-1.2-1.9-3.28-2.09-4.88-1.32-4.14 2.01-3.52 5.88-1.06 7.36 1.17.6 2.48.14 3.44-.8.95-1 1.13-2.38.48-3.42-.7-.98-1.54-1.03-2.27-.66-1.19.7-1.41 1.52-.98 2.38.37.65.99.55 1.22.04' style='fill:%23b39c1c;fill-opacity:1;fill-rule:nonzero;stroke:none' transform='scale(.59524)'/%3E%3Cpath d='M175.6 233.3c-.19.46.1.53 0 1.04q-.25.63-.94.5c-.46-.22-.78-.88-.57-1.74a2.2 2.2 0 0 1 2.15-1.62c1.13.06 2.27 1.24 2.2 2.8-.14 1.24-1.07 2.63-3.09 3.06-1.91.37-3.76-1.11-3.76-3.73a6.1 6.1 0 0 1 3.16-4.8c1.57-.86 3.03-1.43 5.13-.93a4.2 4.2 0 0 1 3.11-2.54c.44-.06.52.3.33.45-.52.35-2.13 1.61-1 4.48 1.24 3.2 1.1 6.08.02 7.62l-3.03 1.34c1.08-.8 3.19-4.2 1.74-7.4a4.2 4.2 0 0 0-2.87-2.44 5.3 5.3 0 0 1 2.44 6.25c-.87 2.35-3.17 4.93-8.49 4.65a3.8 3.8 0 0 1-3.04 2.44c-.29.06-.54-.23-.25-.5.5-.48 2.09-1.9.98-4.4-1.18-2.6-1.36-5.01-.02-7.61.41-.2 3.02-1.35 3.02-1.35-.63.65-3.4 3.31-1.7 7.45.93 2.03 2.98 2.5 4.68 1.93 4.38-1.44 4.26-5.34 2-7.14-1.08-.76-2.44-.47-3.51.35-1.08.86-1.43 2.2-.92 3.31.56 1.07 1.39 1.23 2.18.98 1.25-.55 1.58-1.35 1.27-2.25-.28-.69-.91-.68-1.21-.2' style='fill:%23b39c1c;fill-opacity:1;fill-rule:nonzero;stroke:none' transform='scale(.59524)'/%3E%3Cpath d='M160.43 240.93c.28-.4 0-.54.17-1.02.22-.38.58-.52 1-.34.43.27.65.98.3 1.8-.38.68-1 1.4-2.38 1.25-1.11-.21-2.04-1.57-1.72-3.1.33-1.2 1.47-2.45 3.53-2.54 1.94-.07 3.53 1.7 3.12 4.27a6.1 6.1 0 0 1-3.9 4.25c-1.66.6-3.21.95-5.2.12a4.2 4.2 0 0 1-3.47 2c-.44 0-.45-.38-.26-.5.57-.26 2.37-1.24 1.7-4.23-.71-3.37-.13-6.2 1.2-7.57l3.19-.83c-1.19.63-3.8 3.63-2.9 7.03.3.94.85 2.2 2.48 2.88a5.3 5.3 0 0 1-1.43-6.55c1.21-2.2 3.92-4.39 9.12-3.26a3.8 3.8 0 0 1 3.38-1.95c.28 0 .5.3.16.54-.55.4-2.35 1.55-1.65 4.2.73 2.75.54 5.16-1.19 7.51-.44.14-3.19.86-3.19.86.72-.54 3.89-2.73 2.85-7.09-.58-2.16-2.55-2.93-4.3-2.66-4.55.75-5.04 4.64-3.13 6.74.96.94 2.34.86 3.54.23 1.19-.68 1.76-1.95 1.43-3.13-.4-1.15-1.18-1.44-1.99-1.3-1.34.32-1.78 1.04-1.62 2 .17.73.78.83 1.16.4' style='fill:%23b39c1c;fill-opacity:1;fill-rule:nonzero;stroke:none' transform='scale(.59524)'/%3E%3Cpath d='M143.35 242.92c-.33.39-.07.55-.31 1q-.42.54-1.03.2c-.4-.32-.51-1.07-.06-1.82a2.2 2.2 0 0 1 2.52-.93c1.08.36 1.82 1.84 1.3 3.29-.47 1.16-1.77 2.25-3.83 2.08-1.93-.19-3.27-2.17-2.54-4.67a6.1 6.1 0 0 1 4.42-3.7c1.74-.37 3.31-.5 5.17.57a4.3 4.3 0 0 1 3.7-1.53c.45.06.42.45.2.52-.61.19-2.52.93-2.25 4 .28 3.43-.67 6.15-2.17 7.33 0 0-1.6.18-3.28.41 1.28-.44 4.26-3.1 3.78-6.6a4.1 4.1 0 0 0-2.04-3.16 5.3 5.3 0 0 1 .55 6.7c-1.51 2-4.47 3.8-9.47 2.01a3.8 3.8 0 0 1-3.6 1.49c-.3-.06-.46-.38-.09-.56.59-.32 2.53-1.22 2.17-3.93-.36-2.83.14-5.2 2.18-7.33.43-.04 3.27-.41 3.27-.41-.8.44-4.21 2.22-3.75 6.66.29 2.21 2.13 3.24 3.92 3.2 4.61-.16 5.61-3.93 3.98-6.28-.84-1.05-2.22-1.16-3.48-.67-1.28.5-2.01 1.69-1.84 2.9.24 1.18 1 1.57 1.81 1.56 1.36-.17 1.9-.83 1.87-1.79-.08-.74-.67-.9-1.1-.54' style='fill:%23b39c1c;fill-opacity:1;fill-rule:nonzero;stroke:none' transform='scale(.59524)'/%3E%3Cpath d='M126.72 245.98c.39-.33.16-.54.44-.94q.51-.47 1.07-.06c.32.38.33 1.14-.21 1.82a2.2 2.2 0 0 1-2.64.55c-1.01-.5-1.53-2.09-.8-3.46.65-1.07 2.08-1.95 4.1-1.47 1.88.49 2.92 2.61 1.82 4.96a6.1 6.1 0 0 1-4.9 3.02c-1.79.1-3.36.03-5.04-1.31a4.2 4.2 0 0 1-3.89.95c-.42-.1-.35-.48-.12-.54.63-.1 2.62-.56 2.8-3.6.23-3.43 1.58-5.99 3.22-6.94 0 0 1.62.05 3.3.08-1.3.27-4.65 2.44-4.69 5.97.02.97.18 2.33 1.56 3.42a5.25 5.25 0 0 1 .44-6.68c1.77-1.79 4.96-3.13 9.64-.65a3.8 3.8 0 0 1 3.8-.91c.28.08.4.43.02.55-.65.24-2.7.84-2.77 3.59-.04 2.85-.88 5.11-3.2 6.92-.45-.02-3.3-.07-3.3-.07.84-.33 4.5-1.58 4.7-6.04.02-2.22-1.65-3.51-3.4-3.74-4.6-.51-6.14 3.07-4.88 5.65.68 1.15 2.04 1.45 3.34 1.16a2.8 2.8 0 0 0 2.26-2.61c-.07-1.2-.75-1.7-1.59-1.8-1.34-.06-1.98.53-2.09 1.49-.03.74.53.99 1 .7' style='fill:%23b39c1c;fill-opacity:1;fill-rule:nonzero;stroke:none' transform='scale(.59524)'/%3E%3Cpath d='M109.75 243.09c-.41.28-.21.51-.55.87q-.57.4-1.07-.1c-.27-.4-.19-1.15.44-1.75.63-.48 1.49-.87 2.7-.2.93.65 1.23 2.27.33 3.52-.77 1-2.32 1.67-4.23.94-1.83-.72-2.57-2.97-1.17-5.17a6 6 0 0 1 5.26-2.34c1.77.1 3.32.41 4.82 1.97a4.1 4.1 0 0 1 3.98-.45c.4.16.28.52.04.54-.64.03-2.67.21-3.25 3.24-.68 3.35-2.35 5.7-4.1 6.43l-3.27-.5c1.34-.1 4.94-1.82 5.46-5.3.1-.97.1-2.34-1.12-3.61a5.25 5.25 0 0 1-1.3 6.56c-2 1.54-5.34 2.47-9.66-.63-1.05.84-2.5 1-3.88.44-.27-.14-.33-.5.06-.57.67-.13 2.77-.48 3.2-3.19.42-2.82 1.55-4.95 4.09-6.42l3.27.49c-.89.2-4.67.96-5.44 5.35-.33 2.22 1.15 3.72 2.87 4.15 4.48 1.14 6.48-2.22 5.56-4.92-.5-1.23-1.8-1.73-3.15-1.6-1.37.14-2.4 1.07-2.57 2.3-.09 1.19.51 1.78 1.32 1.98 1.33.22 2.05-.27 2.29-1.2.12-.72-.41-1.05-.93-.83' style='fill:%23b39c1c;fill-opacity:1;fill-rule:nonzero;stroke:none' transform='scale(.59524)'/%3E%3Cpath d='M92.85 241.37c.45-.2.3-.45.7-.75q.6-.3 1.02.26c.22.44 0 1.16-.73 1.66-.68.38-1.6.62-2.67-.25-.83-.79-.87-2.43.24-3.53.92-.84 2.56-1.27 4.34-.21 1.66 1 2.04 3.33.3 5.28a6.1 6.1 0 0 1-5.58 1.46c-1.72-.42-3.2-.97-4.43-2.73a4.2 4.2 0 0 1-4-.2c-.37-.25-.18-.57.04-.57.63.09 2.68.22 3.74-2.63 1.22-3.22 3.25-5.27 5.1-5.7l3.14 1.04c-1.33-.13-5.18.98-6.24 4.34-.26.94-.5 2.26.51 3.74a5.3 5.3 0 0 1 2.36-6.3c2.22-1.16 5.67-1.53 9.41 2.22a3.8 3.8 0 0 1 3.9.23c.25.16.25.52-.16.54-.67.02-2.8 0-3.66 2.6-.88 2.73-2.35 4.65-5.1 5.7-.42-.16-3.13-1.04-3.13-1.04.9-.05 4.76-.18 6.25-4.39.69-2.12-.54-3.84-2.18-4.57-4.22-1.86-6.74 1.14-6.28 3.97.3 1.28 1.51 1.98 2.85 2.1 1.37.06 2.55-.7 2.91-1.85.29-1.17-.22-1.84-.97-2.2-1.3-.4-2.07-.05-2.45.83-.25.68.22 1.1.77.95' style='fill:%23b39c1c;fill-opacity:1;fill-rule:nonzero;stroke:none' transform='scale(.59524)'/%3E%3Cpath d='M77.4 233.8c-.48.13-.36.41-.79.66-.42.16-.78.04-.98-.4-.15-.46.15-1.15.93-1.54a2.2 2.2 0 0 1 2.64.58c.71.89.52 2.55-.7 3.49-1.04.7-2.71.9-4.35-.36-1.52-1.21-1.59-3.58.4-5.28a6 6 0 0 1 5.73-.7c1.65.62 3.06 1.37 4.02 3.27a4.2 4.2 0 0 1 3.95.73c.33.3.1.59-.13.55-.6-.18-2.6-.59-4.05 2.11-1.61 3.03-3.91 4.81-5.78 4.98l-3-1.43c1.31.3 5.26-.3 6.76-3.48.39-.9.8-2.21-.01-3.76a5.2 5.2 0 0 1-3.15 5.89c-2.36.89-5.83.8-9.06-3.43-1.24.5-2.68.23-3.84-.7-.2-.21-.18-.58.24-.53.66.07 2.78.36 3.98-2.11 1.22-2.59 2.92-4.29 5.78-4.96l2.98 1.43c-.9-.06-4.74-.44-6.77 3.53-.96 2.03.03 3.9 1.55 4.82 3.94 2.38 6.84-.25 6.75-3.1-.12-1.34-1.23-2.18-2.55-2.46-1.35-.25-2.61.35-3.13 1.45-.43 1.12-.02 1.86.69 2.28 1.21.6 2.03.33 2.52-.48.35-.66-.06-1.12-.63-1.04' style='fill:%23b39c1c;fill-opacity:1;fill-rule:nonzero;stroke:none' transform='scale(.59524)'/%3E%3Cpath d='M61.75 227.4c.5-.07.41-.37.88-.54q.68-.14.92.51c.08.5-.32 1.15-1.16 1.4-.76.2-1.72.18-2.5-.95-.59-.96-.16-2.58 1.2-3.34 1.11-.55 2.8-.51 4.23.98 1.33 1.43 1.03 3.79-1.18 5.17a6 6 0 0 1-5.75-.15c-1.55-.86-2.83-1.8-3.5-3.82a4.1 4.1 0 0 1-3.79-1.32c-.3-.3-.03-.57.2-.5.57.26 2.5.97 4.3-1.52 2.07-2.77 4.58-4.18 6.48-4.07l2.72 1.86c-1.25-.5-5.23-.48-7.18 2.44a4.2 4.2 0 0 0-.55 3.75 5.26 5.26 0 0 1 4-5.39c2.46-.52 5.88.07 8.45 4.72 1.3-.29 2.7.18 3.69 1.28.18.22.1.58-.3.49-.66-.17-2.7-.78-4.25 1.49-1.57 2.37-3.53 3.82-6.46 4.07l-2.73-1.85c.88.19 4.63 1.12 7.23-2.5 1.23-1.87.52-3.87-.85-5-3.55-2.93-6.8-.75-7.12 2.1-.07 1.32.9 2.32 2.16 2.8 1.3.44 2.63.04 3.31-.99.59-1.05.29-1.82-.34-2.35-1.13-.79-1.96-.64-2.58.1-.44.6-.1 1.1.47 1.13' style='fill:%23b39c1c;fill-opacity:1;fill-rule:nonzero;stroke:none' transform='scale(.59524)'/%3E%3Cpath d='M49.04 215.82c-.5 0-.46.28-.95.4q-.7.04-.83-.65c-.02-.5.46-1.07 1.32-1.22.78-.1 1.73.06 2.37 1.28.44 1.05-.18 2.56-1.64 3.15-1.18.4-2.85.15-4.06-1.54-1.14-1.58-.54-3.87 1.84-4.95a6.1 6.1 0 0 1 5.7.88c1.4 1.07 2.55 2.15 2.96 4.27a4.1 4.1 0 0 1 3.58 1.78c.26.36-.05.6-.25.49-.54-.33-2.35-1.3-4.49.93-2.4 2.47-5.07 3.53-6.94 3.2l-2.47-2.21c1.18.65 5.14 1.15 7.45-1.49a4.2 4.2 0 0 0 1.02-3.64 5.3 5.3 0 0 1-4.65 4.82c-2.51.2-5.83-.84-7.77-5.78a3.8 3.8 0 0 1-3.48-1.74c-.17-.26-.03-.6.36-.45.63.26 2.58 1.1 4.4-.93 1.88-2.13 4-3.33 6.93-3.18l2.47 2.2c-.85-.32-4.43-1.74-7.48 1.54-1.47 1.67-1.05 3.73.18 5.05 3.13 3.38 6.64 1.64 7.33-1.13.25-1.32-.58-2.44-1.77-3.07a2.8 2.8 0 0 0-3.4.53c-.73.96-.54 1.78.03 2.4 1 .9 1.86.88 2.56.22.52-.53.24-1.09-.32-1.16' style='fill:%23b39c1c;fill-opacity:1;fill-rule:nonzero;stroke:none' transform='scale(.59524)'/%3E%3Cpath d='M35.8 205.18c.5.07.5-.23.99-.27q.7.07.73.78c-.07.49-.63.98-1.52 1a2.2 2.2 0 0 1-2.12-1.64c-.27-1.11.6-2.51 2.1-2.85 1.24-.2 2.84.32 3.79 2.16.87 1.74-.08 3.91-2.61 4.6a6.1 6.1 0 0 1-5.47-1.77c-1.23-1.26-2.2-2.53-2.26-4.67a4.2 4.2 0 0 1-3.26-2.35c-.18-.39.15-.57.34-.44.5.42 2.12 1.66 4.58-.2 2.74-2.05 5.56-2.7 7.35-2.05l2.1 2.56c-1.06-.82-4.9-1.95-7.6.3a4.2 4.2 0 0 0-1.6 3.42 5.26 5.26 0 0 1 5.37-4.02c2.5.2 5.61 1.75 6.75 6.93 1.35.09 2.53.93 3.18 2.26.1.29-.07.6-.42.4-.6-.35-2.38-1.52-4.5.23-2.2 1.82-4.48 2.65-7.34 2.05l-2.1-2.57c.79.45 4.1 2.4 7.62-.33 1.73-1.44 1.63-3.55.63-5.03-2.56-3.82-6.3-2.67-7.43-.03-.44 1.25.2 2.5 1.28 3.3 1.11.8 2.5.8 3.45 0 .85-.82.8-1.67.35-2.34-.86-1.07-1.71-1.18-2.5-.63-.6.44-.43 1.03.11 1.2' style='fill:%23b39c1c;fill-opacity:1;fill-rule:nonzero;stroke:none' transform='scale(.59524)'/%3E%3Cpath d='M26.8 190.43c-.48-.13-.53.18-1.01.13-.45-.08-.68-.4-.63-.86.13-.48.76-.88 1.63-.8.77.15 1.64.56 1.89 1.91.11 1.14-.92 2.4-2.47 2.55-1.24.04-2.76-.68-3.45-2.64-.64-1.84.6-3.86 3.2-4.23a6.1 6.1 0 0 1 5.18 2.5c1.06 1.43 1.84 2.8 1.63 4.95a4.1 4.1 0 0 1 2.9 2.72c.14.43-.22.57-.38.4-.43-.47-1.9-1.9-4.56-.4-3 1.66-5.89 1.92-7.57 1.07 0 0-.84-1.4-1.74-2.82.95.95 4.6 2.59 7.56.72a4.2 4.2 0 0 0 2.04-3.18 5.3 5.3 0 0 1-5.86 3.26c-2.45-.53-5.32-2.5-5.75-7.8a3.8 3.8 0 0 1-2.84-2.66c-.08-.29.15-.56.46-.32.54.43 2.16 1.82 4.5.39 2.43-1.52 4.78-2.03 7.54-1.04.25.37 1.74 2.8 1.74 2.8-.71-.56-3.75-2.94-7.6-.68-1.9 1.2-2.08 3.28-1.3 4.9 2.04 4.12 5.88 3.48 7.36 1 .61-1.18.14-2.48-.81-3.43-1-.96-2.39-1.12-3.42-.45-.98.7-1.03 1.54-.67 2.29.71 1.16 1.54 1.39 2.39.95.65-.37.56-.97.04-1.23' style='fill:%23b39c1c;fill-opacity:1;fill-rule:nonzero;stroke:none' transform='scale(.59524)'/%3E%3Cpath d='M17.13 176.58c.46.2.54-.09 1.04.01q.65.27.48.96c-.2.44-.89.77-1.73.54-.74-.27-1.53-.8-1.58-2.17.03-1.14 1.27-2.26 2.81-2.14 1.24.13 2.65 1.07 3.02 3.1.35 1.93-1.17 3.74-3.78 3.71a6.1 6.1 0 0 1-4.76-3.23c-.84-1.56-1.4-3.04-.86-5.12a4.2 4.2 0 0 1-2.49-3.19c-.06-.4.31-.5.46-.3.35.52 1.57 2.16 4.44 1.07 3.23-1.2 6.12-1.02 7.64.1l1.3 3.06c-.8-1.1-4.15-3.27-7.37-1.86a4.1 4.1 0 0 0-2.49 2.83 5.3 5.3 0 0 1 6.27-2.34c2.35.88 4.9 3.24 4.54 8.55a3.8 3.8 0 0 1 2.4 3.07c.04.28-.22.54-.5.23-.48-.5-1.85-2.1-4.38-1.02-2.63 1.12-5.05 1.26-7.63-.1-.17-.43-1.3-3.04-1.3-3.04.62.63 3.27 3.45 7.42 1.8 2.05-.89 2.55-2.93 2-4.64-1.39-4.39-5.29-4.33-7.12-2.1-.77 1.06-.5 2.42.3 3.51.85 1.08 2.19 1.46 3.31.96 1.06-.53 1.25-1.37 1-2.15-.51-1.28-1.32-1.6-2.22-1.3-.7.26-.69.88-.23 1.2' style='fill:%23b39c1c;fill-opacity:1;fill-rule:nonzero;stroke:none' transform='scale(.59524)'/%3E%3Cpath d='M12.7 159.85c-.43-.26-.55 0-1.02-.16q-.6-.33-.35-1c.26-.44.98-.64 1.79-.3.7.35 1.4.99 1.27 2.36-.2 1.12-1.56 2.05-3.08 1.75-1.21-.32-2.45-1.44-2.58-3.49-.08-1.96 1.66-3.57 4.25-3.18a6.1 6.1 0 0 1 4.29 3.86c.62 1.67.97 3.22.17 5.2a4.2 4.2 0 0 1 2.04 3.45c0 .44-.4.47-.5.27-.29-.56-1.28-2.34-4.27-1.66-3.36.74-6.19.18-7.56-1.12l-.87-3.2c.63 1.19 3.66 3.78 7.06 2.82.92-.3 2.19-.84 2.85-2.47a5.3 5.3 0 0 1-6.54 1.48c-2.2-1.2-4.42-3.87-3.34-9.1a3.8 3.8 0 0 1-1.98-3.35c.01-.3.32-.5.55-.17.4.55 1.55 2.34 4.2 1.62 2.75-.76 5.15-.6 7.53 1.11l.88 3.2c-.53-.72-2.78-3.87-7.1-2.8-2.17.62-2.91 2.57-2.62 4.32.78 4.56 4.67 5.03 6.77 3.07.9-.97.84-2.36.18-3.54-.7-1.18-1.97-1.75-3.15-1.4-1.13.4-1.42 1.2-1.28 2.02.35 1.32 1.08 1.76 2.03 1.58.72-.17.8-.78.39-1.17m-5.47-16.16c.38.33.55.05.98.32q.56.41.2 1.03c-.32.37-1.06.48-1.81.03a2.2 2.2 0 0 1-.91-2.53c.37-1.07 1.87-1.8 3.32-1.26 1.14.5 2.21 1.8 2 3.85-.2 1.94-2.17 3.24-4.68 2.48a6.1 6.1 0 0 1-3.64-4.47c-.36-1.75-.47-3.3.62-5.16a4.2 4.2 0 0 1-1.47-3.7c.06-.45.44-.42.52-.22.19.64.9 2.55 3.95 2.3 3.43-.22 6.15.76 7.31 2.26 0 0 .19 1.6.37 3.3-.45-1.27-3.04-4.3-6.54-3.87a4.2 4.2 0 0 0-3.2 2.02 5.3 5.3 0 0 1 6.7-.49c2 1.54 3.77 4.51 1.92 9.5a3.8 3.8 0 0 1 1.43 3.63c-.05.27-.37.45-.56.1-.3-.62-1.17-2.58-3.9-2.26-2.83.33-5.2-.2-7.3-2.26L2.19 145c.43.82 2.16 4.25 6.6 3.86 2.22-.27 3.29-2.1 3.24-3.89-.08-4.6-3.83-5.65-6.22-4.04-1.05.82-1.18 2.19-.71 3.46.5 1.28 1.66 2.02 2.9 1.88 1.17-.23 1.58-.97 1.56-1.8-.12-1.37-.8-1.9-1.75-1.88-.75.05-.92.66-.56 1.1' style='fill:%23b39c1c;fill-opacity:1;fill-rule:nonzero;stroke:none' transform='scale(.59524)'/%3E%3Cpath d='M7.77 126.54c-.32-.37-.53-.15-.94-.43q-.47-.53-.06-1.08c.38-.33 1.13-.33 1.8.22.57.54 1.08 1.34.57 2.63-.5 1-2.07 1.54-3.44.8-1.08-.62-1.97-2.06-1.5-4.06.46-1.89 2.59-2.94 4.97-1.84a6 6 0 0 1 3.03 4.87c.11 1.8.03 3.36-1.3 5.05 1 1.01 1.3 2.4.97 3.88-.1.43-.49.35-.54.13-.1-.63-.55-2.64-3.62-2.8-3.43-.22-6-1.55-6.94-3.19l.06-3.3c.28 1.3 2.46 4.64 5.99 4.67.97-.03 2.33-.2 3.42-1.58a5.2 5.2 0 0 1-6.69-.4c-1.79-1.77-3.15-4.95-.67-9.66a3.8 3.8 0 0 1-.96-3.78c.1-.29.44-.4.58-.02.22.64.83 2.69 3.58 2.74 2.85.04 5.12.86 6.92 3.19l-.05 3.3c-.31-.85-1.58-4.49-6.03-4.66-2.24-.04-3.54 1.65-3.73 3.4-.51 4.59 3.08 6.11 5.64 4.85 1.15-.68 1.46-2.04 1.16-3.35-.33-1.33-1.4-2.22-2.62-2.22-1.2.06-1.7.74-1.8 1.56-.02 1.36.55 1.99 1.5 2.1.76.05 1-.54.7-1.02' style='fill:%23b39c1c;fill-opacity:1;fill-rule:nonzero;stroke:none' transform='scale(.59524)'/%3E%3Cpath d='M7.07 109.6c.27.42.5.23.85.56q.42.6-.1 1.08c-.4.27-1.15.17-1.75-.46-.47-.64-.86-1.5-.17-2.7.65-.94 2.29-1.2 3.53-.3.97.8 1.64 2.34.89 4.26-.75 1.81-3 2.53-5.19 1.1a6.1 6.1 0 0 1-2.28-5.3c.15-1.77.46-3.32 2.02-4.78a4.2 4.2 0 0 1-.4-4c.18-.4.53-.26.56-.04 0 .64.17 2.67 3.17 3.3 3.36.73 5.7 2.42 6.4 4.17l-.55 3.26c-.07-1.32-1.75-4.95-5.22-5.5a4.2 4.2 0 0 0-3.63 1.05 5.3 5.3 0 0 1 6.57 1.4c1.5 2.01 2.39 5.36-.77 9.66.82 1.05.98 2.5.39 3.87-.13.26-.5.33-.57-.07-.13-.68-.43-2.77-3.14-3.23-2.82-.45-4.93-1.62-6.38-4.18l.54-3.25c.19.88.9 4.7 5.29 5.51 2.21.35 3.73-1.13 4.18-2.84 1.2-4.45-2.15-6.5-4.87-5.62-1.23.51-1.73 1.8-1.63 3.14.12 1.37 1.04 2.42 2.27 2.6 1.19.1 1.78-.5 1.99-1.29.25-1.36-.24-2.05-1.17-2.3-.73-.15-1.05.38-.83.9' style='fill:%23b39c1c;fill-opacity:1;fill-rule:nonzero;stroke:none' transform='scale(.59524)'/%3E%3Cpath d='M12.36 93.2c-.22-.43-.48-.28-.79-.66q-.33-.62.24-1.04c.44-.2 1.17-.04 1.67.68.4.69.67 1.6-.18 2.7-.76.83-2.41.9-3.53-.16-.86-.92-1.32-2.54-.31-4.36.97-1.68 3.3-2.1 5.28-.4a6.2 6.2 0 0 1 1.56 5.55c-.37 1.74-.89 3.25-2.63 4.49a4.1 4.1 0 0 1-.13 4c-.23.38-.56.2-.56-.04.1-.62.2-2.68-2.7-3.69-3.24-1.15-5.34-3.13-5.8-4.96l.97-3.18c-.1 1.37 1.08 5.15 4.46 6.16.95.25 2.3.45 3.73-.59a5.3 5.3 0 0 1-6.32-2.21c-1.23-2.2-1.67-5.64 2.01-9.48a3.8 3.8 0 0 1 .13-3.9c.16-.24.53-.27.54.14.06.68.07 2.82 2.7 3.61 2.73.83 4.68 2.25 5.78 4.98l-.95 3.15c-.07-.9-.28-4.76-4.53-6.14-2.15-.64-3.84.61-4.52 2.26-1.76 4.26 1.28 6.72 4.09 6.19 1.3-.32 1.96-1.53 2.04-2.89a2.8 2.8 0 0 0-1.9-2.88c-1.18-.26-1.84.27-2.16 1.03-.41 1.3-.03 2.07.86 2.43.7.26 1.1-.22.95-.78' style='fill:%23b39c1c;fill-opacity:1;fill-rule:nonzero;stroke:none' transform='scale(.59524)'/%3E%3Cpath d='M16.52 76.73c.13.49.4.36.64.8q.24.65-.4.98c-.47.13-1.16-.17-1.53-.96-.3-.74-.4-1.67.61-2.6.9-.72 2.53-.52 3.47.72.7 1.03.88 2.72-.4 4.33-1.22 1.52-3.6 1.55-5.28-.47a6.2 6.2 0 0 1-.65-5.72c.66-1.67 1.43-3.04 3.34-3.99a4.2 4.2 0 0 1 .79-3.93c.28-.34.59-.11.54.13-.18.6-.62 2.6 2.08 4.06 3 1.68 4.74 3.97 4.9 5.87l-1.47 2.96c.32-1.3-.24-5.24-3.4-6.8-.9-.38-2.2-.8-3.78-.02a5.24 5.24 0 0 1 5.87 3.22c.86 2.35.72 5.83-3.53 9.01.48 1.26.19 2.7-.77 3.84-.2.2-.55.15-.52-.23.08-.69.4-2.79-2.04-4.02-2.58-1.25-4.27-2.98-4.9-5.86l1.46-2.94c-.09.89-.5 4.73 3.45 6.8 2.02.98 3.9.02 4.84-1.5 2.42-3.9-.18-6.82-3.04-6.79-1.32.12-2.19 1.22-2.49 2.53-.26 1.35.3 2.62 1.43 3.13 1.11.47 1.85.05 2.3-.64.61-1.2.35-2.04-.47-2.55-.65-.33-1.11.06-1.05.64' style='fill:%23b39c1c;fill-opacity:1;fill-rule:nonzero;stroke:none' transform='scale(.59524)'/%3E%3Cpath d='M26.17 62.63c-.08-.5-.36-.4-.55-.86-.09-.45.1-.79.54-.93.48-.08 1.12.33 1.4 1.16.18.76.17 1.7-.96 2.5-.98.59-2.58.17-3.34-1.2-.55-1.1-.53-2.79.96-4.23 1.42-1.33 3.78-1.05 5.19 1.16a6.1 6.1 0 0 1-.13 5.75c-.85 1.56-1.79 2.84-3.82 3.53a4.2 4.2 0 0 1-1.29 3.8c-.33.28-.6.03-.52-.2.25-.59.95-2.5-1.53-4.3-2.76-2.04-4.19-4.58-4.1-6.48l1.86-2.72c-.49 1.26-.47 5.24 2.47 7.18a4.2 4.2 0 0 0 3.74.53 5.3 5.3 0 0 1-5.4-3.97c-.53-2.47.05-5.9 4.69-8.5a3.8 3.8 0 0 1 1.25-3.66c.23-.2.59-.1.5.28-.17.68-.75 2.71 1.51 4.26 2.38 1.57 3.82 3.5 4.09 6.43L30.9 64.9c.19-.88 1.1-4.63-2.55-7.2-1.86-1.24-3.85-.52-4.98.87-2.92 3.54-.74 6.77 2.1 7.1 1.34.06 2.34-.91 2.8-2.19s.04-2.61-.99-3.3c-1.05-.57-1.83-.26-2.35.36-.78 1.13-.63 1.98.1 2.58.61.43 1.13.1 1.14-.5' style='fill:%23b39c1c;fill-opacity:1;fill-rule:nonzero;stroke:none' transform='scale(.59524)'/%3E%3Cpath d='M34.75 48.06c-.01.5.29.46.4.94q.03.72-.65.83c-.51 0-1.07-.47-1.23-1.33-.06-.8.1-1.72 1.32-2.34 1.05-.44 2.57.22 3.13 1.66.39 1.18.1 2.85-1.57 4.04-1.61 1.14-3.9.5-4.97-1.9a6.2 6.2 0 0 1 .97-5.67c1.08-1.4 2.19-2.53 4.3-2.92a4.2 4.2 0 0 1 1.83-3.56c.37-.25.6.06.49.26-.33.54-1.31 2.34.87 4.5 2.45 2.41 3.47 5.13 3.11 6.98l-2.23 2.43c.66-1.16 1.22-5.1-1.4-7.47a4.2 4.2 0 0 0-3.61-1.06 5.2 5.2 0 0 1 4.74 4.72c.17 2.51-.9 5.81-5.86 7.7a3.8 3.8 0 0 1-1.8 3.46c-.25.15-.58.02-.43-.36.25-.65 1.15-2.56-.88-4.42-2.12-1.92-3.27-4.03-3.1-6.96.3-.35 2.23-2.46 2.23-2.46-.33.85-1.78 4.42 1.45 7.5 1.66 1.5 3.73 1.08 5.05-.1 3.42-3.12 1.72-6.64-1.05-7.36-1.3-.26-2.43.56-3.07 1.73-.63 1.22-.43 2.6.5 3.42.95.73 1.76.55 2.37 0 .94-1 .91-1.85.27-2.57-.53-.52-1.09-.24-1.18.3' style='fill:%23b39c1c;fill-opacity:1;fill-rule:nonzero;stroke:none' transform='scale(.59524)'/%3E%3Cpath d='M48.02 37.14c.07-.5-.22-.5-.27-.98.04-.45.29-.74.76-.76.49.07 1 .6 1.02 1.5-.01.76-.3 1.69-1.6 2.13-1.1.32-2.52-.51-2.89-2.05-.22-1.23.28-2.82 2.1-3.8 1.74-.89 3.92.03 4.65 2.53a6 6 0 0 1-1.69 5.5c-1.25 1.26-2.5 2.24-4.65 2.34a4.1 4.1 0 0 1-2.27 3.29c-.4.2-.59-.14-.46-.32.42-.5 1.62-2.15-.27-4.58-2.1-2.72-2.78-5.52-2.17-7.33l2.52-2.13c-.8 1.08-1.87 4.93.42 7.6a4.2 4.2 0 0 0 3.44 1.53 5.24 5.24 0 0 1-4.1-5.3c.18-2.51 1.68-5.65 6.85-6.85a3.8 3.8 0 0 1 2.22-3.21c.27-.13.59.06.4.41-.35.6-1.48 2.4.28 4.5 1.85 2.17 2.73 4.42 2.15 7.3-.32.3-2.52 2.15-2.52 2.15.42-.8 2.35-4.15-.45-7.62-1.45-1.7-3.56-1.57-5.03-.55-3.8 2.63-2.57 6.32.08 7.41 1.25.44 2.48-.23 3.28-1.3.78-1.14.76-2.55-.05-3.47-.85-.85-1.68-.79-2.35-.3-1.06.84-1.16 1.73-.62 2.5.48.6 1.07.38 1.22-.14' style='fill:%23b39c1c;fill-opacity:1;fill-rule:nonzero;stroke:none' transform='scale(.59524)'/%3E%3Cpath d='M60.44 25.49c-.15.47.16.52.12 1.03q-.16.67-.87.6c-.47-.14-.89-.76-.78-1.63.17-.76.58-1.65 1.93-1.88 1.13-.1 2.4.95 2.52 2.48.03 1.26-.72 2.79-2.66 3.43-1.85.63-3.87-.63-4.21-3.22a6.1 6.1 0 0 1 2.55-5.16c1.43-1.05 2.82-1.8 4.96-1.59.34-1.38 1.34-2.34 2.76-2.89.43-.11.56.25.4.4-.48.42-1.92 1.89-.44 4.56 1.63 3.03 1.86 5.9.98 7.57l-2.84 1.7c.96-.92 2.63-4.54.8-7.55a4.2 4.2 0 0 0-3.17-2.05 5.2 5.2 0 0 1 3.2 5.87c-.54 2.45-2.53 5.3-7.81 5.68a3.9 3.9 0 0 1-2.71 2.82c-.29.09-.57-.14-.32-.46.43-.54 1.85-2.14.42-4.5-1.48-2.45-1.97-4.8-.97-7.55l2.82-1.73c-.55.72-2.97 3.74-.76 7.62 1.2 1.89 3.29 2.1 4.88 1.33 4.17-2 3.55-5.86 1.11-7.34-1.17-.62-2.5-.15-3.44.78-.97 1-1.17 2.37-.51 3.4.69.99 1.53 1.04 2.28.7 1.18-.7 1.4-1.53 1-2.38-.38-.65-.98-.56-1.24-.04' style='fill:%23b39c1c;fill-opacity:1;fill-rule:nonzero;stroke:none' transform='scale(.59524)'/%3E%3Cpath d='M76.32 18.7c.21-.47-.07-.54.01-1.04q.27-.64.94-.5c.46.22.77.88.57 1.73a2.2 2.2 0 0 1-2.16 1.6c-1.14-.03-2.26-1.25-2.16-2.8.12-1.24 1.06-2.65 3.09-3.03 1.91-.36 3.75 1.13 3.73 3.75a6 6 0 0 1-3.21 4.78c-1.56.85-3.03 1.41-5.11.9a4.2 4.2 0 0 1-3.15 2.51c-.43.06-.51-.31-.32-.45.52-.36 2.16-1.6 1.04-4.47-1.2-3.2-1.06-6.08.05-7.63l3.03-1.32c-1.09.8-3.22 4.18-1.8 7.38a4.2 4.2 0 0 0 2.86 2.48 5.25 5.25 0 0 1-2.39-6.26c.87-2.36 3.21-4.94 8.52-4.6a3.9 3.9 0 0 1 3.04-2.44c.3-.04.55.24.26.52-.48.49-2.1 1.87-1.01 4.39 1.14 2.6 1.32 5.03-.04 7.62l-3.02 1.3c.63-.62 3.42-3.27 1.74-7.4-.9-2.06-2.95-2.52-4.66-1.99-4.38 1.41-4.28 5.32-2.06 7.13 1.09.77 2.46.5 3.52-.32 1.08-.85 1.46-2.2.95-3.31-.56-1.07-1.39-1.23-2.16-.98-1.28.52-1.6 1.32-1.3 2.24.26.69.9.68 1.2.2' style='fill:%23b39c1c;fill-opacity:1;fill-rule:nonzero;stroke:none' transform='scale(.59524)'/%3E%3Cpath d='M91.42 11.05c-.28.42 0 .54-.16 1.02q-.36.59-1.01.33c-.42-.27-.64-.98-.29-1.78.37-.7 1-1.4 2.38-1.25 1.1.2 2.03 1.57 1.72 3.08-.32 1.21-1.47 2.45-3.53 2.56-1.95.06-3.54-1.7-3.12-4.28a6.1 6.1 0 0 1 3.89-4.25c1.66-.6 3.2-.94 5.19-.12a4.2 4.2 0 0 1 3.47-2.02c.44 0 .47.4.26.51-.57.25-2.36 1.25-1.7 4.25.73 3.35.13 6.17-1.18 7.55l-3.21.83c1.2-.63 3.83-3.63 2.89-7.03-.3-.93-.83-2.2-2.46-2.86A5.25 5.25 0 0 1 96 14.13c-1.21 2.2-3.92 4.39-9.12 3.28a3.8 3.8 0 0 1-3.38 1.94c-.29 0-.5-.31-.17-.55.56-.4 2.36-1.53 1.66-4.2-.74-2.74-.56-5.15 1.17-7.51l3.2-.86c-.73.55-3.88 2.75-2.84 7.1.58 2.15 2.54 2.93 4.3 2.64 4.56-.75 5.05-4.61 3.11-6.74-.96-.93-2.35-.85-3.53-.21-1.19.7-1.76 1.95-1.43 3.14.39 1.12 1.17 1.43 2 1.28 1.32-.32 1.76-1.05 1.62-2-.17-.73-.79-.8-1.17-.4' style='fill:%23b39c1c;fill-opacity:1;fill-rule:nonzero;stroke:none' transform='scale(.59524)'/%3E%3Cpath d='M108.6 9.06c.33-.38.07-.56.3-1q.43-.54 1.05-.22c.37.34.49 1.08.06 1.83-.47.64-1.2 1.26-2.53.93-1.1-.35-1.82-1.84-1.3-3.3.5-1.16 1.78-2.23 3.83-2.05 1.94.2 3.28 2.17 2.53 4.66a6.2 6.2 0 0 1-4.43 3.7c-1.73.36-3.32.5-5.16-.6a4.2 4.2 0 0 1-3.72 1.51c-.44-.04-.41-.44-.2-.52.62-.18 2.51-.9 2.27-3.98-.28-3.42.7-6.13 2.18-7.3l3.29-.4c-1.27.44-4.26 3.08-3.8 6.56.16.96.51 2.3 2.04 3.18a5.3 5.3 0 0 1-.53-6.68c1.5-2.02 4.47-3.81 9.47-2.02a3.8 3.8 0 0 1 3.6-1.46c.3.06.47.37.1.55-.6.32-2.54 1.21-2.2 3.94.35 2.83-.15 5.19-2.19 7.3l-3.27.42c.8-.44 4.22-2.22 3.76-6.64-.28-2.23-2.13-3.26-3.9-3.22-4.61.13-5.63 3.9-4 6.27.83 1.06 2.22 1.14 3.48.68 1.26-.52 2.01-1.69 1.83-2.91-.23-1.18-.97-1.59-1.8-1.55-1.34.14-1.9.8-1.87 1.76.08.75.68.91 1.11.56' style='fill:%23b39c1c;fill-opacity:1;fill-rule:nonzero;stroke:none' transform='scale(.59524)'/%3E%3Cpath d='M123.79 133.35c.05-.25.45-.25.56.06.11.3.11 1.25 1 1.25.6-.02.75-.68.81-1.27.05-.29.46-.3.55-.03.2.57.63 1.75-.44 2.86.03.54.01 1.29.01 1.29-.12.28-.66.46-1.43.31-.24-.03-.34.36 0 .45 0 0 .96.2 1.57-.15.56-.37.93-.27 1.74-.12 1.6.47 3.27 1.76 3.71 4.63 0 0 .57 5.37.85 7.6a7.3 7.3 0 0 0 2.17 4.46c1.12 1.09 2.9 2.56 3.2 5.23-5.28-4.84-20.16-4.81-25.45-.08.38-2.36 2.13-4.02 3.27-5.11a7.8 7.8 0 0 0 2.2-4.5s.61-6 .85-7.57a5.6 5.6 0 0 1 3.66-4.6c.77-.21 1.7-.24 1.7-.65 0-.43.04-1.19.04-1.19-.61-.43-1.1-1.27-.57-2.87' style='fill:%23000;fill-opacity:1;fill-rule:nonzero;stroke:none' transform='scale(.59524)'/%3E%3Cpath d='M119.74 156.8c.74-.16 7.01-1.34 12.81.4 1.5.39 4.15 1.32 5.52 2.72.16.67.17 1.78-.48 2.63-2.1 1.79-5.06 3.61-11.7 3.7-7.76 0-10.53-1.63-12.66-3.58-1.14-1.21-.53-2.37 0-2.92 1.1-1.14 3.59-2.29 6.5-2.96' style='fill:%23fff;fill-opacity:1;fill-rule:nonzero;stroke:none' transform='scale(.59524)'/%3E%3Cpath d='M119.03 157.5a30 30 0 0 1 12.57 0s4.02 1.02 5.76 2.58c.94.88 1 1.69 0 2.69-.66.5-2.25 1.9-5.76 2.86-3.77.77-8.13.86-12.57 0-3.13-.78-4.55-1.77-5.68-2.86-.9-.95-1.05-1.8 0-2.7.36-.3.56-.42.9-.6 0 0 .21.28.6.63-1.42.28-1.04 1.75 2.6 3.08 2.78.98 4.66 1.43 9.82 1.32 5-.34 7.22-2.1 8.7-3.18.29-.28.05-.45-.23-.23-.51.37-1.42.98-2.37 1.38-.52.28-2.09.3-2.98.2.96-.25 2.09-.78 2.4-.96.16-.12.13-.34-.24-.3-1.76.18-3.04.17-3.7.13a.8.8 0 0 1-.63-.5c-.2-.43-.19-1.34-.32-2-.12-.56-.55-.47-.45-.1.17 1.04.42 3.73-2.42 3.41-.57-.13-.9-.5-.4-.8 1.01-.58 1.01-3.73-1.16-3.37-1.42.23-2.33 3.47.4 4.6.6.25 2.45.52 4.16.28 1.73-.2 3.69-.26 4.92-.3-1.7.62-3.14 1.33-7.6 1.36a22 22 0 0 1-7.84-1.33c-2.34-.9-3.89-2.11-2.58-2.59a9.5 9.5 0 0 0 6.87 2.16c.23 0 .34-.34-.03-.34 0 0-3.6-1.04-5.6-3.54q1.01-.5 2.86-.98' style='fill:%23000;fill-opacity:1;fill-rule:nonzero;stroke:none' transform='scale(.59524)'/%3E%3Cpath d='M126.97 141.75c-.03-.53-.03-1.56.87-1.5.86.1 1.32.75 1.4 1.56-.84-.13-2.3-.03-2.3-.03m.04 1.52a20 20 0 0 1 2.43 0s.7 4.73.97 8.38a20 20 0 0 0-3.2-.09zm.85 9.8c.19.42.48 1.85.7 2.56 2.15.27 3.56.56 5.54 1.27-.36-.7-1.46-2.72-3.09-3.53a11 11 0 0 0-3.15-.3m-5.08-10.84c-.64 1-1.11 2.69-1.65 6.31-.24 1.75-.35 2.82-.77 3.73 0 0 1.75-.33 2.72-.33.06-1.28.18-8.06-.3-9.71m-7.71 13.3a8.4 8.4 0 0 1 4.32-1.85c1.97-.28 2.69-.42 4.1-.5.48-.03.86.22.9.83l-.02 2.3c-2.2.14-7.9.59-11.72 3.55.02-1.09.95-3.12 2.42-4.33' style='fill:%23fff;fill-opacity:1;fill-rule:nonzero;stroke:none' transform='scale(.59524)'/%3E%3Cpath d='M102.58 110.98c12.19-6.96 33.46-7.41 46 0v4.36l-1.54 1.04v2.64c.35.24 1.2.89 1.55 1.28v6.06c-.41 1.12-2.62 4.62-14.16 6.64-5 .87-13.6.87-18.33-.11-9.15-2-12.69-5.18-13.52-6.53v-6.06c.45-.44.98-.9 1.5-1.3v-2.62l-1.5-1.01zm0 0' style='fill:%23000;fill-opacity:1;fill-rule:nonzero;stroke:none' transform='scale(.59524)'/%3E%3Cpath d='M147.11 118.44c-11.25-6.28-29.2-6.48-43.06-.12v.64a14 14 0 0 0-1.6 1.38l-.03 5.95c.42.64.98 1.25 1.88 1.92 1.04-.3 18.38-5.79 18.38-5.79-1.05-.1-5.08-.83-5.08-.83-1.23.36-14.15 4.5-14.15 4.5s1.08-2.62 5.2-3.9l2.04.38c1.26-.42 9.35-2.82 9.35-2.82 4.37-.37 13.7-1.46 21.83 2.1l-15.4 4.32c-.55-.63-1.82-.4-2.2.54l-7.42 2.25c1.67.38 6.06 1.28 6.06 1.28.79-.22 1.4-.44 1.4-.44q0 .69-.03 1.14c-1.35.38-7.43 2.2-7.43 2.2.84.15 2.9.33 3.77.36 0-.2.04-.57.04-.57.86-.24 3.68-1.11 3.68-1.11-.02.2 0 .48-.02.66-.44.04-.95.44-1.23 1.11.23.03.4.03.6.03.1-.29.61-.87.7 0 0 0 .99.05 1.73.02.05-.42.41-.75.72.08 1.31 0 4.65-.26 6.05-.47-.37-.05-1.02-.09-1.45-.14.53-.17 10.48-3.39 11.12-3.64-.28-.08-1.08-.25-1.32-.3-2.19.75-11.54 3.86-12.82 4.27l-1.08.03c-.21-.64-.39-.81-.77-1.04l-.02-1.2c.85-.28 11.21-3.27 11.21-3.27-.7-.17-1.86-.42-1.86-.42l-9.38 2.76.01-1.08c1.1-.33 19.34-5.56 19.34-5.56a9 9 0 0 1 2.76 1.91l.01-1.08c-1.5-1.12-5.2-2.96-7.78-3.9.05-.83.07-4.36.07-4.36s-1.15-.48-3.67-1.05l-.06 4.42s-1.7-.32-3.13-.53c0-1.05-.08-4.55-.08-4.55l-.4-.04.03 4.49a7 7 0 0 0-.89-.12l-.01-4.55c-1.17-.11-2.74-.32-4.52-.3l-.06 4.44c-3.16 0-11.43.46-17.17 2.22v-4.43c-.61.16-1.17.26-1.94.53v4.55c-.46.19-1.14.37-1.95.76l.05-4.21c11.33-4.27 27.49-5.47 39.97 1.2zm0 0' style='fill:%23fff;fill-opacity:1;fill-rule:nonzero;stroke:none' transform='scale(.59524)'/%3E%3Cpath d='M109.09 108.1a8 8 0 0 1 1.79-.52l.03 4.4c5.12-1.3 10.5-2 17.55-1.87l.01-4.54c1.37.08 3 .19 4.5.41.03 1 .02 4.6.02 4.6.33.05.63.05.63.05l.04-4.52.81.12.02 4.5c.57.05 2.55.4 3.01.5l-.03-4.46s2.5.59 3.62.94l.05 4.36s4.96 1.53 7.43 3.3l-1.53 1.05c-10.96-5.7-28.72-6.63-42.99-.03l-1.47-1.02-.06-4.4a30 30 0 0 1 4.64-2.15l.03 4.3c.74-.3 1.92-.64 1.92-.64-.02-.85-.02-4.38-.02-4.38' style='fill:%23fff;fill-opacity:1;fill-rule:nonzero;stroke:none' transform='scale(.59524)'/%3E%3Cpath d='M124.78 127.67c.07-.85 1.27-.82 1.3-.03l-.01 5.3c-.02.72-1.22.67-1.26-.06-.04-.82-.03-5.2-.03-5.2m-8.2-22.05c-.67-4.48-2.3-24.53-20.76-23.58-8.94.68-12.5 9.02-12.8 14.43l-1.79 51.74c-.44.91-.79 1.7-1 2.6 0 .89-1 36.51-1 36.51.84.58 2.97 2.13 2.97 2.13l.9-36.26c0-1.47.08-2.24-.6-3.17-.62-.58.2-.98.45-.73.28.29 1.01 1.25.98 2.9 0 .67-.83 37.83-.83 37.83l.66.42c.08-1.04.95-39.41.95-39.41a17 17 0 0 0-.78-2.73l1.67-50.9c.17-4.13 2.42-12.06 10.11-12.66 4.26-.12 16.08-.31 18.08 21.48 1.12-.2 1.75-.37 2.8-.6m19.15.23c.67-4.5 2.3-24.54 20.76-23.57 8.96.67 12.5 9 12.8 14.4l1.8 51.78c.45.89.78 1.67 1 2.57 0 .89 1.01 36.51 1.01 36.51l-.68.5-1.16-34.87c-.1-1.47-.27-2.77-1.17-3.4-.78-.47-1.05.24-.74.4.37.23.89.53.96 2.25.09 1.22 1.2 36.26 1.2 36.26l-2.97 2c-.07-1.04-.92-39.42-.92-39.42.1-.95.78-2.72.78-2.72l-1.68-50.9c-.17-4.13-2.43-12.06-10.12-12.67-4.26-.1-16.08-.3-18.07 21.48-.86-.14-1.9-.42-2.8-.6' style='fill:%23000;fill-opacity:1;fill-rule:nonzero;stroke:none' transform='scale(.59524)'/%3E%3Cpath d='M109.23 107.45c-.22-1.22-1.09-6.97-8.36-7.02-3 .17-8.78 3.24-9 11.43l-1.53 57.5c-.45.74-1.05 2.16-1.05 2.16l-.44 20.93 3.31 1.07c0-.72.4-20.5.4-20.5.02-.86-.02-1.46-.96-2.06-.4-.23-.09-.7.3-.61.53.19 1.48.71 1.44 2.08 0 1.38-.35 21.32-.35 21.32.38.1.85.14.85.14l.23-22.32c-.18-.5-.96-2.13-.96-2.13 0-.86 1.33-56.82 1.33-56.82.08-1.56.52-8.87 6.8-9.44 3.1-.23 5.15 2.52 5.42 5.15.97-.26 2.57-.88 2.57-.88m33.31.12c.23-1.23 1.09-7.1 8.36-7.14 2.97.17 8.77 3.24 9 11.43l1.53 57.5a23 23 0 0 1 1.05 2.16l.43 21.87c-.33.17-.84.34-.84.34 0-.72-.38-20.63-.38-20.63-.04-.86-.27-1.83-1.3-2.17-.58-.16-.73.27-.5.56.53.33.9.3.93 1.67 0 1.4.34 20.8.34 20.8l-3.29.94-.17-23.33c.18-.5.96-2.13.96-2.13 0-.87-1.34-56.82-1.34-56.82-.08-1.56-.52-8.87-6.8-9.45-3.09-.22-5.26 2.75-5.52 5.38-.9-.34-2.46-.98-2.46-.98' style='fill:%23000;fill-opacity:1;fill-rule:nonzero;stroke:none' transform='scale(.59524)'/%3E%3Cpath d='M82.32 149.83c-.18-.26.22-.9.67-.45.3.23.96 1.43.94 2.78 0 .48-.24 9.51-.24 9.51l-.79.09c.03-.35.22-9.3.22-9.3 0-.49.07-1.72-.8-2.63m87.15.41c-.51-.28-.06-.86.49-.54.36.19 1.2.77 1.28 3.13l.32 9.06c-.29.05-.83.08-.83.08 0-.35-.36-9.26-.36-9.26-.05-.49-.09-2-.9-2.47' style='fill:%23fff;fill-opacity:1;fill-rule:nonzero;stroke:none' transform='scale(.59524)'/%3E%3C/svg%3E "National Taiwan University") National Taiwan University
 National Taiwan UniversityNational Taiwan UniversityNational Taiwan University
Our scholars are based at
National Taiwan UniversityNational Taiwan UniversityNational Taiwan UniversityNational Taiwan UniversityOur scholars are based at
National Taiwan UniversityNational Taiwan UniversityNational Taiwan UniversityNational Taiwan UniversityAreas of Expertise
Leading scholars with significant experience over 3 practice fields: The 3 “Cs” of Competition, Competitiveness, and Creative Destruction.
Competition of AI
The Domestic Angle
The domestic angle treats artificial intelligence as a question of American market structure, not only of foreign industrial policy. It brings three bodies of law to the same stack. Antitrust asks whether control of compute, cloud, data, and foundation models is hardening into durable power — through exclusivity, switching costs, and vertical ties that rivals cannot match. Intellectual property asks when training on protected works is a fair use that spreads capability, and when it is substitution that starves the authors on whom the next generation of models depends. Consumer protection asks whether the interfaces through which households and firms meet these systems are truthful, contestable, and free of designs that convert attention into lock-in.
The stakes are already measurable. Epoch AI estimates that five U.S. hyperscalers — Amazon, Google, Meta, Microsoft, and Oracle — own more than 70 percent of global AI compute, with Google alone holding roughly a quarter. The OECD reports that the five largest U.S. technology firms spent $400 billion on capital expenditure in 2025 and are forecast to spend $660 billion in 2026, a scale that can diffuse innovation if access stays open and can foreclose it if the stack closes. Downstream, payments for access to foundation models exceeded $37 billion in 2025, tripling in a year, while nine in ten firms in Y Combinator’s summer 2025 cohort were AI-native and nearly all depended on three model providers. A domestic policy equal to that structure protects consumers from deception, keeps fair use as a doctrine that rewards transformative use rather than a blanket exemption or a blanket ban, and treats concentration as a risk to the diffusion of innovation — not as a trophy of scale.
Competitiveness of AI
The Global Angle
The global angle treats artificial intelligence as a traded system, not a domestic market with a foreign footnote. It covers the law and policy of cross-border commerce in chips, models, data, and cloud capacity; the supply chains that run from lithography and memory through foundries and packaging to power and undersea links; and the rivalry among the United States, China, and other powers over who sets the terms of access. Industrial policy sits inside that frame — subsidies, export controls, investment screening, and standards — alongside the market-access question of whether those tools secure critical assets or close markets that innovation needs to stay open.
The geography of capability is already stark. Epoch AI’s inventory of GPU clusters puts the United States at about three-quarters of recorded cluster performance, China at about 15 percent, and the European Union under 5 percent. Upstream, the stack narrows to a single firm: ASML is the only maker of the extreme-ultraviolet machines required for leading-edge chips, each tool drawing on more than 100,000 parts and roughly 2,000 suppliers. Governments are already spending against that concentration. The U.S. Commerce Department has awarded $30.9 billion under the CHIPS Act toward lifting America’s share of leading-edge logic manufacturing from zero in 2022 to about 20 percent by 2030, while OECD figures show Chinese support for its chip firms reaching close to 10 percent of sales in the early 2020s. A competitiveness policy equal to that structure secures the assets rivalry can cut off, keeps market access open enough for innovation to diffuse, and treats standards as a commons to be protected — not as an instrument for shutting rivals out.
Creative Destruction of AI
The Regulatory Angle
The regulatory angle treats artificial intelligence as a problem of institutional design, not of prohibition. It covers pro-innovation regulation — rules that police fraud, safety, and deception without freezing the entry on which creative destruction depends — and the unintended consequences of statutes written faster than the technology they name. It also covers fragmentation: federal, state, and foreign regimes that define the same system differently, so a firm scaling across borders inherits several compliance stacks rather than one intelligible duty.
The volume of rules is already a fact of market structure. In 2025 every U.S. state introduced AI-related bills, 1,208 in all, of which 145 became law; by March 2026 a further 1,561 had been introduced in 45 states. Globally, one tracker counts 1,142 AI instruments across 110 jurisdictions, 668 of them already in force, with the United States alone accounting for 271 once state law is included. Europe shows the same strain in the calendar: transparency duties under the EU AI Act applied from August 2026, while the standalone high-risk obligations were pushed to December 2027. A regulatory policy equal to creative destruction prefers innovation principles to the precautionary principle, and simplification to accumulation — clear duties an entrepreneur can read, meet, and scale under, rather than a patchwork that taxes entry more heavily than it disciplines harm.
The journey
Creation of the GW Competition & Innovation Lab at The George Washington University.
Launch of the GW Competition & Innovation Lab at GWU. 40 Senior Fellows, 6 Regional Initiatives, and institutional collaborations with the OECD, the ABA, the WTO, and the G7.
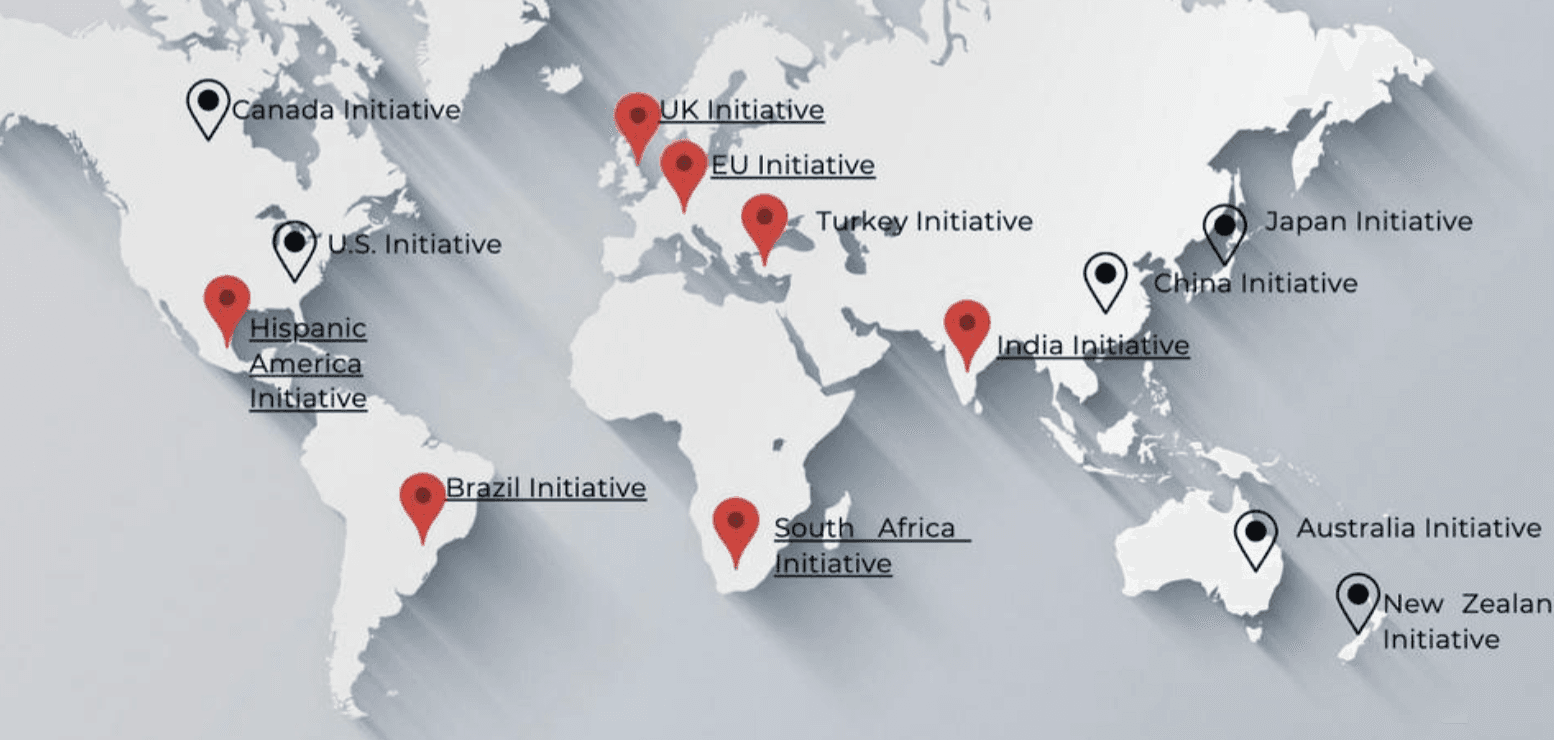
The GW Competition & Innovation Lab becomes an influential global center: 8 Regional Initiatives, 62 publications, 32 events, and further partnerships.
Thanks to the success of the GW Competition & Innovation Lab, the ambition becomes more global and focused on artificial intelligence: the seed-funding phase for the launch of the Global AI Competition & Innovation Lab.
Launch of the Global AI Competition & Innovation Lab, an independent research and consulting center with Senior Scholars coming from a network of leading universities
Scroll to continue
© 2026 Global AI Competition & Innovation Lab
© 2026 Global AI Competition & Innovation Lab
© 2026 Global AI Competition & Innovation Lab